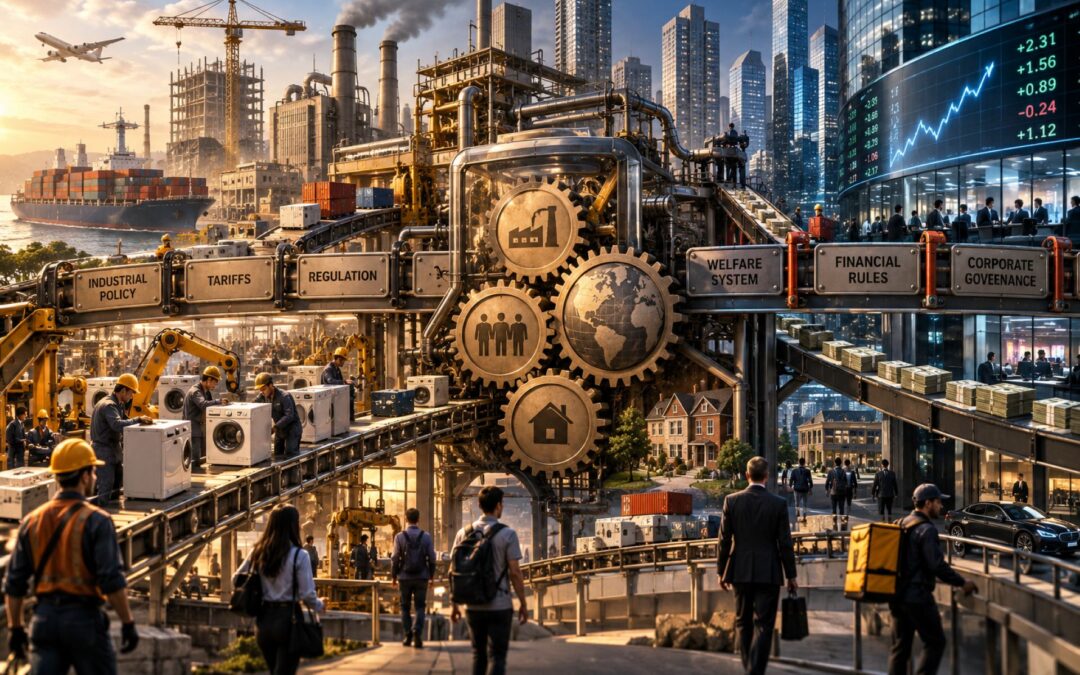
Published in 2010, in the immediate aftermath of the global financial crisis, Ha-Joon Chang’s 23 Things They Don’t Tell You About Capitalism arrived at a moment when ideas that had been treated as economic common sense suddenly looked much less secure. The crisis had required governments to rescue banks, guarantee financial systems, expand public spending and use extraordinary monetary measures—actions that sat awkwardly beside three decades of rhetoric about self-correcting markets and the dangers of state intervention. Chang uses that contradiction as the starting point for a much broader argument about how capitalism actually works.
Despite its combative title, this is not an argument for abolishing capitalism. Chang explicitly regards capitalism as the best economic system humanity has yet devised. His target is a particular version of capitalism: the free-market model that became increasingly influential from the 1980s onward and that presents deregulation, privatisation, liberalised trade and finance, weak welfare provision, low taxes on the rich and limited industrial policy as the natural route to prosperity.
Chang’s most important contention is that this supposedly natural order is nothing of the kind. Markets are created by political rules. Wages are shaped by institutions and borders as much as individual productivity. Companies do not necessarily serve society best when they maximise shareholder returns. Governments sometimes fail spectacularly, but so do firms and financial markets. Welfare states can increase rather than suppress economic dynamism. Education, entrepreneurship and sophisticated finance are not automatic engines of development. Even apparently technical questions about executive pay, inflation, manufacturing or immigration depend on political choices about whose interests matter and what kind of economy a society wants.
The book develops this case through 23 deliberately provocative “Things.” Each begins by presenting a familiar free-market proposition and then challenging it with history, comparisons, institutional analysis and counterexamples. The chapter titles often sound more absolute than the arguments themselves: Chang does not claim that education is useless, that inflation is harmless, that governments always select successful industries, or that the internet has been unimportant. His method is to attack an assumption forcefully enough that readers are pushed to examine what had previously seemed obvious.
That distinction matters because the book’s lasting value lies less in treating all 23 claims as final truths than in learning how to interrogate economic claims that are presented as inevitable. Some of Chang’s arguments have gained substantial support since 2010. Others need more qualification after the return of inflation, the expansion of digital technologies and AI, the changing structure of global finance and renewed debate over industrial policy. Read as a complete work rather than a collection of contrarian slogans, 23 Things They Don’t Tell You About Capitalism is ultimately a book about institutions, power and economic possibility.

23 Things They Don’t Tell You About Capitalism: Complete Book Summary
Chang begins with the financial crisis, but the book rapidly expands beyond banking. His larger purpose is to challenge the assumptions through which free-market capitalism is justified: that markets can be separated from politics, that prices reliably reflect merit, that individuals generally know what is best for themselves, that firms should serve shareholders first, that governments are unusually bad economic decision-makers, and that liberalisation naturally leads to growth.
The chapters are individually readable, and Chang even suggests different reading routes for readers interested in capitalism, politics, living standards, inequality or development. Taken in order, however, they reveal a cumulative argument. The early chapters challenge the intellectual foundations of the free-market view; the middle chapters apply that critique to development, inequality, industry and education; and the final chapters build toward a positive case for planning, welfare provision, financial restraint and more active government.
Things 1–5: Markets, Companies, Wages, Technology and Human Motivation
Thing 1: There is no such thing as a free market. Chang starts with the proposition on which almost everything else depends. Free-market advocates often describe regulation as an external interference with an otherwise natural arena of voluntary exchange. Chang argues that this is conceptually wrong because markets exist only after societies decide what may be traded, who may trade it, under what conditions contracts will be enforced and which rights cannot be sold.
He illustrates the point with nineteenth-century arguments over child labour. Restrictions that now appear morally obvious were once attacked as violations of freedom of contract. A factory owner and the parents of a child might both have agreed to employment, yet societies eventually decided that the transaction should be prohibited. The same logic applies to restrictions on slavery, drugs, organs, votes, public offices and many other things that modern economies do not treat as ordinary commodities. Once a rule becomes morally accepted, Chang argues, people stop seeing it as a restriction on markets at all.
He extends the argument to wages, immigration, product standards and interest rates. Rich countries that celebrate flexible labour markets nevertheless impose extremely strict controls on who can enter those markets through immigration laws. Central banks influence interest rates. Governments determine safety regulations, professional qualifications, minimum wages and trading rules. Even the distinction between “free” and “fair” trade depends on prior moral and political judgments about acceptable competition.
The financial crisis provides Chang with a dramatic contemporary example. Governments that had spent years defending private-market discipline intervened massively to prevent the collapse of financial institutions. For Chang, this does not prove that markets are useless; it proves that markets are always embedded in political arrangements. The real debate is therefore not government intervention versus a pristine free market. It is which rules should govern markets, whose interests those rules serve and what outcomes society is willing to accept.
Thing 2: Companies should not be run in the interest of their owners. Chang next turns from markets in general to corporations. Conventional shareholder-value theory begins from the idea that shareholders own a company and bear the residual risk after workers, suppliers and lenders receive their contractual payments. Because shareholders benefit when profits rise and suffer when the company fails, the theory says that managing companies for them should align corporate incentives with efficiency.
Chang traces the history of the limited-liability company to show why this reasoning is incomplete. Limited liability allowed capitalism to mobilise vastly larger pools of capital because investors could lose only the amount they invested rather than their entire personal fortunes. Joint-stock companies could therefore gather resources on a scale that traditional owner-managed businesses could not. This was one of the institutional innovations that made modern industrial capitalism possible.
Yet the same arrangement that makes shareholders willing to invest also makes them unusually mobile. Workers may have firm-specific skills, suppliers may depend heavily on a company, communities may rely on its jobs and infrastructure, and managers may build careers around it. Shareholders can often sell their stakes quickly. Chang therefore questions why the stakeholder with the easiest exit should automatically be treated as the one whose interests deserve priority.
His central target is the shareholder-value revolution that accelerated in the United States and Britain from the 1980s. Companies were encouraged to maximise short-term profits, distribute more of those profits through dividends and share buybacks, cut labour and investment costs, and align executives with shareholders through stock-based compensation. Chang argues that this can create a coalition between senior managers and mobile investors against the long-term productive capabilities of the firm. A company may look financially successful while underinvesting in research, training, equipment and organisational resilience.
His conclusion is not that shareholders should have no rights. It is that companies are long-lived institutions embedded in networks of employees, suppliers, creditors and communities. Corporate governance should therefore protect long-term stakeholders rather than assume that maximising immediate shareholder returns automatically maximises social welfare.
Thing 3: Most people in rich countries are paid more than they should be. Chang deliberately chooses an inflammatory title to attack the idea that wages reveal individual productivity. He compares a bus driver in Stockholm with a bus driver in New Delhi. The Swedish driver may earn dozens of times more, but Chang asks whether anyone seriously believes the Swedish worker drives dozens of times better, works dozens of times harder or possesses dozens of times more talent.
In some respects, the driver in the poorer country may perform a more difficult job. Roads may be worse, traffic less orderly, vehicles older, schedules less predictable and pedestrians, animals and informal transport more difficult to navigate. Yet the worker earns dramatically less. The explanation cannot therefore be individual productivity alone.
Chang identifies immigration controls as a crucial part of the answer. If workers from poorer countries could move without restriction into rich-country labour markets, many would compete for jobs at lower wages. Rich countries prevent this through some of the strongest labour-market restrictions in modern economies. Citizens then experience wages generated partly by this political exclusion as though those wages were simply their natural market value.
The deeper argument concerns collective productivity. Workers in rich economies operate inside systems containing better infrastructure, capital equipment, technologies, education, management, legal institutions, suppliers and accumulated organisational knowledge. Their individual earnings partly reflect the productivity of the society around them. Conversely, capable people in poor economies may remain unproductive because they lack access to those collective systems.
Chang therefore rejects explanations that blame poor countries on supposedly lazy, uneducated or unenterprising poor people. National prosperity is not simply the sum of personal virtues. A productive economic system makes ordinary people extraordinarily productive; an impoverished economic system can make talented people appear economically unproductive.
Thing 4: The washing machine has changed the world more than the internet has. Chang uses another deliberately provocative comparison to challenge technological recency bias. People living through a new technology naturally experience it as revolutionary because they directly observe its novelty. Older innovations have faded into the background even when they transformed everyday life more profoundly.
The washing machine stands for a wider collection of household technologies, including running water, vacuum cleaners, gas and electric cookers, refrigeration and other labour-saving appliances. In poorer societies, middle-class households have historically employed domestic servants because household labour is time-consuming and labour is relatively cheap. In richer societies, domestic technologies transformed this relationship by reducing the amount of human labour needed to clean, wash, cook and maintain a home.
Chang emphasises the consequences for women. Mechanising domestic work reduced the time required for unpaid household labour and contributed to the transformation of female participation in paid employment. These technologies altered family structure, labour markets and social expectations in ways that are easy to underestimate precisely because they are now ordinary.
He then compares the internet with the telegraph. Before transatlantic telegraphy, messages crossing the ocean took the time required to physically transport them. Telegraph cables reduced communication delays from weeks to minutes. The internet made communication cheaper, richer and more convenient, but the proportional reduction in transmission time was less dramatic because electronic long-distance communication already existed.
Chang’s purpose is not to deny the usefulness of the internet. He is warning against allowing excitement about recent technologies to distort economic strategy. In 2010, he was particularly concerned that Britain and the United States were embracing the idea of a weightless “knowledge economy” while treating manufacturing as obsolete. He argues that technological importance should be judged by actual changes in productivity, labour, social organisation and material life rather than novelty.
Thing 5: Assume the worst about people and you get the worst. Free-market economics often begins from self-interest. Adam Smith’s famous butcher, brewer and baker supply others not primarily from benevolence but because exchange serves their own interests. Modern versions of the argument extend this assumption into models in which employees may shirk, managers may pursue their own status, politicians may seek votes and bureaucrats may expand their organisations unless incentives constrain them.
Chang accepts that self-interest is real. People cheat, shirk, exploit information and pursue material advantage. His objection is to treating self-interest as the only motivation on which institutions can safely be built.
Organisations function because people routinely do things that cannot be perfectly enforced through contracts. Workers help colleagues, managers take responsibility beyond measurable performance targets, professionals maintain standards when nobody is watching, and traders honour obligations when opportunism might offer a short-term advantage. Trying to specify and police every possible action would create enormous monitoring and transaction costs.
Chang also rejects the claim that apparently moral behaviour can always be reduced to concealed self-interest. Reputational incentives and repeated interactions certainly matter, but people are also motivated by loyalty, fairness, identity, professional pride, duty and reciprocity. Institutional design can strengthen or weaken these motives.
The danger of assuming universal opportunism is that organisations may create the behaviour they expect. If employees are treated as people who will cheat whenever surveillance weakens, trust can erode. If executives are told that their only responsibility is to maximise their own financial rewards while serving shareholder returns, social obligations can become harder to defend. Chang therefore argues for an economic system that recognises mixed human motivations and deliberately cultivates cooperation rather than designing institutions exclusively around fear and greed.
Things 6–12: Stability, Development, Globalisation, Industry and the State
The next seven chapters move outward from the foundations of markets and firms into macroeconomic policy and national development. Chang’s central question is why policies advertised as growth-enhancing—low inflation, liberalisation, financial openness, deindustrialisation and reduced state intervention—have so often failed to produce the results their advocates predicted.
He repeatedly turns to economic history because development theories are easiest to evaluate against countries that actually became rich. This produces some of the book’s strongest challenges to conventional policy, but it also introduces a recurring methodological problem: historical success under interventionist policies demonstrates that such policies can work, not that they will always work.
Thing 6: Greater macroeconomic stability has not made the world economy more stable. Chang begins by distinguishing hyperinflation from ordinary inflation. Hyperinflation can destroy a monetary economy because prices change too rapidly to function as meaningful signals or stores of value. His examples include Weimar Germany, postwar Hungary and later episodes such as Zimbabwe. He does not argue that inflation is inherently harmless.
His target is the elevation of very low inflation into the dominant definition of macroeconomic stability. From the 1980s onward, governments were encouraged to restrain public spending, empower politically independent central banks and accept high interest rates when necessary to suppress inflation. By the 1990s and early 2000s, many countries had achieved dramatically lower inflation.
Chang asks what was gained in return. Low consumer-price inflation did not eliminate financial bubbles, banking crises, unemployment or insecurity. In many developing countries, tight macroeconomic policies also discouraged investment. Financial systems could become increasingly unstable even while the consumer-price index looked reassuringly calm.
The 2008 crisis gives the chapter its force. Economies that had satisfied orthodox inflation targets experienced catastrophic financial instability because policymakers had treated stable prices as evidence of broader stability. Chang’s distinction is therefore between price stability and systemic stability. An economy can achieve the first while failing badly at the second.
He also questions whether moderate inflation necessarily damages growth to the degree often implied in policy debates. The point is not that policymakers should pursue inflation for its own sake but that an obsession with driving inflation toward extremely low levels can impose costs through unemployment, weak investment and reduced policy flexibility. Stability should be judged more broadly by employment, growth, financial resilience and economic security.
Thing 7: Free-market policies rarely make poor countries rich. Development economics is one of Chang’s central concerns, and this chapter delivers one of his most direct attacks on the policy package associated with liberalisation. He begins with two apparently unattractive country profiles containing protection, restrictions on foreign ownership, regulated finance and significant government intervention. Such characteristics would normally make a free-market analyst pessimistic.
The trick is that versions of these policies were used by countries that later became economic successes. Chang then widens the historical lens to the United States and other rich economies. Nineteenth-century America, despite later becoming one of the world’s strongest advocates of free trade, used high tariffs extensively during industrialisation. Britain liberalised more fully only after establishing industrial supremacy. Japan, South Korea and Taiwan used combinations of trade protection, directed credit, industrial targeting and restrictions on foreign investment during major phases of development.
Chang calls attention to what he elsewhere describes as “kicking away the ladder”: rich countries recommending policies to developing countries that differ from the policies they themselves used while catching up. Free-market defenders can reply that these economies grew despite intervention rather than because of it, and Chang acknowledges that natural resources, market size and other factors matter. His counterargument is comparative. Interventionist development was not an isolated American accident but appeared repeatedly across successful industrialisers.
He also contrasts developing-country performance before and after the neoliberal reform era. His argument is that growth in many poorer regions slowed rather than accelerated after liberalisation, even though the reforms were explicitly justified as pro-growth measures. China and India, often cited as liberalisation successes, did open parts of their economies but did not adopt the full policy package of unrestricted trade, capital flows and state withdrawal.
The chapter therefore rejects the notion that development is primarily a matter of removing government-created distortions. Poor countries often need to build productive capabilities that do not yet exist, and temporary protection, credit policy, state enterprises or industrial support can form part of that process.
Thing 8: Capital has a nationality. Globalisation is often described as a process through which national ownership becomes economically irrelevant. Multinational corporations operate in many countries, managers come from different backgrounds, production networks span continents and capital can cross borders rapidly. Chang does not dispute these developments, but he argues that they are often exaggerated into the belief that corporations have become genuinely stateless.
He opens with Carlos Ghosn, whose Brazilian birth, Lebanese family background, French education and leadership of Japanese automaker Nissan make him an almost ideal symbol of transnational corporate life. Yet Chang argues that multinational companies still display strong home-country biases.
The Daimler-Chrysler merger illustrates the point. It was initially presented as a combination of equals, but control gradually revealed the predominance of the German side. Strategic functions, high-level management, research and supplier relationships often remain clustered around the country where a corporation originated or where controlling interests are concentrated.
Chang offers several reasons. Managers and owners possess stronger information about domestic institutions and suppliers. Corporate cultures are historically embedded. Governments may exert informal or formal pressure. National loyalties do not disappear simply because executives pursue profit.
This matters for policy because foreign ownership can affect where high-value functions are located and how companies behave during restructuring. Chang does not argue that foreign investment is inherently bad. He argues that governments should not assume ownership nationality is irrelevant when deciding whether to sell strategic companies or how to negotiate with foreign investors. Capital may be internationally mobile, but it is not automatically detached from national institutions and interests.
Thing 9: We do not live in a post-industrial age. Falling manufacturing employment in rich countries is often interpreted as proof that advanced economies have progressed beyond industry into services and knowledge. Chang argues that this confuses employment shares with economic importance.
Manufacturing can shrink as a share of employment precisely because manufacturing productivity rises faster than service productivity. A factory that once required hundreds of workers may produce more goods with dozens. Meanwhile, many services—haircuts are Chang’s intuitive example—remain labour-intensive because their basic production process cannot be accelerated indefinitely. As manufactured goods become relatively cheaper, manufacturing’s nominal share of the economy may decline even when societies consume more physical products.
Some apparent service-sector growth also reflects statistical reclassification. Activities once performed inside manufacturing firms, such as cleaning, catering, design or logistics, may be outsourced to specialist companies and recorded as services even though they remain connected to industrial production.
Chang then asks whether deindustrialisation matters. If it merely reflects extraordinary productivity growth in domestic manufacturing, it need not be disastrous. But if domestic industry is losing technological competitiveness against foreign producers, the consequences are more serious. Manufacturing historically offers strong opportunities for productivity growth, technological learning and international trade. Because many services are harder to export, excessive dependence on them can also create balance-of-payments constraints.
He is particularly sceptical of the idea that developing countries can skip industrialisation and move directly from agriculture into high-value services. India’s outsourcing success does not imply that service exports can employ or transform an entire low-income economy. For Chang, manufacturing remains an essential platform for broad productivity growth.
Thing 10: The US does not have the highest living standard in the world. Chang uses the United States to question how living standards should be measured. Americans are often described as enjoying the world’s highest standard of living because US incomes are extremely high. Yet comparisons change depending on exchange rates, purchasing power and what people must purchase privately rather than receive collectively.
Chang notes that several countries can outrank the United States on particular income measures. More importantly, averages conceal distribution. Because American income inequality is high among rich economies, average national income may describe the life of the typical person less accurately than it would in a more equal country.
Working time matters too. A person earning more because they work substantially longer hours has not necessarily gained an equivalent increase in welfare. Neither has someone who must spend significantly more on healthcare or other essential services that are publicly provided elsewhere.
Chang is not trying to prove that Americans live badly. His argument is that GDP per person should not be casually equated with welfare. Leisure, public services, health, security, inequality and the cost of necessities all affect how income translates into actual living conditions.
This chapter contributes to a recurring theme: prices and incomes are important, but they are not neutral measurements of human worth or social achievement. Institutional differences influence what people must buy, how much they work and how economic resources are distributed.
Thing 11: Africa is not destined for underdevelopment. Sub-Saharan Africa’s weak growth after the late 1970s generated explanations ranging from tropical disease and landlocked geography to ethnic fragmentation, colonial borders, resource dependence and cultural characteristics. Chang challenges the idea that any of these amount to an unavoidable destiny.
His most important move is historical. African stagnation was not constant. During the 1960s and 1970s, per-capita growth was positive and respectable even if it lagged behind the East Asian miracles. The major deterioration occurred later. A factor that remained constant cannot easily explain a sharp change in performance unless the mechanism connecting it to growth also changed.
Chang therefore turns toward policy. Many African economies underwent structural-adjustment programmes involving liberalisation, privatisation, fiscal restraint and reductions in state economic intervention. He argues that these policies damaged industrial capabilities, restricted investment and made economies more vulnerable rather than producing the promised acceleration.
He does not deny that geography and history matter. Tropical disease can reduce productivity, landlocked countries face transport disadvantages, conflict can spill across borders and resource wealth can produce destructive political incentives. His point is that none of these mechanisms is deterministic. Other countries have overcome major geographic or historical disadvantages through institutions, technology and policy.
Africa therefore should not be treated as a collection of countries suffering immutable structural curses. Chang wants policy discussion to focus on transformable productive institutions rather than fatalistic explanations that conveniently absolve contemporary economic strategies.
Thing 12: Governments can pick winners. One of the strongest free-market objections to industrial policy is that governments lack the information required to identify industries worth supporting. Chang answers with examples in which states did exactly that, while also acknowledging famous failures.
He begins with projects that genuinely deserved scepticism. Developing governments sometimes built prestige factories or infrastructure without economic justification. Yet he contrasts these failures with South Korea’s POSCO steel company. When Korea decided to establish an integrated steel producer, the country lacked obvious comparative advantages: it did not possess major deposits of the necessary raw materials and had limited experience in steel production. Nevertheless, the state supported the project, which eventually became one of the world’s most efficient steel producers.
Chang places POSCO alongside Korean support for companies and sectors such as automobiles and electronics. Hyundai’s entry into automobile production once looked unrealistic. The wider East Asian development record supplies examples in which governments deliberately pushed firms into activities that current market signals did not favour because policymakers expected capabilities to develop over time.
The theoretical defence of industrial policy often claims that government officials cannot know more than entrepreneurs directly engaged in business. Chang responds that firms themselves routinely make expensive mistakes. Private investment decisions are not guaranteed correct merely because private money is involved. Large companies also select projects internally without relying on markets to determine every allocation.
Government need not possess perfect foresight. Agencies can consult firms, gather information, support experimentation, impose performance targets and withdraw assistance from persistent failures. Chang openly concedes that governments can pick losers and cites unsuccessful programmes even in countries known for strong industrial policy. His argument is therefore about possibility rather than infallibility: state failure is real, but it does not justify assuming that private allocation always dominates state-supported development.
Things 13–17: Inequality, Executive Pay, Entrepreneurship, Rationality and Education
The next cluster shifts toward distribution and individual capability. Free-market arguments often interpret economic outcomes as the result of individual choices: investors become rich because they create wealth, CEOs receive high pay because their decisions are unusually valuable, entrepreneurs drive growth, consumers know what they want and educated workers make countries productive.
Chang repeatedly turns those explanations inside out. Individual outcomes, he argues, depend on institutions, collective capabilities, bargaining power and the productive structures within which people operate.
Thing 13: Making rich people richer doesn’t make the rest of us richer. The argument for pro-rich policy is usually presented as a trade-off between present distribution and future growth. Investors and entrepreneurs need strong rewards. If taxes or regulations allow the rich to retain more income, they should save and invest more, creating firms, jobs and technologies. Poorer citizens may receive a smaller share of national income initially, but the total economy should grow enough to leave them better off.
Chang makes an unexpected historical detour through early Soviet industrialisation to show that the logic of sacrificing current consumption for investment is not uniquely capitalist. Soviet economist Yevgeni Preobrazhensky argued that agricultural surplus had to be transferred toward industrial investment. Different political systems can therefore share the belief that resources should be concentrated among those presumed most likely to invest them productively.
In capitalist economies, the modern version emerged strongly with tax reductions, deregulation and weakening labour power from the 1980s. Higher inequality was tolerated or encouraged on the assumption that greater rewards at the top would generate greater investment and faster growth.
Chang argues that the promised acceleration did not materialise. Growth in many countries slowed compared with the postwar decades even as inequality increased. Nor does additional income automatically flow from rich households into productive investment. It can support financial speculation, luxury consumption, asset-price inflation or accumulation without equivalent expansion of productive capacity.
This is why Chang says trickle-down economics fails twice. First, making the rich richer does not reliably make the economic “pie” grow faster. Second, even when the pie grows, market forces alone do not guarantee that the gains will trickle down sufficiently to lower-income groups. Distributional policy therefore cannot simply be postponed until after growth has occurred.
Thing 14: US managers are over-priced. If enormous executive salaries reflect market competition for rare talent, attempts to restrict them could damage firms by driving the most capable managers elsewhere. Chang asks whether observed pay differences genuinely reveal equivalent differences in productivity.
He compares US executives with earlier American managers and with contemporary executives in other rich capitalist economies. American CEO compensation rose dramatically relative to average-worker pay even though corporate performance did not improve by anything remotely resembling the same multiple. Managers in Japan, the Netherlands and other successful economies have historically earned much less than their US counterparts without obviously managing less competent companies.
Chang therefore interprets executive pay partly as an institutional and bargaining outcome. Boards that are supposed to discipline executives may be socially and professionally close to them. Compensation consultants can produce ratcheting effects because firms generally want to classify their executives as above-average performers. Stock options can reward managers for broad market increases rather than exceptional company-specific performance.
The problem becomes clearer when compensation is asymmetric. Executives who perform well can earn enormous bonuses, but executives who perform poorly are frequently protected by severance agreements, pensions and other contractual payments. The market that supposedly imposes strict accountability can therefore produce arrangements in which managers participate heavily in upside gains while bearing comparatively little downside risk.
Chang’s argument extends Thing 3. Market income should not automatically be interpreted as a precise measure of productive contribution. Institutions, governance rules and bargaining power influence pay at the top just as immigration controls and national productive systems influence wages lower down.
Thing 15: People in poor countries are more entrepreneurial than people in rich countries. Entrepreneurship is commonly celebrated as the scarce ingredient that separates dynamic economies from stagnant ones. Poor countries, in this view, need more people willing to take risks, start firms and exploit opportunities.
Chang observes that everyday life in many developing countries points in the opposite direction. Far more people must engage in self-employment, informal trading and tiny businesses because stable wage employment is scarce. Street vendors, repair workers, food sellers and countless other informal workers continually search for ways to earn income. Survival itself demands entrepreneurial improvisation.
This apparent abundance of entrepreneurship helped inspire enthusiasm for microcredit. Small loans promised to release the productive energy of poor people excluded from conventional banking. The extraordinary popularity of microfinance suggested that development might be achieved by giving millions of poor individuals enough credit to become successful micro-entrepreneurs.
Chang is deeply sceptical. Many micro-businesses operate in crowded, low-productivity activities with few technological or organisational advantages. When one borrower opens a small shop, success may simply divert customers from another nearby shop rather than increase aggregate productivity. Access to credit can help households manage their lives, but it does not automatically create scalable enterprises.
The richer economies are not rich because every citizen behaves like a heroic entrepreneur. They have institutions capable of turning individual initiative into collective productivity: modern firms, technologies, research systems, financial organisations, infrastructure and trained workforces. Innovation increasingly depends on teams and organisations rather than solitary inventors.
The developmental task is therefore not merely to awaken entrepreneurial spirit. Poor countries often possess plenty of it. They need productive organisations capable of making individual ingenuity economically powerful.
Thing 16: We are not smart enough to leave things to the market. Free-market arguments against regulation often assume that individuals understand their own circumstances better than governments do. Even if policymakers are intelligent, they cannot know every borrower’s needs, every investor’s risk tolerance or every firm’s opportunities. Restricting choices may therefore prevent beneficial transactions.
Chang answers with bounded rationality, associated especially with Herbert Simon. People are not necessarily foolish; they simply have limited capacity to process information and complexity. In a sufficiently complicated environment, even highly intelligent experts can make systematic mistakes.
Long-Term Capital Management provides a memorable illustration. The hedge fund employed exceptional financial talent and was closely associated with economists whose mathematical work had won the Nobel Memorial Prize. Yet LTCM came close to collapse in 1998 and required a rescue organised by the Federal Reserve because its failure threatened wider markets. Intelligence and technical sophistication had not eliminated vulnerability.
Modern finance magnifies the problem because contracts and derivatives can create layers of contingent risks that are difficult to understand even for specialists. Asking each individual to evaluate every possibility is unrealistic.
For Chang, regulation can therefore improve decision-making even when regulators do not possess superior detailed knowledge. Rules can reduce the number and complexity of choices that people must evaluate. A ban on an extremely dangerous financial product does not require regulators to know exactly which alternative investment is best for every person. It merely prevents a class of risks judged socially unacceptable.
This reverses the normal information argument against government. The question is not whether officials are omniscient. It is whether institutions can simplify environments in which nobody—including market participants—is capable of mastering all relevant information.
Thing 17: More education in itself is not going to make a country richer. Chang challenges one of the most widely accepted propositions in development policy: that increasing education automatically increases productivity and therefore economic growth.
He begins with comparisons that weaken a simple correlation. Some East Asian economies achieved spectacular growth despite initially modest educational indicators, while countries with higher literacy or schooling did much worse. Taiwan and the Philippines are one of his central contrasts. If formal education were the decisive growth engine, such outcomes would be difficult to explain.
Chang then distinguishes education’s human value from its productive value. Literature, history, philosophy, art and many other subjects can make people more informed, capable and fulfilled citizens without directly raising workplace productivity. Defending education therefore does not require pretending that every year of schooling produces a measurable economic return.
He also questions whether modern economies are uniquely “knowledge-based.” Every successful economy has depended on valuable knowledge. Ancient China’s technological knowledge, Britain’s industrial capabilities and Germany’s engineering expertise were all foundations of prosperity. The knowledge economy is not a new condition created by computers.
Higher education presents another complication. Switzerland became an exceptionally rich and technologically capable country despite historically lower university participation than might be expected from a simple human-capital model. Firms can create specialised knowledge through vocational training, apprenticeships, research and organisational learning rather than relying exclusively on university degrees.
Chang worries that richer economies may produce credential inflation in which jobs require degrees without becoming correspondingly more technically demanding. In developing countries, he argues that expanding schools and universities will not by itself create productive employment if the economy lacks firms and technologies capable of using educated workers.
The chapter’s real conclusion is therefore not “education does not matter.” It is that educational expansion must be connected to productive transformation. A country does not become rich simply by accumulating diplomas.
Things 18–23: Regulation, Planning, Opportunity, Welfare, Finance and Economics
The final six Things bring the institutional argument to its broadest level. Chang now asks what the national economy should be trying to accomplish, what governments can legitimately plan, what fairness requires, why welfare provision might increase adaptability, how finance should relate to production and why economic expertise itself needs to become more pluralistic.
The tone becomes increasingly constructive. By the end, the book is no longer merely debunking propositions associated with free-market capitalism. It is assembling the principles of a different capitalism.
Thing 18: What is good for General Motors is not necessarily good for the United States. Chang invokes the enormous role of Detroit’s automobile industry in American industrial history. During the Second World War, the productive capacity of US automakers was converted toward military production, contributing enormously to the Allied war effort. Industrial giants such as General Motors became symbols of national productive power.
By 2009, however, GM had entered bankruptcy and required massive government support. Chang accepts that rescuing the company could be justified by wider national considerations: allowing a firm with enormous employment, supplier and demand linkages to collapse during a financial crisis could intensify recession. Yet he uses GM’s history to reject the idea that a company’s private interest and the national interest are automatically identical.
Companies may find it privately rational to relocate production, avoid investment, reduce worker training or resist regulations whose broader social benefits exceed the costs to the individual firm. Governments therefore sometimes impose requirements that companies themselves would not voluntarily choose.
Chang cites South Korea’s famously burdensome licensing environment during its rapid development. At one point, opening a factory could require a daunting number of official permissions. Such rules may sound incompatible with dynamism, yet Korea industrialised rapidly. Chang does not celebrate bureaucracy for its own sake. He argues that the mere existence of regulations tells us little about whether they are economically harmful; their design and purpose matter.
Some regulations can solve collective-action problems. A firm may not want to train workers who can later leave for competitors, invest in costly pollution control or maintain production capacities with benefits that spill across the economy. Regulation can therefore force individually reluctant firms toward collectively beneficial behaviour.
Thing 19: Despite the fall of communism, we are still living in planned economies. The collapse of the Soviet bloc is frequently interpreted as proof that planning failed and markets won. Chang agrees that comprehensive Soviet central planning had profound weaknesses. The Soviet Union could achieve extraordinary feats in selected areas, such as space technology and military production, while failing to supply ordinary consumer goods reliably.
The underlying problem was excessive informational ambition. Central planners tried to determine too many production and allocation decisions, creating bottlenecks, weak consumer responsiveness and distorted incentives.
Chang’s next move is crucial: the failure of comprehensive planning does not mean planning itself disappeared. Capitalist governments plan infrastructure, education, research, energy systems, land use and strategic investments. During wars, capitalist countries have often extended planning dramatically because coordination through ordinary markets would be too slow or uncertain.
Some countries have also used indicative planning, in which governments coordinate expectations and investment without issuing Soviet-style compulsory production orders. Firms remain private, but public institutions help establish long-term priorities.
Most importantly, corporations themselves are planned economies. Inside a large company, divisions do not generally buy and sell every intermediate service to one another through continuously changing market prices. Senior management allocates budgets, sets targets, approves projects and determines strategy. A large portion of economic activity is therefore coordinated administratively even in highly capitalist societies.
For Chang, the meaningful question is not whether to plan. Every complex organisation plans. The question is what should be planned, by whom, at what level and with what mechanisms for correction.
Thing 20: Equality of opportunity may not be fair. Modern market societies generally endorse formal equality of opportunity. Legal barriers based on race, caste, gender or inherited status have been dismantled in many countries through long political struggles. Chang regards those achievements as indispensable.
He nevertheless argues that formal equality can coexist with profound substantive inequality. A competition in which everyone is legally allowed to participate is not necessarily fair if some contestants begin malnourished, poorly educated or chronically ill while others receive excellent nutrition, tutoring, healthcare and social connections.
South Africa after apartheid illustrates the distinction. Removing racist legal restrictions created essential new opportunities, but the economic legacy of apartheid could not disappear immediately. Extreme inequalities in wealth, education and neighbourhood conditions meant that nominally equal citizens entered market competition from radically unequal starting points.
Chang also discusses cases of exceptional upward mobility, such as individuals from poor backgrounds who overcome extraordinary disadvantages. Such examples show that mobility is possible, not that opportunity is equal. Using exceptional success to prove that structural disadvantages do not matter confuses possibility with probability.
He therefore argues that some redistribution of outcomes is necessary to create meaningful equality of opportunity. Nutrition, healthcare, education, income security and childhood conditions affect people’s capacity to compete. Pure formal equality can become a justification for inherited inequality if societies ignore the resources needed to make opportunity real.
This is not a demand for identical outcomes. Chang accepts that incentives and differences in effort matter. His argument is that meritocracy requires greater equality at the starting line than a minimally regulated market will normally produce.
Thing 21: Big government makes people more open to change. Welfare states are often criticised for reducing flexibility. Employment protection can make companies reluctant to hire, unemployment benefits can weaken incentives to find work and taxes can discourage investment. Chang challenges this by asking how people respond to economic change when losing a job threatens not only income but healthcare, housing, education and family security.
His analogy is bankruptcy law. Capitalist economies do not normally insist that failed entrepreneurs remain permanently ruined. Limited liability and bankruptcy procedures allow businesspeople to take risks because failure does not automatically destroy the rest of their lives. Chang argues that workers need an equivalent mechanism.
A strong welfare state separates job loss from complete social catastrophe. Unemployment insurance, healthcare, retraining and income support can therefore make workers more willing to tolerate technological change, trade competition and restructuring. People may accept flexible employment when they possess security outside a particular job.
The Nordic economies, especially Denmark’s “flexicurity” model, are central to the argument. Firms can adjust employment relatively easily, but workers receive extensive social insurance and active labour-market support. Security attaches less to the preservation of one specific job and more to people’s ability to survive transitions.
Chang therefore reverses the usual relationship between security and dynamism. Too little social protection can make citizens defensive because every economic change becomes an existential threat. A larger state may make capitalism politically and socially more adaptable precisely because it protects people from its disruptions.
Thing 22: Financial markets need to become less, not more, efficient. Financial-market efficiency is normally desirable because liquid markets allow money to flow rapidly toward better opportunities. Chang accepts that finance is essential. Modern industrial projects require ways to mobilise savings, distribute risk and bridge the time between investment and future returns.
His concern is that finance can become too liquid relative to the productive economy it finances. Factories, technologies, worker skills and organisational capabilities take years to build and cannot be redesigned instantly. Financial investors, by contrast, can sell assets within seconds. When capital becomes extremely mobile, managers and governments can face intense pressure to deliver immediate returns.
Iceland serves as a cautionary example. Before 2008, financial liberalisation helped create an enormous banking system relative to the country’s economy. The expansion looked like a successful new growth model until the global crisis exposed its fragility.
Chang links this to the broader explosion of financial assets, securitisation and derivatives. Financial innovation can improve risk management, but layers of complex instruments can also obscure risk and generate opportunities for leverage and speculation. Instruments famously described by Warren Buffett as potentially dangerous are part of Chang’s wider concern that financial complexity had outrun regulators’ and investors’ ability to understand it.
He does not want finance abolished. His concept is closer to “slow finance.” Transaction taxes, restrictions on some cross-border capital flows, tighter controls on financial products and greater resistance to short-term takeover pressures could make investors more patient. The objective is to reduce the speed mismatch between financial claims and productive investments.
Finance should serve long-term economic activity rather than force the productive economy to adapt to the time horizon of traders.
Thing 23: Good economic policy does not require good economists. The final Thing attacks the authority structure of economics itself. Chang notes that several East Asian economies achieved extraordinary development without relying heavily on economists trained in the particular free-market tradition that became internationally dominant.
Japan, South Korea, Taiwan, Singapore, Hong Kong and later China followed very different institutional arrangements, but their policymakers often relied on engineers, lawyers, bureaucrats and practitioners as well as economists. Their success suggests that sophisticated economic management does not require adherence to one theoretical school.
Chang then turns to the 2008 crisis. Economists, regulators and financial specialists possessed extraordinary mathematical and technical expertise, yet mainstream institutions largely failed to anticipate the scale of systemic danger. He invokes Queen Elizabeth II’s famous question during a visit to the London School of Economics: why had nobody seen the crisis coming?
His answer is not that economics is useless. Chang is himself an economist, and the entire book relies on economic reasoning. His objection is to intellectual monopoly. When one school becomes sufficiently dominant, assumptions can become invisible and contrary evidence can be dismissed as anomalous.
He points toward alternative traditions in economics—Keynesian, institutionalist, developmental, behavioural and others—that treat uncertainty, power, institutions and history more seriously than simple free-market models do. Good economic policy requires pluralism because economies are too complex to be understood through one theoretical lens.
The chapter completes the democratic argument introduced at the beginning. Citizens should not treat economic choices as technical matters that only experts can understand. Experts are necessary, but economic policy also involves values, institutions and political judgments. Ordinary people have both the capacity and the right to question the assumptions behind expert advice.
Conclusion: Chang’s Eight Principles for Rebuilding the World Economy
After dismantling 23 propositions, Chang closes by stating what he wants in their place. The first principle is that capitalism should be retained, but unrestrained free-market capitalism should be abandoned. Profit and markets remain extraordinarily powerful tools for coordinating economic activity. They are tools, however, not moral authorities. Different capitalist systems arrange taxation, welfare, finance, corporate governance and industrial policy differently, and societies should choose among them according to their goals rather than assume one model is universally optimal.
Second, economic institutions must recognise bounded rationality. The financial crisis demonstrated that complexity can exceed human capacity to understand risk. More disclosure alone cannot solve this problem because information is useful only when people can process it. Chang therefore favours restricting financial innovations whose broader social value cannot be demonstrated rather than allowing unlimited complexity and hoping market participants will evaluate it correctly.
Third, institutions should be designed to bring out better human motivations rather than assume universal selfishness. Material incentives matter, but economies also depend on trust, professionalism, loyalty and cooperation. Chang wants corporate and public institutions that reward socially useful behaviour instead of treating individual enrichment as sufficient evidence of social contribution.
Fourth, society should stop assuming that market income equals personal desert. Immigration controls, national productive systems, bargaining institutions and inherited circumstances profoundly affect earnings. At the bottom, genuinely equal opportunity requires adequate childhood nutrition, health and education. At the top, executive compensation should not be treated as automatically justified simply because boards and markets have produced it.
Fifth, Chang calls for renewed seriousness about manufacturing and productive capability. A “post-industrial” economy cannot live on ideas alone. High-value services frequently depend on industrial ecosystems, and poorer countries in particular need technologies, machinery, infrastructure, worker training and firms capable of producing tradable goods.
Sixth, the relationship between finance and the real economy must be rebalanced. Finance is indispensable, but its speed and liquidity can impose damaging short-termism on investments that require years to mature. Chang therefore advocates mechanisms that make capital more patient and reduce destabilising flows.
Seventh, government should become larger and more active where collective action requires it. This includes welfare provision, financial regulation, industrial policy, research, training and infrastructure. Chang does not deny government failure; he denies that government failure is uniquely disqualifying when markets and corporations fail as well.
Finally, the international economic order should give developing countries greater policy space. Rich countries historically used tariffs, industrial support and restrictions on investment while developing, yet modern trade and financial rules often restrict poorer countries from using similar tools. Chang therefore wants global rules that deliberately give developing countries greater freedom to protect infant industries, regulate foreign capital and pursue national development strategies.
The conclusion reveals the unity behind the book’s provocations. Chang is not proposing a return to central planning, nor does he reject markets, private property or profit. He wants capitalism treated as a consciously designed institutional system whose rules can be changed when they produce weak growth, instability, insecurity or unfairness.
The Book’s Core Argument: There Is No Neutral Free Market
Thing 1 is more than the first chapter. It provides the conceptual key to almost every argument that follows. Once markets are understood as institutions created by laws and social conventions, the political character of apparently technical economic outcomes becomes much easier to see.
A market requires property rights before anyone can exchange property. It requires contract law before promises become economically enforceable. It requires rules defining corporations, bankruptcy, fraud, acceptable products, working conditions, financial instruments and the rights of creditors and employees. Governments also decide whether children can work, whether organs can be sold, whether employers may discriminate and which professions require licences. None of these decisions is external to the market. Collectively, they constitute the market.
This does not mean every possible regulation is desirable. Chang’s argument is more fundamental: calling one arrangement “free” does not settle which arrangement is better. A labour market with unrestricted child labour is not inherently more economically authentic than one with compulsory schooling and a minimum working age. It merely embodies different political and moral rules.
That insight helps explain several later chapters. Immigration restrictions make Thing 3’s international wage differences possible. Corporate law makes Thing 2’s shareholder relationships possible. Intellectual-property rules, trade policy and financial regulation shape the developmental choices discussed in Things 7, 12 and 22. Social provision influences the labour flexibility described in Thing 21.
Readers unfamiliar with the standard building blocks of markets, incentives and government intervention may find it useful to place Chang’s challenge beside a broader explanation of basic economic concepts. Chang is not denying supply, demand or incentives. He is asking readers to notice the legal and institutional structure within which those forces operate.
This is also why his position differs from a simple demand for “more government.” Government already exists inside market institutions. Even a programme of radical deregulation requires governments to enforce property rights, company law and contracts while deciding which previous restrictions to remove. The political choice is never between constructed markets and no construction; it is between different institutional designs.
The idea is powerful because it undermines a common rhetorical asymmetry. When a government imposes a minimum wage, people immediately recognise political intervention. When it limits immigration, enforces a patent, permits a particular corporate structure or rescues a banking system, those interventions may become so familiar that they disappear into the background. Chang wants them made visible.
The implication is democratic as much as economic. If market outcomes depend on choices about rules, citizens are entitled to debate those rules. The statement that “the market demands” a particular outcome cannot by itself end the argument. Someone still has to ask which market, constructed under which laws, distributing which rights and risks.
How the 23 Things Connect: Institutions, Power and Collective Capability
The book repeatedly replaces individualistic explanations with institutional ones. Rich-country workers are not prosperous simply because each worker is exceptionally productive. Entrepreneurs do not create modern economies by heroic personal effort alone. Schooling does not generate growth unless productive organisations can use educated labour. Executives are not necessarily paid in proportion to their contribution. Economic outcomes emerge from systems.
Thing 3 provides the clearest illustration. The difference between the earnings of a bus driver in India and one in Sweden cannot plausibly be explained by individual driving ability. The Swedish worker benefits from an entire productive environment: roads, vehicles, public administration, physical capital, organisational competence, accumulated technology and the productivity of other people. Remove the worker from that environment and the income-generating capacity changes.
Thing 15 applies similar reasoning to entrepreneurs. Informal economies contain enormous quantities of personal initiative. The missing ingredient is often not courage or ingenuity but the institutions that turn effort into high productivity. A street vendor working twelve hours a day may display more entrepreneurial resourcefulness than an employee in a rich-country corporation, but the corporation combines thousands of specialised workers with equipment, research, finance, supply chains and accumulated knowledge. Collective organisation multiplies individual capability.
This is why Chang is sceptical of explanations that turn national development into a morality play. Poor countries are not simply populated by insufficiently educated or enterprising people. A country becomes richer by constructing productive systems that allow ordinary people to do economically valuable work.
Education illustrates the same point from another direction. Expanding universities can increase knowledge and opportunity, but graduates require firms and institutions capable of using specialised skills. Without productive demand, more qualifications can generate unemployment, emigration or credential inflation rather than technological transformation.
Power enters because institutions distribute opportunities unevenly. Immigration controls protect rich-country workers from global wage competition. Corporate governance gives some constituencies more control than others. Intellectual-property systems determine who can use knowledge. Labour law alters bargaining strength. Financial institutions determine which investments receive capital and on what time horizon.
Chang’s capitalism is therefore neither an aggregation of isolated individuals nor an autonomous machine called “the market.” It is a network of institutions that determines how individual capabilities are combined. That perspective explains why the book can defend entrepreneurship while criticising entrepreneurial mythology, defend markets while denying the existence of a pure free market, and defend capitalism while arguing for extensive collective intervention.
The concept also clarifies why Chang’s preferred policies are so often concerned with capability rather than immediate efficiency. Protecting an infant industry can look inefficient if the only question is which country can produce a good most cheaply today. It may look different if protection allows firms to learn technologies that make tomorrow’s economy more productive. Worker training, research, infrastructure and industrial finance have similar long-term characteristics.
This is one of the book’s deepest disagreements with the free-market view it attacks. Static efficiency asks whether resources are being allocated to their most valuable current use. Chang repeatedly asks a different question: what institutions will change what people and firms are capable of producing in the future?
Markets, Government and Planning
Chang’s argument about government is often easier to caricature than to state accurately. He is not claiming that public officials reliably know more than entrepreneurs, that political incentives are benign or that state projects normally succeed. Thing 12 contains failed industrial projects alongside POSCO, and Thing 19 treats Soviet planning as a genuine failure. His position is that the conventional comparison is unfair because government is judged against an idealised market rather than against real markets and corporations that also make mistakes.
Government and private business face different informational problems. Entrepreneurs may know their own firms better than civil servants, but they do not automatically internalise the wider consequences of their decisions. A company deciding whether to train workers, develop a supplier network or maintain strategic production capacity will compare private costs and benefits. The national economy may value spillovers that the company cannot capture.
Industrial policy emerges from this gap. Governments may support sectors where learning, technological development, coordination or strategic investment create benefits beyond an individual firm. The intellectual case has returned to mainstream policy debate in recent years. An IMF assessment of the renewed interest in industrial policy acknowledges legitimate rationales such as market failures and strategic externalities while warning that poorly designed programmes can generate fiscal costs, capture, misallocation and international spillovers. That combination of possibility and danger is closer to Chang’s actual argument than either “governments always know best” or “governments can never pick winners.”
State capacity is therefore crucial. POSCO cannot be converted into a universal recipe merely by observing that South Korea created a successful steel company. Policymakers need information, competent administration, mechanisms for monitoring performance, the ability to resist permanent subsidies to political allies and the willingness to terminate programmes that repeatedly fail. A state capable of doing these things is itself a developmental achievement.
Chang also broadens planning beyond industrial policy. Firms plan because complicated organisations cannot continuously renegotiate every internal relationship through markets. Senior managers allocate investment, define strategy and coordinate departments. That does not make a corporation socialist; it shows that markets and planning are complementary coordination mechanisms rather than ideological opposites.
The same applies at national scale, though with greater difficulty. Infrastructure requires long horizons. Electricity grids, transport networks and research institutions cannot be built solely by responding to moment-to-moment prices. Climate transition, defence and public health create coordination problems where government planning becomes difficult to avoid.
Thing 19 is strongest when it destroys the false binary between markets and plans. Soviet comprehensive planning failed partly because central authorities attempted to control an impossibly detailed set of decisions. From that failure it does not follow that every deliberate attempt to influence the future composition of an economy is futile.
Chang’s framework is better understood as institutional experimentation. Some decisions should be decentralised through markets. Others can be coordinated inside firms. Still others require public rules or investment. The challenge is not discovering one universally superior mechanism but matching mechanisms to problems while building feedback that exposes failure.
That approach also supplies a useful standard for criticising Chang. Whenever the book moves from “government can succeed” toward “this particular intervention should therefore be attempted,” the evidentiary burden rises sharply. Demonstrating that laissez-faire theory is too categorical is easier than determining which governments possess the competence to outperform markets in a specific sector.
Firms, Incentives, Inequality and Who Gets Paid What
Several of Chang’s most provocative chapters attack a moral inference that is often smuggled into economic reasoning: if a competitive market produces a particular income, that income reflects what the person contributed. Things 3, 13 and 14 challenge this at different levels, while Things 2, 18 and 20 examine the institutions that distribute power and opportunity.
Thing 3 undermines the simplest version of the productivity story. A worker’s output depends heavily on capital, infrastructure, colleagues and national institutions. Thing 14 makes a parallel argument about CEOs. Even if excellent managers are valuable, the scale of American executive compensation cannot simply be inferred from the scale of managerial talent because compensation is produced by governance structures that executives themselves can influence.
This does not prove that income differences are arbitrary. Skills, effort, scarcity and responsibility genuinely matter. Chang’s stronger point is that market prices cannot by themselves tell us how much of an income difference reflects those characteristics and how much reflects bargaining institutions, legal protections, historical circumstances or political power.
Thing 13 then asks whether high inequality can be defended instrumentally even if it is not morally deserved. Perhaps allowing the wealthy to capture a larger share stimulates investment so strongly that everyone ultimately benefits. This is the familiar trickle-down claim.
Later research has generally made that proposition harder to state confidently. An IMF study of inequality and growth found that increases in the income share of the richest 20 percent were associated with lower subsequent growth, while larger shares for poorer and middle-income groups were associated with stronger growth. The finding does not prove that every redistributive policy increases growth or that inequality never supplies useful incentives. It does support Chang’s central objection to the simple claim that enriching the top reliably creates enough extra growth to justify widening inequality.
Chang is particularly effective at separating incentives from entitlement. A society may decide that entrepreneurs need the possibility of becoming very rich because exceptional rewards encourage risk-taking. That does not mean the resulting fortune measures the person’s moral worth. Incentive structures can be useful institutional tools without being converted into theories of desert.
Corporate governance matters for the same reason. Shareholder-value systems give certain financial claims priority over employees, suppliers and long-term investment. Executive-pay systems can reward senior managers even after failure. Labour institutions determine bargaining power. Tax systems affect how market incomes translate into disposable income.
Thing 20 extends the argument backward to the starting point. If childhood nutrition, healthcare, schooling and family resources differ radically, later market competition does not isolate merit. Someone who succeeds after severe deprivation may be extraordinarily capable, but that does not demonstrate that everyone who failed had an equivalent opportunity.
Chang therefore treats distribution as both cause and consequence. Inequality affects education, health, political influence and willingness to tolerate economic change; those institutions then shape future market outcomes. A purely market-based explanation becomes circular when existing inequalities determine access to the resources needed to compete in the next round.
The danger is that Chang can occasionally move too quickly from demonstrating institutional influence to implying a preferred distribution. Showing that CEO pay is politically and institutionally shaped does not establish the ideal ratio between executives and workers. Showing that equal opportunity requires some redistribution does not tell us exactly how extensive redistribution should be. Those remain political and empirical questions.
Even with that limitation, the book’s central correction is important. Market outcomes are not verdicts delivered by an impartial tribunal. They are results generated by particular rules. Societies can evaluate those rules without denying that incentives and scarcity remain economically real.
Development, Manufacturing and Industrial Policy
Development is where Chang’s arguments become most systematic. Things 7, 9, 11, 12, 15, 17 and 19 all reject the idea that poorer countries can become rich primarily by improving the efficiency with which existing markets allocate existing resources. Development requires changing what an economy can produce.
That distinction explains his historical interest in manufacturing. Industrialisation does more than move workers from farms into factories. It creates opportunities for mechanisation, technological learning, quality control, supply-chain development, engineering competence and large-scale organisation. Productivity can rise repeatedly as firms master more complex production.
Services can also be sophisticated and productive, and modern digital industries complicate any simple manufacturing-versus-services division. Chang’s point is developmental rather than definitional. A country needs sectors capable of sustained learning and tradable output. In 2010, he believed manufacturing remained the most reliable broad platform for that process.
Thing 7 supplies the historical argument. The countries that now advocate open markets frequently industrialised behind tariffs and other interventions. That does not prove protection causes development: protection can preserve inefficient firms indefinitely. It does destroy the stronger claim that successful development has normally occurred through immediate exposure to unrestricted international competition.
The infant-industry argument depends on time. A new producer in a poorer country may initially be less efficient than an established foreign competitor because it has not yet learned the technology, trained workers, built suppliers or achieved scale. If free trade eliminates the new producer before learning occurs, current comparative advantage becomes self-perpetuating. Temporary protection may allow capability to develop.
The danger is obvious. “Temporary” protection can become permanent. Firms may invest more effort in lobbying governments than improving products. Consumers can pay high prices for poor goods. Political allies can capture subsidies. Chang recognises these possibilities but believes they are management problems rather than arguments against industrial policy in principle.
The return of industrial policy in the United States, Europe and other advanced economies after the pandemic, supply-chain disruptions and geopolitical tensions has made Chang’s insistence that governments inevitably shape industrial structure look less heterodox. Yet contemporary debate also reinforces the importance of state capacity. The same IMF analysis of industrial policy that recognises potential benefits stresses how demanding successful intervention is.
Thing 11 applies the capability perspective to Africa. Chang’s rejection of geographic and cultural fatalism remains persuasive because development history supplies too many exceptions to deterministic explanations. Yet his alternative emphasis on neoliberal reform should also be treated as one part of a larger causal story. Conflict, governance quality, commodity structures, health burdens, infrastructure, external debt and institutional capacity all interact with trade and industrial policy.
Thing 15 deepens the point by attacking entrepreneurial individualism. Evidence accumulated after the book’s publication has strengthened Chang’s scepticism toward microcredit as a transformation strategy. A J-PAL synthesis of seven randomized evaluations found no evidence of the sweeping reductions in poverty or transformative business growth once promised by the most enthusiastic microfinance narratives, although credit could still give households useful flexibility. That is remarkably close to Chang’s distinction between helping individual households and building a productive national economy.
Thing 17 makes a similar argument about education. Years of schooling are inputs, not development outcomes. The World Bank’s World Development Report 2018 placed heavy emphasis on the distinction between attending school and actually learning, reinforcing Chang’s objection to treating educational quantity as sufficient. At the same time, modern research makes it important to qualify his rhetoric: cognitive skills and learning quality can be economically valuable even when simple enrolment measures correlate weakly with growth.
The unifying concept is productive capability. Development requires firms that can organise complex activities, financial systems willing to support long-term investment, states capable of coordinating infrastructure and learning, institutions that train people appropriately and mechanisms that expose producers to enough pressure to improve.
This is why Chang resists policy universalism. A rich country with mature industries can survive competition that would destroy a young producer in a poorer economy. A developing country may need restrictions that become unnecessary later. International rules that require identical treatment of economies at radically different stages can therefore preserve rather than eliminate inequality.
The strongest version of Chang’s development argument is not that every country should copy South Korea. It is that countries need enough policy freedom to discover their own route toward higher productivity. The state cannot manufacture development by decree, but neither will development reliably emerge from merely removing the state.
Finance, Stability and Bounded Rationality
Things 6, 16 and 22 form a coherent theory of financial instability. Thing 6 argues that policymakers mistook low inflation for overall stability. Thing 16 argues that individuals cannot process unlimited complexity. Thing 22 argues that financial markets became faster, larger and more sophisticated than the productive economy they were supposed to serve.
The 2008 crisis gives this sequence its historical foundation. Before the crash, many advanced economies combined low consumer-price inflation with rapidly increasing leverage, property prices and complex financial instruments. Conventional measures of macroeconomic stability looked reassuring even as systemic risk accumulated elsewhere.
Chang’s bounded-rationality argument explains why simply adding disclosure is inadequate. A contract containing hundreds of pages can technically disclose risk while remaining functionally incomprehensible. A financial system can publish enormous quantities of data while becoming too interconnected for any individual institution to understand the consequences of collective behaviour.
Regulation can therefore be valuable by limiting complexity. Society already applies this principle outside finance. Manufacturers are not allowed to sell every conceivable drug, aircraft or food product and leave consumers to decide whether the risks are acceptable. Chang thinks financial innovation deserves similarly demanding scrutiny when private instruments can generate systemic losses.
His “slow finance” idea addresses time horizons rather than knowledge alone. Productive investment is intrinsically illiquid. A semiconductor plant, worker-training programme or new automobile platform requires years before returns can be evaluated. If financial investors can exit immediately and punish management whenever quarterly returns disappoint, companies may underinvest in projects whose social and private value appears only later.
This concern remains relevant. The Financial Stability Board’s 2025 monitoring report on non-bank financial intermediation reported that non-bank financial institutions accounted for more than half of global financial assets in 2024. That statistic does not prove Chang’s claim that finance is excessively large, because many non-bank institutions perform useful savings and investment functions. It does confirm that systemic financial activity has continued to expand outside traditional banking and that questions about leverage, liquidity and interconnectedness did not disappear after 2008.
The difficulty lies in distinguishing useful liquidity from destructive short-termism. Liquid markets allow savers to diversify risk and let capital leave genuinely failing projects. Making exit excessively difficult can trap resources inside politically protected or badly managed firms.
Chang sometimes writes as though longer commitment is inherently superior. It is better understood as a trade-off. Economies need enough liquidity to discipline bad investments and enough patience to finance investments whose value cannot be proven immediately. Financial design should balance these requirements rather than maximise liquidity as an end in itself.
Thing 6 requires similar balance. In 2010, Chang was responding to an era in which policymakers often appeared more alarmed by moderate inflation than by unemployment or financial bubbles. Later events remind us that price instability can itself produce large welfare losses. That does not invalidate his broader definition of stability; it makes the definition even more important. A resilient economy requires price stability, financial stability, employment and investment rather than allowing any one indicator to stand in for all the others.
Where the Book Has Aged: Inflation, Technology, AI and the World Since 2010
A book built around empirical economic claims should not be treated as if publication froze the evidence. Some of Chang’s arguments have become easier to defend since 2010, while others need significant qualification. The fairest assessment distinguishes the conceptual insight from the time-specific examples through which it was originally presented.
Thing 6 is the clearest case where later events demand a correction in emphasis. Chang was right that low inflation did not guarantee financial stability, and the 2008 crisis remains decisive evidence. Yet the post-pandemic inflation shock showed how damaging rapid price increases can be even when they remain far below hyperinflation. The IMF’s 2022 World Economic Outlook on the cost-of-living crisis documented the global surge in inflation, erosion of real incomes and difficult monetary tightening that followed the pandemic and energy-price shocks.
The later experience does not vindicate an obsession with extremely low inflation at any cost. It does weaken any reading of Chang that makes moderate or moderately high inflation sound relatively painless. Households with little financial protection can suffer badly when food, energy and housing costs rise rapidly. A broader conception of macroeconomic stability should therefore incorporate Chang’s financial concerns without downgrading price stability.
Thing 4 presents the opposite problem: the conceptual warning has aged better than the specific technology ranking. Chang’s point about recency bias remains valuable. The washing machine, sanitation, electricity and earlier communications technologies produced transformations so embedded in modern life that their magnitude is easy to forget.
The digital world of 2026, however, is not the digital world of 2010. Smartphones became ubiquitous, cloud computing altered business infrastructure, platform companies transformed advertising, retail and transport, remote work expanded dramatically during the pandemic, and generative AI became a general-purpose technology with potential implications for a wide range of cognitive tasks. The World Bank’s 2025 report on AI foundations treats artificial intelligence and digital infrastructure as major forces affecting productivity, work, firms and development.
That does not establish that “the internet” has now unambiguously surpassed household electrification or mechanised domestic work in historical importance. Such comparisons depend on what is being measured. It does mean that Chang’s 2010 empirical judgement cannot simply be carried forward as though the subsequent sixteen years had not happened.
Thing 13, by contrast, has aged strongly. The claim that giving the rich a greater share of income does not reliably accelerate growth has received substantial support from later institutional research, including the IMF work on inequality and growth. Debate continues over taxation, incentives and causal mechanisms, but simple trickle-down formulations now have far less empirical confidence behind them than their political prominence once suggested.
Thing 15 has also been strengthened. Microcredit still has legitimate uses, particularly for household liquidity and some businesses, but expectations of a general entrepreneurial revolution have moderated. The later randomized evidence summarised by J-PAL fits Chang’s argument that financing millions of tiny enterprises is not the same as constructing an economy of productive, innovative firms.
Thing 17 requires a more mixed verdict. Chang correctly attacks the assumption that years of schooling mechanically translate into development. Modern education research has increasingly emphasised learning quality rather than enrolment alone. The World Bank’s education research is particularly compatible with this point. Yet human capital remains economically important, especially when education develops literacy, numeracy, technical skill and adaptive capacity. The safest update is therefore that schooling alone does not create development, not that education has only a minor role.
Thing 21’s mechanism remains plausible and important. The idea that social insurance can make workers more willing to accept change continues to be illustrated by countries that combine flexible labour markets with strong welfare systems. The OECD’s analysis of Denmark continues to describe a labour market characterised by substantial mobility alongside broad social protection and active labour-market policies. The model has its own costs and cannot simply be transplanted, but it supports Chang’s rejection of the claim that security and flexibility must be opposites.
Thing 10’s challenge to income-only measures of welfare has also aged well. The United States remains extremely wealthy, but high national income does not automatically translate into dominance across health, leisure, distribution or security. Contemporary OECD health indicators for the United States show outcomes such as life expectancy and avoidable mortality that compare less favourably with other wealthy countries. Chang’s exact 2010 rankings are historical, but the analytical distinction between income and broader living standards remains robust.
Industrial policy is perhaps the most striking intellectual shift. When Chang wrote, explicit sectoral intervention was frequently dismissed in mainstream discussion as an outdated strategy associated with inefficient developing states. By the mid-2020s, semiconductors, clean energy, supply-chain resilience, strategic minerals and national security had returned industrial policy to major economies. The debate now often concerns how to design such policy rather than whether governments should ever influence industrial structure.
This revival does not prove Chang right about every intervention. In some ways it raises the stakes of his critics’ questions: how can governments prevent lobbying from turning industrial policy into corporate subsidy? How should international retaliation be handled? What happens when every major economy tries to subsidise the same strategic sectors? The modern debate validates Chang’s insistence that industrial policy is possible while reinforcing how difficult good industrial policy is.
The book’s treatment of finance also remains relevant. The post-2008 period produced tougher bank regulation in many jurisdictions, but financial complexity migrated as well as disappeared. Non-bank institutions, private credit, asset managers and new forms of digital finance expanded. Chang’s concern that risk can move into areas where oversight is weaker remains a live question even though the specific instruments attracting attention have changed.
Globalisation complicates Thing 8. Multinational corporations have become even more internationally integrated, and production networks are highly dispersed. Yet geopolitical tensions, semiconductor controls, sanctions, pandemic supply disruptions and government pressure on strategic companies have made corporate nationality newly visible. The idea of a completely borderless corporation looks less convincing when states treat technology, data, energy and supply chains as national-security concerns.
Several of Chang’s 2010 examples therefore need updating without changing the central structure of his case. The book is strongest when it identifies institutional mechanisms that continue to operate under new conditions. It is weakest when a provocative empirical comparison is allowed to sound timeless.
Evidence, Method and the Power of Chang’s Contrarian Arguments
Chang is an unusually effective popular economic writer because he understands that many theoretical disputes become clearer through stories. Child labour makes market regulation concrete. Swedish and Indian bus drivers expose the limits of individual-productivity explanations. Washing machines make technological change visible in everyday life. POSCO turns industrial policy from an abstraction into a risky historical decision.
The method is pedagogically powerful because it reverses intuition. Readers are first shown something that appears obvious, then given an example that does not fit. Once the exception is undeniable, the original theory has to be reformulated.
This is especially effective when Chang is attacking universal claims. If someone says governments cannot pick successful industries, one strong counterexample is enough to disprove the word “cannot.” If someone says a free market exists wherever government interference is minimal, the unavoidable existence of rules about property, contract and permissible trade creates a serious conceptual problem.
The evidentiary burden changes, however, when Chang moves from destroying a universal claim to establishing a causal alternative. Showing that South Korea successfully supported POSCO proves that government industrial policy can work. It does not by itself prove how much of Korea’s overall development was caused by industrial policy, whether another strategy could have performed better, or whether governments with weaker institutions should attempt similar interventions.
Historical comparisons create the same difficulty. Rich countries used protection during development, but they also differed in geography, institutions, education, politics, market size, technology and access to resources. It is rarely possible to isolate one policy through historical narrative alone.
This is where the book’s rhetorical confidence sometimes exceeds the precision of its evidence. Chang generally knows the qualifications, and individual chapters often state them, but the chapter titles deliberately sharpen claims to make them memorable. The risk is that readers remember “governments can pick winners” or “education will not make a country richer” more clearly than the conditions and distinctions developed in the argument.
Paul Mason’s contemporary critical review of the book captured part of this tension. Mason admired Chang’s ability to unsettle free-market assumptions while questioning whether the book fully confronted the historical failures and stagnation that can occur under heavily state-directed capitalism. That is an important objection because disproving laissez-faire does not automatically validate every alternative form of intervention.
Chang’s response is partly contained in the book itself. He openly rejects Soviet central planning, recognises government failure and insists that capitalism should remain. His preferred model is not one in which officials replace markets but one in which markets operate inside stronger social and developmental institutions.
Even so, the book gives much more space to showing that interventions can succeed than to specifying the institutional conditions under which success is likely. Readers looking for a detailed theory of bureaucratic capacity, political capture or policy evaluation will need to go beyond it.
The empirical style also reflects the book’s intended audience. Chang uses statistics, but this is not an econometric treatise. Case studies, comparisons and historical anomalies do much of the argumentative work. That makes the book highly readable, but readers should distinguish three different achievements: demonstrating that free-market assumptions are not universally true, offering plausible alternative mechanisms, and proving the magnitude of those mechanisms empirically. Chang is strongest at the first, frequently persuasive at the second and more uneven at the third.
This unevenness does not cancel the achievement. Economic debate can become trapped when one model determines which questions are considered legitimate. Chang’s examples reopen questions that had been treated as settled. In a popular book, that is a considerable intellectual contribution.
Style and Organisation: Why the Myth-Busting Format Works
The 23-Thing structure is central to the book’s appeal. Chang does not begin with a large theoretical system and ask readers to learn its vocabulary. He begins with propositions they are likely to have heard: markets should be free, shareholders own companies, education creates prosperity, governments cannot pick winners, welfare states undermine flexibility and finance should become more efficient.
Each chapter then follows a recognisable reversal. “What they tell you” states the conventional position in a form that its supporters could broadly recognise. “What they don’t tell you” introduces Chang’s counterclaim. The rest of the chapter builds the challenge through history, comparisons, jokes, anecdotes and institutional reasoning.
This makes complex economics unusually accessible. Limited liability becomes a story about the invention of the modern corporation. Deindustrialisation becomes a comparison between computers and haircuts. Bounded rationality becomes a discussion of brilliant investors who still managed to misjudge risk.
Chang’s humour also matters. He is willing to use absurd examples, personal stories and playful headings without turning the book into economic trivia. The jokes usually perform explanatory work by making an assumption visible.
The weakness is inseparable from the strength. Myth-busting rewards sharp opposition. Nuance is harder to market than contradiction. As a result, the title of a chapter can suggest a proposition more absolute than the argument that follows.
“The washing machine has changed the world more than the internet” is memorable; “the social impact of older household technologies is systematically underestimated because technological recency biases our evaluation” is more precise but would not sell many copies. “More education in itself is not going to make a country richer” is deliberately destabilising even though Chang repeatedly affirms education’s broader value.
The best way to read the book is therefore not to treat the chapter titles as commandments. They are intellectual provocations designed to reopen questions. The argument lives in the qualifications that follow.
The organisation also allows repetition because several Things attack related assumptions from different directions. Wages, executive pay and equality overlap. Industrial policy, Africa and development overlap. Rationality and finance overlap. Chang generally uses that repetition productively, showing the same institutional logic at multiple scales, although a reader moving straight through all 23 chapters may occasionally feel that the book is proving the same point again: outcomes presented as natural are often structured by institutions.
That repetition becomes an advantage when the whole book is considered. What initially looks like a loose collection of contrarian essays gradually reveals a coherent worldview.
Critical Review: What the Book Achieves and Where It Falls Short
The strongest contribution of 23 Things They Don’t Tell You About Capitalism is its ability to make economic institutions visible. Chang repeatedly identifies rules that disappear from ordinary discussion because people have become accustomed to them. Immigration controls, corporate law, bankruptcy, welfare provision, financial regulation and industrial policy are not peripheral distortions around a natural market. They help determine what the market is.
That insight remains powerful because it changes the burden of argument. Once markets are recognised as constructed, defenders of an existing arrangement cannot justify it merely by calling alternatives “intervention.” They must explain why the current rules produce better outcomes than other possible rules.
Chang is equally strong when challenging the habit of interpreting income as a direct measure of individual contribution. The comparison between workers in rich and poor countries makes it difficult to sustain a purely personal theory of productivity. People operate inside economic systems whose capital, technology and institutions amplify or suppress what they can accomplish.
His development arguments are another major strength. By bringing economic history into popular debate, Chang shows that the development paths of rich countries were far more interventionist than simplified free-market narratives suggest. This does not settle modern industrial-policy debates, but it makes historical amnesia harder.
Several of the book’s arguments have also aged impressively. Later evidence has weakened transformative claims about microcredit, strengthened scepticism toward simple trickle-down economics and pushed education research toward distinctions between schooling and actual learning. The return of industrial policy has moved questions once treated as heterodox closer to the centre of economic policy.
The book is also genuinely pluralist rather than simply anti-market. Chang repeatedly acknowledges the power of profit, entrepreneurship, competition and decentralised exchange. His desired endpoint is regulated capitalism, not command socialism. That makes the critique more serious than a catalogue of complaints about markets because it forces him to think about how capitalism might work differently.
The most important weakness is causal overreach. Chang is excellent at producing counterexamples to universal free-market propositions. He is less consistent at demonstrating that his preferred institutional explanation accounts for the full difference in outcomes.
Africa illustrates the issue. It is reasonable to reject geographic or cultural destiny, and the timing of African growth changes gives Chang grounds to question static explanations. But development outcomes arise from interacting institutions, commodity structures, conflict histories, state capacity, infrastructure, global conditions and policies. The failure of neoliberal reforms in particular settings does not mean reversing those reforms is sufficient.
Industrial policy presents the same challenge. POSCO and South Korea prove that governments can help create globally competitive industries. They do not provide a simple method for distinguishing future POSCOs from future white elephants. The hard problem is governance: how to support learning without protecting failure, how to obtain reliable information, how to resist capture and how to stop policies when they do not work.
Chang recognises government failure, but the book does not explore it with the same sustained curiosity that it applies to market failure. Readers could therefore leave with an asymmetrical impression even though the explicit theory is more balanced.
The treatment of technology has aged more visibly. Chang was right to remind readers that mundane household technologies transformed society profoundly and that novelty should not be confused with importance. Yet digital technology continued evolving after publication. Smartphones, platforms, cloud computing and generative AI widened the range of economic activities affected by digital systems. A reader in 2026 should retain Chang’s method of historical comparison without treating his 2010 ranking as a settled result.
Inflation is another area where the rhetoric needs updating. Chang’s attack on low-inflation monoculture remains persuasive, especially after the supposedly stable pre-2008 period culminated in financial collapse. Yet the post-pandemic inflation episode showed that even far-from-hyperinflationary price increases can severely damage living standards and create difficult policy trade-offs. Stability needs a broader definition, but that definition cannot marginalise inflation itself.
Thing 17 similarly benefits from careful reinterpretation. Chang is convincing that expanding education does not automatically create productive industries. He is less convincing if read as minimising the broader contribution of human capital to technological absorption, institutional quality and worker adaptability. Modern evidence supports a distinction between schooling quantity and learning quality rather than an outright demotion of education.
His critique of finance also needs calibration. Liquidity can generate short-termism, but it also allows diversification, price discovery and the withdrawal of capital from genuinely bad investments. Patient capital is valuable only if patience does not become protection from accountability. The desirable objective is not simply less-efficient finance but finance whose efficiency is judged partly by the quality of real investment it enables.
The book’s rhetorical style occasionally compounds these substantive problems. “What they don’t tell you” suggests that important truths have been deliberately concealed, when many of these questions have long been debated within economics. Economists have argued over industrial policy, bounded rationality, inequality, institutions and market failure for decades. Chang’s complaint is better understood as a challenge to which ideas dominated public policy, not a claim that the profession literally ignored every alternative.
Thing 23 is therefore both important and somewhat unfair. Mainstream economic institutions failed badly before the financial crisis, and excessive confidence in particular models deserves criticism. Yet “economists” are not a single school. Behavioural economics, institutional economics, development economics, economic history and macroeconomic traditions have generated substantial internal disagreement.
Chang is strongest when asking readers to resist intellectual monopoly, not when using the failures of one dominant approach to indict economic expertise generally. Modern economies are complicated enough that serious expertise remains indispensable. The democratic task is to expose expert assumptions to challenge rather than imagine that expertise can be dispensed with.
The book’s accessibility is an overwhelming strength. A reader can understand shareholder value, industrial policy, deindustrialisation, bounded rationality and financial liquidity without prior economics training. Chang is particularly good at connecting abstractions to ordinary experience.
That clarity sometimes comes at the cost of technical depth. Readers looking for econometric identification, formal models or exhaustive engagement with competing literature will not find them here. That is not necessarily a flaw given the book’s purpose, but it matters when evaluating how conclusively any one chapter proves its case.
Its greatest achievement is therefore educational in the broadest sense. Chang teaches a habit of questioning. When someone says that wages reflect productivity, he asks what institutions determine the wage. When someone says industrial decline is inevitable, he asks what exactly the statistics measure. When someone says governments cannot choose industries, he asks whether history supplies counterexamples. When someone says markets should be free, he asks free from which rules.
That intellectual habit survives even when individual claims are revised. A reader can conclude that Chang understates inflation risks, overstates the case against educational expansion or places too much confidence in industrial policy while still accepting that economic systems should not be discussed as though their rules descended from nature.
The book will be most useful to readers whose understanding of capitalism has been shaped primarily by simple oppositions: market versus government, efficiency versus regulation, growth versus redistribution, security versus flexibility, entrepreneurship versus bureaucracy. Chang shows that each opposition is too crude.
Readers already immersed in political economy may find some claims familiar and some examples too selective. Readers seeking detailed policy prescriptions will also need more specialised work. The book does not provide a blueprint specifying optimal tariffs, ideal tax rates, the correct size of government or a universal system for identifying strategic industries.
What it does provide is a framework for understanding why such questions cannot be answered by invoking “the market” as an independent authority. Economic institutions involve trade-offs, historical conditions and political values. That is the book’s most durable contribution.
Sixteen years after publication, 23 Things They Don’t Tell You About Capitalism is no longer best read as a dispatch from the immediate aftermath of the 2008 crash. The world that produced it has changed: inflation returned, industrial policy returned, geopolitical competition changed attitudes toward supply chains, digital technology became far more economically pervasive, and finance evolved rather than simply retreating.
Yet those changes have made the book’s central question more relevant rather than less. What kind of capitalism are societies choosing to build? Once the fiction of a politically neutral free market is removed, disagreements about regulation, welfare, industrial policy, corporate governance and finance can be argued on their actual merits.
Chang does not win all 23 arguments equally. Some chapters are stronger as challenges than as complete explanations, some generalisations need qualification, and several empirical comparisons belong firmly to 2010. His strongest propositions survive because they are institutional rather than statistical: markets have rules, productive capacity is collective, government and market failure must be compared symmetrically, financial sophistication does not abolish uncertainty, and development requires building capabilities rather than merely liberalising existing exchanges.
That makes the book worth reading even for someone who expects to disagree with Chang. Its value does not depend on replacing one economic orthodoxy with another. It lies in making apparently natural arrangements look contestable again.
The best final judgment is therefore neither that Chang has revealed 23 hidden truths nor that his provocations are merely ideological. He has produced an unusually effective guide to the assumptions behind free-market capitalism and a forceful argument that capitalism can take forms very different from the model that dominated policy before 2008. Readers who want a technical treatment of each empirical dispute will need additional economics. Readers who want to understand why markets, states, firms and social institutions cannot be separated as neatly as political slogans imply will still find 23 Things They Don’t Tell You About Capitalism an exceptionally useful place to begin.
Last Updated on September 15, 2026 by Aseem Gupta