
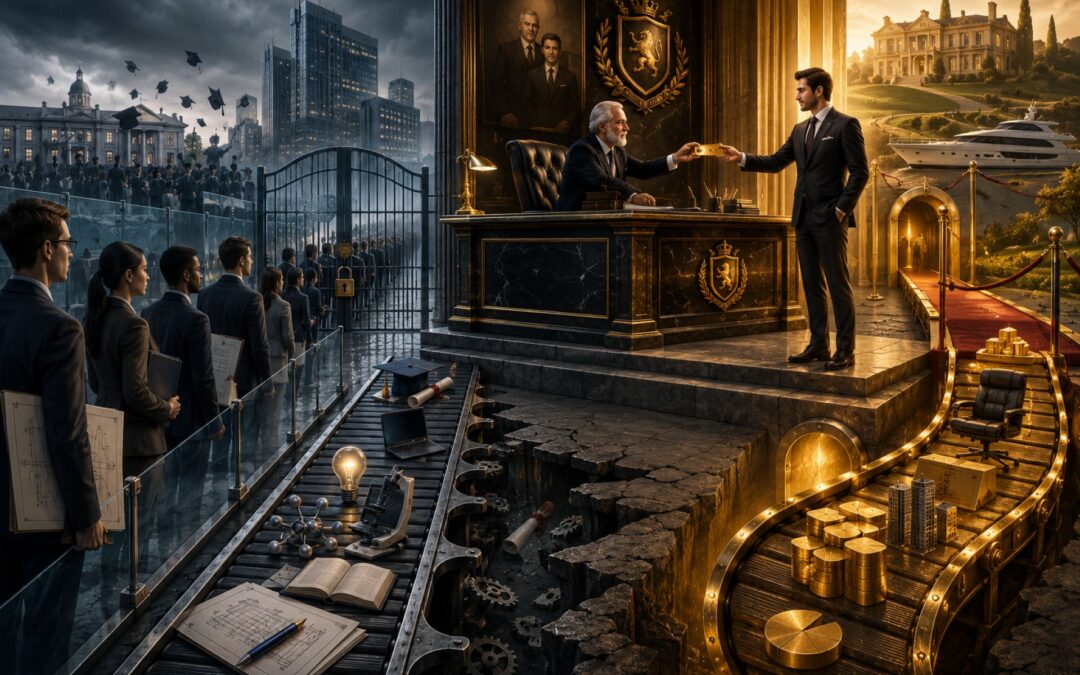
In November 2016, JPMorgan Chase agreed to pay more than $264 million to settle allegations involving a hiring programme that had operated across its Asia-Pacific business between 2006 and 2013. The bank had been offering jobs and internships to relatives and associates of powerful clients and government officials, sometimes bypassing its normal recruitment procedures to accommodate candidates who would otherwise have struggled to qualify.
What made the arrangement particularly revealing was how openly the bank measured its commercial benefits. Employees maintained spreadsheets labelled “Referral Hires vs Revenue,” tracking business associated with politically connected recruits. According to the US Securities and Exchange Commission, JPMorgan hired approximately 100 people referred by foreign government officials, helping the bank secure or retain business that generated more than $100 million in revenue.
Employment had become a form of payment. A job that should have been awarded through a legitimate recruitment process was instead being used to purchase influence.
The scandal was an extreme and unlawful example of something that occurs far more quietly throughout the economy. Most nepotism does not involve secret spreadsheets or government contracts. It appears in preferential hiring, prestigious internships, university admissions, protected promotions and leadership positions passed from parents to children.
For the beneficiary, a family connection can be extraordinarily valuable. It reduces competition, creates access to opportunities and provides advantages that others must struggle to earn. But when these decisions accumulate across thousands of institutions, they raise a much larger economic question: what happens when an economy distributes opportunities according to family relationships rather than ability?
The cost extends beyond unfairness. Nepotism can discourage investment in skills, weaken organisational performance, restrict social mobility and prevent talented people from reaching positions where they could create the greatest value.
When Family Loyalty Becomes Nepotism
Nepotism is favouritism based on family relationships, particularly when relatives receive employment, promotions, authority or other opportunities because of their connection to someone influential. Although the word is often used loosely, it is important to distinguish nepotism from other forms of advantage.
Cronyism generally involves favouring friends, political allies or influential associates. Patronage involves distributing opportunities in exchange for loyalty or support. Legacy admissions favour applicants whose relatives attended an institution, while inheritance transfers private wealth or ownership between generations. These practices can reinforce one another, but they are not interchangeable.
Nor is every family-assisted opportunity necessarily nepotistic. An employee recommending a capable relative for a vacancy may provide useful information to an employer. A business founder might have a child who understands the organisation exceptionally well and is genuinely qualified to lead it.
The distinction lies in how decisions are made. A family connection becomes problematic when it substitutes for independent evaluation, removes meaningful competition or shields someone from standards applied to everyone else.
There are understandable reasons why people favour relatives. Hiring strangers involves uncertainty because qualifications can be exaggerated, interviews reveal relatively little and professional references are imperfect. Someone who knows a relative personally may feel better equipped to judge their reliability, character and willingness to remain loyal.
Trust can also carry economic value. Business owners may believe that relatives are less likely to steal, disclose confidential information or abandon an organisation during difficult periods. Political leaders sometimes appoint family members because they expect greater personal loyalty, while founders may prefer children who understand the business’s history and feel responsible for protecting it.
The most powerful motivation is also one of the most ordinary human instincts: parents want their children to succeed. They pay for education, provide financial support, offer career advice and introduce their children to people who might help them.
None of these actions is inherently objectionable. The difficulty arises when legitimate family loyalty conflicts with responsibility towards an institution.
A parent helping a child prepare for an interview is different from ensuring that the child receives the job regardless of qualifications. A founder teaching an heir how to manage a company is different from excluding stronger candidates from consideration. The first involves family support; the second can transfer the costs of private favouritism to employees, investors, customers and other applicants.
Nepotism survives partly because the incentives are uneven. The benefits to the family are concentrated and immediate, while the costs are dispersed among people who may never know they were disadvantaged. A decision that appears entirely rational from one household’s perspective can therefore contribute to an inefficient system when repeated throughout the economy.
How Nepotism Survived the Rise of Meritocracy
Family-based privilege existed long before modern corporations. Ancient dynasties passed political authority through bloodlines, aristocratic families controlled land and legal rights, and many occupations were organised around inherited status. In societies where birth determined social position, the idea that every important appointment should be decided through open competition was far from universal.
The word nepotism derives from the Latin nepos, meaning nephew or descendant, and became particularly associated with the Catholic Church. Renaissance popes frequently elevated relatives into influential religious and administrative positions. Pope Alexander VI, for example, appointed his teenage son Cesare Borgia as a cardinal, illustrating how ecclesiastical authority could become entangled with family advancement.
Over time, hereditary appointments encountered growing resistance, partly because increasingly complex institutions needed specialised knowledge. Expanding states required skilled administrators, universities needed productive scholars, and businesses operating in competitive markets had stronger reasons to appoint capable managers.
Historical research provides an interesting illustration. In a study of academic families between 1088 and 1800, David de la Croix and Marc Goñi estimated that nepotistic selection among scholars’ sons declined substantially during the Scientific Revolution and Enlightenment. Their model estimated that nearly 49% of scholars’ sons entering academia before 1543 would not have qualified under the selection standards faced by comparable outsiders, falling to approximately 8% during the Enlightenment.
These figures are estimates of preferential selection within a specific historical population, not the percentage of all academic appointments made through family connections. Nevertheless, the pattern supports an important interpretation: when scientific advancement made weak appointments more costly, institutions faced stronger incentives to reward competence.
Nepotism did not disappear as hereditary systems weakened. Instead, family advantage increasingly operated through institutions that formally claimed to value individual achievement.
A hereditary appointment might become a prestigious internship. An aristocratic connection might become access to an influential professional network. A family fortune might finance the education and experiences needed to compete for positions that appeared open to everyone.
Modern meritocratic institutions changed the rules of competition, but they did not eliminate the advantages families could bring into that competition.
The First Gate: Family Connections in Hiring
Most professional careers begin with a series of decisions that happen before anyone has demonstrated their full abilities. Someone must discover a vacancy, attract attention, secure an interview and persuade an employer to take a chance on them.
Family connections can influence every stage. A parent may know that a company is recruiting before the vacancy becomes public, understand what its managers value or have a relationship with someone willing to recommend an applicant.
Research suggests that these connections are far more common than the occasional spectacular example of an executive hiring a relative.
Economist Matthew Staiger’s research on the intergenerational transmission of employers found that 29% of individuals had worked for a parent’s employer at least once by age 30. Using variation in job availability at parents’ workplaces, the study estimated that working for a parent’s employer increased initial earnings by approximately 19%, largely because it gave young workers access to higher-paying firms.
The finding does not establish that nearly one-third of young workers obtained jobs through improper favouritism. Children may develop interests and skills similar to their parents, while employers can legitimately value referrals from employees whose judgement they trust.
Nevertheless, the study demonstrates that labour-market access is partly transmitted through families. Its analysis also found that children of higher-earning parents were more likely to benefit from these employer connections and experienced larger earnings gains.
Consider two graduates with similar qualifications. One submits applications without knowing anyone inside the organisations being approached. The other receives advice from a parent who understands the recruitment process, knows which departments are expanding and can introduce the graduate to an experienced manager.
Both may eventually need to perform well, but they are not competing under identical conditions. The second applicant begins with better information, stronger credibility and potentially access to employers the first applicant might never encounter.
The advantage continues after recruitment. Connected employees may understand an organisation’s informal rules, receive advice about valuable assignments and learn which managers influence promotions. These forms of knowledge can accelerate career development without any single decision appearing obviously improper.
Nepotism is often imagined as one undeserved appointment. In practice, inherited advantage may consist of numerous small opportunities that make the next opportunity easier to obtain.
The Second Gate: Legacy Admissions and Elite Networks
The distribution of professional opportunities begins long before people enter the workforce. Elite universities play an important role because admission offers more than an education: it provides credentials, social relationships, internships, alumni networks and access to employers that recruit from a relatively narrow group of institutions.
This makes legacy admissions particularly consequential. Giving an applicant preference because a parent attended the university can influence opportunities that extend far beyond the original admissions decision.
Research by Raj Chetty, David Deming and John Friedman on admissions to highly selective private colleges found that children from families in the top 1% of the income distribution were twice as likely to attend an Ivy-Plus institution as middle-class applicants with comparable standardised test scores.
The researchers identified several important contributors to this advantage, including legacy preferences, recruitment of athletes and greater weight placed on non-academic ratings. Those ratings also tended to favour students from affluent private-school environments.
The study does not suggest that wealthy applicants are uniformly less capable or that academic performance is irrelevant. Many privileged students possess exceptional qualifications and would remain competitive without preferential policies. The question is whether family background should provide an additional advantage after relevant qualifications have been considered.
Supporters of legacy admissions argue that these preferences encourage alumni loyalty, strengthen institutional communities and support fundraising. Universities must consider financial sustainability, but the benefits to their existing networks need to be weighed against the opportunities denied to other qualified applicants.
The consequences of admission can be substantial. The same research found that attending an Ivy-Plus institution rather than an average highly selective public flagship university increased the probability of reaching the top 1% of earnings by 60%, nearly doubled the likelihood of attending an elite graduate school and tripled the probability of working at a prestigious firm.
These effects concern specific high-end career outcomes, not a comparable increase in average earnings for every student.
An initial family preference can therefore become increasingly difficult to recognise. A student receives an elite university place, develops valuable professional connections, secures a prestigious internship and eventually enters the workforce with an impressive résumé.
By that stage, the resulting achievements may be genuine. Yet some of the opportunities that made them possible originated in an advantage that other applicants could not earn.
How Advantage Compounds Over Generations
A family’s influence on economic outcomes extends beyond direct nepotism. Parents transmit financial resources, educational opportunities, information, expectations and social relationships that shape their children’s prospects throughout life.
Wealthier households can afford desirable neighbourhoods, high-quality schooling, extracurricular activities and additional academic support. They may also possess professional knowledge that helps children understand which qualifications matter and how competitive industries operate.
These advantages are particularly valuable when young adults face uncertainty. Someone with financially secure parents may accept an unpaid internship, move to an expensive city, experiment with entrepreneurship or remain unemployed while searching for a promising position.
A person without comparable support may need to accept immediate work regardless of long-term prospects. The difference does not necessarily reflect ambition or intelligence; it reflects the financial consequences each person faces if an opportunity fails.
Wealthy parents can, in effect, provide insurance against failure. A failed business might be a temporary setback for someone with substantial family resources, while the same failure could leave another person burdened by debt and unable to try again.
Economists study these patterns through intergenerational mobility, examining how strongly income, education, occupations and wealth are associated across generations. One common measure, intergenerational income elasticity, estimates how much of a parent’s relative income advantage tends to persist in their children’s income.
A higher elasticity generally indicates greater persistence of economic position, although estimates vary across countries, generations and measurement methods. The relationship is not evidence that every child from a wealthy family remains wealthy or that individuals cannot substantially improve their circumstances.
The World Bank’s Global Database on Intergenerational Mobility, which includes income-mobility estimates for 87 economies, indicates that greater inequality is generally associated with lower mobility. OECD research similarly describes sticky floors, which make it difficult for disadvantaged people to rise, and sticky ceilings, which help privileged families retain their position.
Nepotism can reinforce both patterns. It makes some opportunities more accessible to people who already possess connections while reducing the rewards available to outsiders investing in education, experience and professional development.
There is also a less visible effect on incentives. If capable people repeatedly observe that promotions and influential appointments depend more on family relationships than performance, their expectations about the value of effort may change.
Some may invest less in training because they believe advancement is restricted. Others may leave for organisations or countries where opportunities appear more accessible.
Cross-country research has found a negative association between perceived nepotism and measures of human capital. Such findings do not establish that nepotism independently causes every difference in education or skills, since institutional quality, corruption and economic development can influence these outcomes simultaneously.
The underlying incentive problem nevertheless matters. A competitive economy depends not only on employing skilled people but also on persuading individuals that acquiring skills is worthwhile. When important opportunities appear predetermined by birth, that expectation becomes harder to sustain.
The Productivity Cost Inside Firms
The consequences of nepotism become more direct when family relationships determine who manages employees, allocates resources and makes business decisions.
Imagine a company in which the founder’s child is expected to become chief executive regardless of performance. Ambitious employees quickly recognise that the most influential position is unavailable to them, while senior managers may hesitate to challenge someone whose authority comes from the controlling family.
This changes behaviour throughout the organisation. Employees who believe promotions are predetermined may reduce their effort, while capable professionals may leave for employers offering a more credible route to advancement.
The immediate problem is unfair allocation of positions. The deeper problem is that nepotism can weaken the incentives and accountability systems on which productive organisations depend.
A poorly performing executive protected by family relationships may be difficult to remove. Managers might conceal problems rather than risk confrontation with the owner’s relatives, and employees may hesitate to recommend changes that conflict with family preferences.
The organisation can consequently retain inefficient practices long after their weaknesses become apparent.
Modern management systems are intended to reduce these problems through measurable targets, performance monitoring, consistent incentives and clear responsibilities. But formal procedures cannot deliver their intended benefits when influential people are exempt from them.
A 2026 study by Yuchen Feng, Andrew Henley and Anna Kochanova examined how family ownership affects the relationship between structured management practices and productivity in British firms.
The researchers found that structured management practices were generally associated with higher labour productivity, but family ownership significantly weakened their long-run productivity benefits. This effect was particularly pronounced for incentive systems and target-setting practices, especially among smaller and medium-sized businesses and service-sector firms.
The findings are based on observational firm data and should not be interpreted as proof that all family-owned businesses are inefficient. They highlight a more specific problem: management rules are less effective when informal authority compromises their consistent application.
A company may introduce performance reviews, but those reviews lose credibility if the owner’s relatives are evaluated differently. It may establish ambitious targets, but managers have little reason to take them seriously if privileged executives face no consequences for missing them.
These failures affect more than internal fairness. Weak management can produce poor investment decisions, inefficient supply chains, delayed innovation and an inability to expand into profitable markets.
At the level of an entire economy, the consequences may be amplified when influential positions are repeatedly allocated according to relationships rather than capability. Researchers have associated entrenched nepotism with smaller firms and weaker economic performance, although national comparisons cannot neatly separate nepotism from corruption, institutional quality and access to capital.
The central issue is the allocation of scarce talent. An economy becomes more productive when capable people can move towards positions where their skills create the greatest value.
Nepotism interferes with that process by protecting some appointments from competition and preventing other candidates from demonstrating what they could achieve.
Why Family-Business Succession Is a Different Risk
The stakes become particularly high when family connections determine not merely who receives employment but who controls an entire organisation.
Business founders often possess capabilities that are difficult to transfer. They may have developed unusual market knowledge, supplier relationships, technological expertise and managerial judgement through years of experience. Their leadership authority also reflects decisions made while creating and expanding the company.
Children can inherit ownership, but they do not automatically inherit those abilities.
This creates a fundamental difference between passing down an asset and passing down responsibility for managing it. A founder may legitimately leave company shares to an heir without that heir necessarily being the best person to run the organisation.
The economic risk arises when ownership and executive authority are treated as inseparable.
Research has repeatedly examined whether companies perform differently when leadership passes to relatives rather than unrelated professionals. One influential study published in the American Economic Review found that companies appointing chief executives related to founders, departing executives or major shareholders subsequently performed worse on measures including operating profitability and market valuation than companies appointing unrelated executives.
Such comparisons are informative, but they also raise a difficult question. Are family successors responsible for weaker performance, or do families choose internal successors in companies already facing particular challenges?
A study of Danish businesses provides stronger evidence by examining circumstances that influence succession decisions independently of managerial ability.
In Inside the Family Firm: The Role of Families in Succession Decisions and Performance, published in the Quarterly Journal of Economics, Morten Bennedsen and his co-authors studied chief-executive transitions in Denmark.
The researchers used the gender of a departing chief executive’s first child as a source of variation in whether leadership remained within the family. Because families with firstborn sons were more likely to appoint family successors, this created an opportunity to estimate the consequences of family succession while reducing some of the selection problems affecting ordinary comparisons.
They found that family CEO succession caused operating profitability on assets to fall by at least four percentage points around the leadership transition.
The estimated underperformance was especially pronounced in larger firms, rapidly growing industries and businesses employing highly skilled workers. These findings suggest that restricting the search for leadership talent can be particularly costly when managerial demands are complex.
Yet these results should not be interpreted as proof that every family successor is incapable or that professional managers are invariably superior.
Some heirs spend decades learning the business, develop deep industry expertise and demonstrate exceptional ability. Family ownership can also support valuable organisational strengths that are difficult to reproduce in businesses dominated by investors focused on short-term returns.
Families with a substantial financial and emotional stake in an organisation may be willing to invest through temporary downturns, preserve relationships with employees and suppliers, and pursue strategies whose benefits take many years to emerge.
The evidence from Asia illustrates both sides of this relationship.
A UBS analysis of large Asian family businesses found that family-owned companies had delivered stronger long-term share-price performance and returns on invested capital than comparable non-family businesses over the period examined.
However, the research also identified uncertainty surrounding leadership transitions. UBS estimated that approximately 48% of the family businesses in its coverage would undergo intergenerational transfers within five years, affecting companies representing more than $1 trillion in free-float market capitalisation.
Its detailed examination of 170 major Asian family groups found that transitions to family leaders were associated with greater short-term share-price underperformance than transitions to non-family executives. Importantly, performance often recovered after approximately three years, while returns on invested capital remained relatively stable around succession events.
This distinction matters. A temporary decline in share prices can reflect investor uncertainty rather than a permanent collapse in operational performance. Family control may therefore produce both genuine advantages and identifiable risks, depending on the organisation and the quality of its governance.
South Korea offers a particularly revealing institutional example. Its family-controlled conglomerates, known as chaebols, helped transform the country into an industrial powerhouse while concentrating considerable corporate authority within founding families.
As the history of South Korea’s chaebol system demonstrates, hereditary control can coexist with internationally competitive businesses, sophisticated technology and remarkable commercial achievements. The difficulty arises when controlling families possess influence disproportionate to their direct ownership and corporate decisions become difficult for independent shareholders or directors to challenge.
The relevant dividing line is therefore not simply family ownership versus outside ownership. It is whether family influence is constrained by credible governance.
A well-managed family company can separate ownership rights from automatic entitlement to executive positions. Relatives may compete for leadership, but they should face meaningful performance standards and credible comparisons with outside candidates.
Independent directors must possess genuine authority, succession plans should be established before a crisis emerges, and companies need mechanisms for replacing leaders who underperform.
Professional management is not automatically excellent, just as inherited leadership is not automatically poor. But opening the selection process to capable candidates increases the likelihood that important responsibilities will be assigned to people who can perform them.
The strongest family businesses do not have to abandon family continuity. They must ensure that continuity does not become immunity from competition or accountability.
Inheritance Turns Connections Into Durable Wealth
Family connections shape access to education, employment and leadership. Inheritance introduces another mechanism through which economic advantages persist across generations: the direct transfer of accumulated assets.
Unlike nepotism, inheritance does not necessarily involve improper influence over an institution. Parents generally have the legal right to transfer property to their children, and family ownership can provide continuity and stability.
Nevertheless, inherited wealth can magnify advantages that already exist.
According to Cerulli Associates’ projections of US wealth transfers, approximately $124 trillion is expected to change hands through 2048. Around $105 trillion is projected to flow to heirs, while approximately $18 trillion will be transferred to charitable organisations.
More than half of the projected total transfer volume is expected to originate from high-net-worth and ultra-high-net-worth households, which together represent only about 2% of American households.
These are forecasts rather than wealth transfers that have already occurred, and their eventual size will depend on asset values, economic conditions and household decisions. Nevertheless, the projections illustrate how much accumulated wealth is concentrated among a relatively small proportion of families.
An inheritance can change economic prospects in ways that extend well beyond the amount received.
Someone who inherits a home may avoid decades of rent or mortgage payments. Another person may receive capital to start a business, finance education or purchase investments that generate future income.
Inherited wealth also provides something that ordinary income often cannot: patience.
An individual with substantial assets can wait for a business to become profitable, hold investments during a market downturn or reject unsuitable employment. Someone dependent on monthly wages may lack the financial security necessary to make those choices.
Research from the United Kingdom helps clarify how unevenly these benefits can be distributed.
The Institute for Fiscal Studies’ research on inheritance and lifetime inequality projected that, among people born during the 1980s, inheritances would increase lifetime income by approximately 29% for those whose parents were in the wealthiest fifth of the parental wealth distribution.
For those whose parents were in the poorest fifth, the projected increase was approximately 5%.
These figures describe differences by parental wealth, not simply by the recipients’ own earnings. The researchers also found that inheritances can represent meaningful proportions of lifetime income for households across the income distribution, so inheritance is not exclusively relevant to wealthy recipients.
The stronger conclusion is that unequal parental wealth can translate into increasingly unequal lifetime resources for the next generation.
This process becomes self-reinforcing when inherited assets combine with educational and professional advantages. Well-connected families may enjoy higher earning opportunities, accumulate investments and eventually pass both wealth and valuable social relationships to their descendants.
Tax policy influences how easily these advantages persist. Estate taxes, inheritance taxes, trusts and rules governing the treatment of appreciated assets can affect the concentration of wealth across generations.
The question of how inheritance taxes and dynasty trusts should be designed involves competing concerns about fairness, private property, avoidance and the incentives to build businesses.
For the economic analysis of nepotism, the essential point is that inherited wealth can amplify unequal access to opportunity. A family name may open professional doors, while family assets can provide the financial security necessary to benefit from whatever lies beyond them.
The Opportunity Cost Nobody Can Count
The economic consequences of nepotism are difficult to measure because some of the most important losses never appear in company accounts or national statistics.
Researchers can compare hiring outcomes, wages, executive succession, corporate profitability and intergenerational mobility. These measurements reveal specific ways in which connections influence economic performance.
What they cannot fully observe is the economy that might have existed if opportunities had been allocated differently.
Consider a company that appoints an underqualified relative to a senior management position. The business may remain profitable, continue employing workers and survive for decades without experiencing a dramatic failure.
Yet a more capable manager might have expanded operations, developed new products, reduced costs or entered international markets. None of those possibilities appears as a recorded financial loss because the alternative management decisions were never made.
The same problem applies to employment. An unsuccessful applicant might have been exceptionally productive, but there is no database recording the innovations that person could have created if given the opportunity.
Education produces similar uncertainties. A student admitted through family preference may perform adequately and build a successful career, but that outcome does not reveal what another applicant might have achieved with the same resources and institutional connections.
Economists describe the value of the best forgone alternative as an opportunity cost. In nepotistic decisions, those costs may involve careers, innovations, business formation and productivity improvements that never materialise.
This does not mean every connected appointment necessarily destroys value. Some relatives are excellent employees or leaders, and predicting what another candidate would have achieved is inherently uncertain.
Nor can the entire economic cost of nepotism be reduced to one reliable national figure. Different studies measure specific effects under particular institutional conditions, while the complete counterfactual economy remains impossible to observe.
That uncertainty should encourage careful analysis rather than exaggerated estimates. It does not make the underlying problem unimportant.
A company can waste talent without collapsing, and an institution can restrict opportunity without producing an obvious scandal. Economic damage may accumulate through thousands of decisions that appear individually unremarkable.
Can a Meritocracy Limit Nepotism?
Nepotism cannot be eliminated simply by asking people to stop favouring their families. Family loyalty is too deeply embedded in human behaviour, and personal relationships often provide legitimate information and support.
The practical challenge is to create institutions in which relationships cannot override accountability.
Public-sector restrictions offer one approach. In the United States, 5 U.S.C. §3110 restricts federal public officials from appointing, employing, promoting or advocating for relatives in agencies over which they exercise relevant authority or control.
The law recognises that public employment should not become an extension of family power. However, it is not a general prohibition against relatives working together, nor does it apply universally to private businesses.
Private organisations generally require governance systems that make recruitment and promotion more transparent.
One starting point is disclosure. Employees and executives should be required to identify relevant family relationships before participating in hiring, promotion or contract decisions, allowing organisations to manage conflicts of interest.
Structured recruitment can also reduce opportunities for favouritism. Candidates can be assessed against documented criteria, interviews can use consistent questions, and panels can include individuals independent of the person making the referral.
Blind screening may help during early recruitment by concealing names or other identifying information. But its effects are limited when relationships become visible during interviews or when influential people can intervene later in assignments, promotions and executive appointments.
Senior leadership requires stronger safeguards because the potential consequences of a poor decision are much larger. Boards should compare family successors with credible outside alternatives and establish performance expectations before appointments are made.
Ownership should not automatically confer executive authority, and independent directors need the power to challenge or replace leaders who fail to meet organisational requirements.
Transparency is valuable because it changes the incentives facing decision-makers. A manager may think differently about appointing a relative when the decision must be justified to employees, investors or the public.
These safeguards cannot guarantee a perfectly meritocratic system. Ability is difficult to measure, hiring decisions always involve judgement, and personal networks sometimes help employers identify excellent candidates whom formal recruitment would overlook.
There is also a risk that rules designed to prevent nepotism become purely symbolic. An organisation may adopt independent hiring procedures while allowing its most powerful members to influence decisions informally.
Effective reform therefore requires more than written policies. It depends on whether those policies are consistently enforced, including when doing so is inconvenient for influential families.
A functioning meritocracy does not have to exclude relatives from opportunities. It must ensure that being related to someone powerful does not exempt a candidate from demonstrating the competence expected of everyone else.
Families will always transfer advantages to their children. They will provide education, financial assistance, useful advice and introductions to people who might offer opportunities. These actions are ordinary features of family life, and eliminating them would be neither realistic nor desirable.
The economic danger begins when private family loyalty determines who receives opportunities and authority that should be allocated through accountable institutional decisions.
Nepotism is attractive because the beneficiary receives a concentrated advantage while the costs are dispersed. A connected applicant obtains a job, but the stronger candidate who never receives an interview remains invisible. An heir obtains control over a company, while employees, investors and customers may gradually bear the consequences of weaker leadership.
The system does not necessarily collapse under these decisions. It may simply become less competitive, less innovative and less productive than it could have been.
A healthy economy does not require people to abandon their families. It requires institutions strong enough to distinguish legitimate family support from inherited entitlement, ensuring that important responsibilities remain open to capable people regardless of their background.
A family name may open a conversation, but it should never settle the decision.
Last Updated on October 20, 2026 by Aseem Gupta