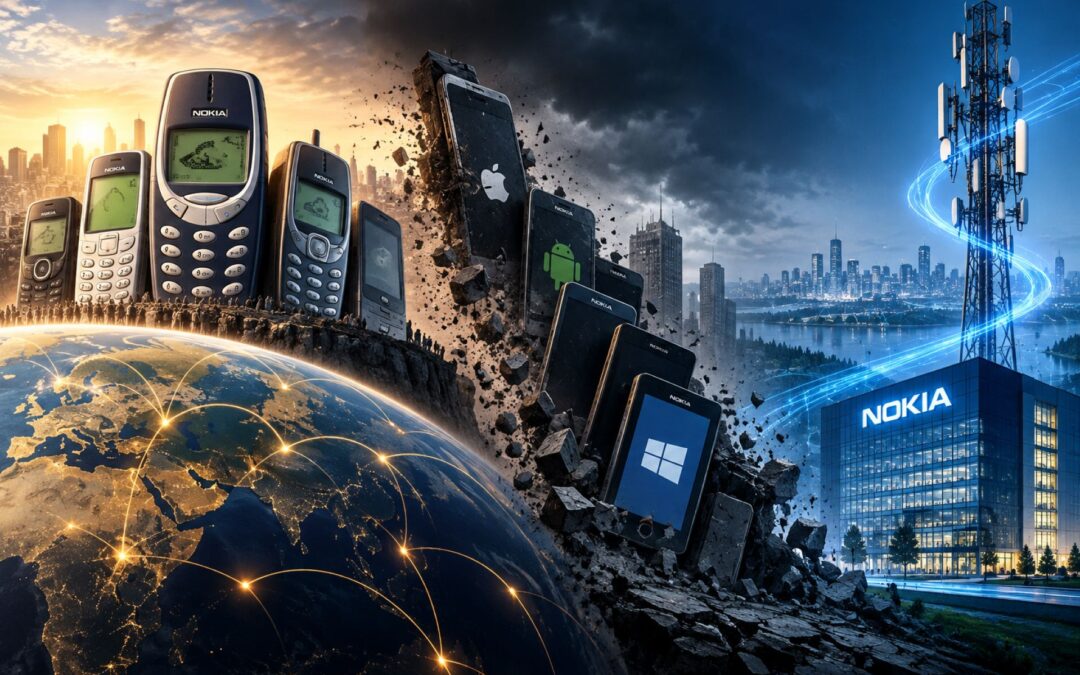
For much of the early twenty-first century, Nokia seemed almost inseparable from the mobile phone itself. Its handsets were everywhere, from European business districts to small towns in developing countries. They were affordable, durable, easy to operate, and available in a remarkable variety of designs. At its peak, the Finnish company sold hundreds of millions of phones annually and controlled more than a third of the global handset market. Yet within a few years, its dominance had collapsed, and in 2014, Nokia completed the sale of its mobile-phone business to Microsoft.
The story is often reduced to a simple explanation: Apple introduced the iPhone, Nokia failed to innovate, and an industry leader disappeared. That account overlooks how technologically capable Nokia already was, how extensively it attempted to respond, and why its efforts repeatedly fell short. It also overlooks something more fundamental: Nokia Corporation never disappeared. The company that lost the smartphone war had spent nearly 150 years moving between industries, and its survival would depend on another transformation. Understanding Nokia’s rise and fall means examining both the strengths that made it dominant and the organisational and technological changes that eventually undermined those strengths.
From Paper Mills to a Finnish Industrial Powerhouse
Nokia’s origins lie in nineteenth-century Finland, where its founder was concerned with producing paper rather than transmitting information. In 1865, mining engineer Fredrik Idestam established a wood-pulp mill beside the Tammerkoski Rapids in Tampere. The location provided the water power needed to process timber into pulp, an increasingly valuable raw material as industrialisation expanded the demand for paper. Three years later, Idestam opened another mill near the Nokianvirta River, close to the town of Nokia. The second location eventually supplied the name that would become familiar to billions of consumers.
In 1871, Idestam and Leo Mechelin established Nokia Ab as a joint-stock company. Its original business remained firmly rooted in forestry and paper manufacturing, although Mechelin subsequently advocated broader industrial development, including electricity generation. The company was part of an expanding Finnish industrial economy in which natural resources, mechanical production and electrical infrastructure were becoming increasingly important. The historical development of Nokia was therefore considerably more complicated than the straightforward technological origin story associated with many modern electronics companies.
Two other businesses would eventually become central to that history. Finnish Rubber Works was founded in 1898, with Eduard Polón serving as its managing director. It manufactured rubber products such as footwear and later expanded into tyres and other industrial goods. Finnish Cable Works, established in 1912, produced cables for electrical installations, power distribution and telephone networks. Although these operations initially had separate identities, they were building expertise in materials, manufacturing and electrical infrastructure that would become relevant to the future corporation.
The companies gradually came under common ownership. Finnish Rubber Works acquired control of Nokia Ab in 1918, and by 1922, the rubber, paper and cable businesses were connected through a common ownership structure. They nevertheless remained legally distinct for decades, operating across different industrial markets. The association was particularly valuable because the businesses could share resources and benefit from Finland’s expanding electrical and communications infrastructure without immediately surrendering their individual identities.
In 1967, Nokia Ab, Finnish Rubber Works and Finnish Cable Works formally merged to create the modern Nokia Corporation. The new conglomerate manufactured paper, rubber products, cables and a growing range of electronics. Its activities eventually extended into computers, televisions and other consumer and industrial technologies. Telecommunications did not emerge from a predetermined plan established in 1865; it developed through successive investments in industries that appeared promising at different moments. That flexibility was one of Nokia’s defining historical characteristics, although managing such a diverse corporation would also become increasingly difficult.
The cable business provided one particularly important connection to telecommunications. Producing equipment for electrical and telephone networks gave Nokia experience with communications infrastructure before mobile phones became commercially important. Its developing electronics capabilities supplied another foundation. Together, these operations made telecommunications a plausible field for expansion when advances in radio technology began creating opportunities beyond conventional fixed-line networks.
Nokia’s early history reveals an important distinction between changing products and changing the underlying organisation. Moving from paper into rubber, cables and electronics involved new technologies, customers and manufacturing methods, but the company could often add those activities to an expanding industrial group. Its later transition into mobile communications would require a much more concentrated strategy. The eventual shift from conventional mobile phones to software-driven smartphones would prove harder still, because it demanded changes not only to Nokia’s products but also to how the company developed technology and competed for customers.
How Nokia Became the World’s Biggest Mobile-Phone Maker
Nokia’s entry into mobile communications occurred while cellular telephony was still expensive, cumbersome and largely associated with professional users. In 1979, Nokia joined Finnish electronics manufacturer Salora to establish Mobira, a venture focused on mobile radio and telephone equipment. The Nordic countries were developing a shared cellular communications system known as the Nordic Mobile Telephone network, or NMT. Unlike fixed-line telephones, NMT used radio connections between handsets and network base stations, allowing customers to make calls while travelling through areas with coverage.
The Nordic approach created an attractive opportunity for equipment manufacturers. Cooperation around common technical standards allowed compatible devices to operate across participating markets, reducing the limitations imposed by individual national systems. For a company based in a relatively small country, the prospect of serving several markets through shared technology was especially significant. Nokia could develop equipment for an expanding communications network rather than confine itself to Finland’s domestic telephone users.
In 1982, Mobira introduced the Mobira Senator, an early car phone designed for NMT networks. It offered an important improvement over a telephone permanently connected to an office or home, but it was hardly a convenient handheld device. Much of the equipment remained installed inside the vehicle, and its bulk and power requirements limited how it could be used. Nevertheless, the underlying attraction was clear: customers could communicate while moving between locations, making the telephone increasingly independent of a fixed building.
Nokia continued reducing the size of its mobile equipment during the 1980s. The Mobira Cityman, introduced in 1987, represented a major step towards a genuinely portable cellular telephone, although its cost and dimensions remained substantial by later standards. As battery technology, electronic components and radio systems improved, mobile telephony began moving beyond a specialised business service. The opportunity was no longer merely to equip cars with telephones but to place communication directly in the hands of individual users.
The emergence of GSM, the digital mobile communications standard adopted across Europe and eventually many other markets, helped accelerate that transformation. GSM improved the prospects for international compatibility and allowed manufacturers to develop devices for a much larger market. Nokia participated in the development of GSM technology and supplied network equipment as well as handsets. In 1991, Finland hosted the first official GSM call using Nokia equipment, and the Nokia 1011, released in 1992, became an important early mass-produced GSM handset.
That same year, Jorma Ollila became Nokia’s chief executive. He inherited a diversified business whose industrial activities competed for management attention and investment. Rather than continue treating telecommunications as one activity among many, Ollila made it the centre of Nokia’s corporate strategy. The company gradually divested businesses that did not support this direction, concentrating resources on mobile phones and communications networks.
This concentration transformed Nokia’s competitive position. Instead of spreading investment across unrelated product categories, it could build specialised capabilities in handset design, radio engineering, manufacturing and global distribution. Its growing production volumes helped it purchase components, improve factory efficiency and bring new models to market across different price categories. The company was developing advantages that extended far beyond the technical specifications of any individual phone.
By 1998, Nokia had overtaken Motorola to become the world’s largest mobile-phone manufacturer. Its leadership expanded as cellular services spread through both wealthy and emerging markets. Nokia understood that customers did not all need the most technologically advanced handset. Many wanted an affordable phone with reliable reception, a readable screen, familiar menus, a dependable battery and a design that could withstand everyday use.
Those requirements shaped some of Nokia’s most recognisable products. The Nokia 2110, introduced in 1994, helped popularise the melody that became known as the Nokia Tune, adapted from Francisco Tárrega’s guitar composition Gran Vals. The company also turned simple games into memorable handset features. Snake appeared on Nokia phones in 1997, with later versions, including Snake II, becoming closely associated with the brand. These details were modest individually, but they made Nokia products familiar and appealing to customers who might otherwise have regarded a mobile phone as purely functional equipment.
Models such as the Nokia 3310 and Nokia 1100 further strengthened the company’s reputation for accessible, dependable devices. Nokia offered different handsets for customers with different budgets and preferences while maintaining recognisable approaches to usability. Its commercial success illustrates an important aspect of product differentiation in the early mobile-phone market: distinctive design and features could attract attention, but reliability, familiarity and distribution helped turn that attention into repeated purchases.
Nokia’s greatest achievement was not inventing a single revolutionary handset. It was making mobile communication practical and accessible at an enormous scale. By 2008, according to Gartner’s worldwide mobile-phone market figures, Nokia sold approximately 472.3 million handsets and held around 38.6% of the global market. Those figures measure mobile phones overall, including conventional feature phones, rather than smartphones alone.
The distinction is essential because Nokia remained extraordinarily successful in the market it had helped create even as another market was beginning to redefine the industry. Its factories, distribution relationships, engineering expertise and brand recognition still provided enormous advantages. Yet the significance of a mobile phone was changing. Customers would increasingly judge devices not merely by their ability to make calls and send messages but by the software, applications and online services available through them.
The Smartphone Revolution Changed the Rules
Nokia did not enter the smartphone era as a company unfamiliar with advanced mobile computing. It had experimented with combining telephone functions and computing capabilities long before Apple introduced the iPhone. The Nokia 9000 Communicator, launched in 1996, incorporated features associated with a personal digital assistant, including email and productivity functions. Later devices offered cameras, internet access, multimedia functions and increasingly sophisticated software.
The Nokia 7650, introduced in 2002, was among the company’s early camera-equipped smartphones, while the Nokia N95, released in 2007, combined features such as navigation, multimedia playback, a capable camera and internet connectivity. These products demonstrated that Nokia understood the potential for a handset to perform tasks beyond voice communication. The problem was not an absolute inability to imagine the smartphone. It was that the emerging market began rewarding a different combination of technical capabilities, user experience and software development.
For much of the earlier smartphone era, Nokia relied on Symbian, an operating system designed for mobile devices with constrained processing power, memory and battery capacity. Those restrictions mattered when mobile hardware was relatively limited. Symbian allowed phones to perform increasingly complicated tasks without the power consumption or hardware requirements associated with desktop computing. Its engineering strengths helped Nokia deliver advanced features during a period when mobile computing was still developing.
However, an operating system optimised for earlier devices was not automatically ideal for the next generation of smartphones. Symbian had evolved through different user-interface implementations, software versions and development arrangements. Nokia’s S60 interface became especially important, but the broader Symbian ecosystem also included other approaches that were not fully interchangeable. This fragmentation complicated development and made it harder to provide customers and software developers with a consistent experience across devices.
Apple’s introduction of the iPhone in 2007 brought these issues into sharper focus. The original iPhone was not necessarily superior to Nokia’s advanced handsets in every technical feature. Its significance lay in the way Apple designed the screen, interface and core functions as a coherent experience. Large areas of the display responded directly to touch, allowing customers to browse websites, navigate photographs and select functions through familiar gestures rather than relying primarily on keypads and complicated menus.
The launch of Apple’s App Store in 2008 extended that approach beyond the capabilities installed on the device at purchase. Customers could discover applications through a central marketplace, while developers gained a common distribution channel and access to an expanding audience. The phone became a platform capable of acquiring new functions throughout its useful life. A customer purchasing a smartphone was increasingly choosing not only a device but also a continuing relationship with its software ecosystem.
Android entered the commercial market in 2008 with a different organisational model. Rather than reserve its operating system for one manufacturer’s products, Google made Android available to multiple handset manufacturers. Companies could compete through hardware, pricing, industrial design and distribution while developing around a shared software platform. Google’s services and the expanding Android application ecosystem helped create a powerful alternative to Apple’s more tightly integrated approach.
These developments changed the economics of smartphone competition. A platform became more attractive to customers as useful applications accumulated, while a growing customer base encouraged more developers to build applications for that platform. This positive feedback could strengthen established software ecosystems and make life harder for smaller competitors. A manufacturer could produce an excellent handset and still struggle if customers could not obtain the applications and services they increasingly expected.
The changing structure of the smartphone industry therefore placed operating systems and software platforms at the centre of competition. Hardware continued to matter, but its commercial value became more closely tied to software compatibility, developer participation and service integration. Nokia’s expertise in physical devices remained valuable, yet it no longer guaranteed that the company’s phones would offer the most attractive overall experience.
This shift also weakened some of Nokia’s traditional advantages. Its ability to offer many models at different prices had previously helped it serve an enormous customer base. In a software-driven market, however, maintaining numerous device variants could introduce additional development and compatibility problems. The company needed to combine the flexibility of its handset portfolio with a much more unified software experience.
Nokia recognised that internet services were becoming central to the business. In 2007, it introduced Ovi as a brand intended to bring services such as maps, music, content sharing and synchronisation closer to its devices. The initiative demonstrated an effort to extend Nokia’s relationship with customers beyond the original handset purchase. Yet identifying the importance of services was different from developing a seamless ecosystem that could compete with Apple and Android.
The smartphone revolution was therefore not simply a transition from physical buttons to touchscreens. It was a change in where competitive advantage was created and how that advantage accumulated. Nokia had become dominant by producing reliable devices at tremendous scale. The new competition rewarded companies capable of coordinating hardware, operating systems, applications, developers and online services into an experience customers preferred to competing alternatives.
Why Nokia’s Software Strategy Failed to Catch Up
Nokia’s central difficulty was not a complete absence of technological ambition. Between 2007 and 2010, the company invested in several initiatives intended to strengthen its smartphone position. It continued developing Symbian, expanded its internet services, established an application marketplace and pursued a more modern operating-system platform. These projects addressed genuine weaknesses, but they also reflected a company trying to maintain its successful existing business while constructing a different future.
Symbian presented the most immediate problem. Its architecture had been developed under constraints that no longer defined the leading edge of smartphone design. Supporting different interfaces, versions and device requirements made substantial changes difficult to coordinate. Developers faced additional complexity when applications needed to operate across incompatible or differently configured devices, while customers encountered inconsistent software experiences under the same Nokia brand.
The problem extended beyond individual applications. An operating system shapes how people move between functions, access information, manage media and interact with online services. When customers repeatedly encounter confusing menus, slow responses or inconsistent controls, powerful hardware cannot always compensate. Nokia could improve a camera, battery or display without necessarily resolving the frustration created by the surrounding software.
In 2008, Nokia announced plans to acquire the remaining shares in Symbian Limited and support the platform through the Symbian Foundation. The strategy was intended to broaden participation, reduce barriers to adoption and strengthen Symbian’s position against emerging competitors. Nokia was trying to preserve the advantages of an established operating system while giving it a more sustainable future. Yet the transition also required coordination among developers, manufacturers and organisations whose priorities were not necessarily identical.
Meanwhile, Nokia continued releasing touchscreen devices and updating Symbian. The Nokia 5800 XpressMusic, introduced in 2008, represented a substantial touchscreen effort, and the Nokia N97 followed in 2009 with ambitions to combine advanced smartphone functions and a more flexible interface. Later, Symbian^3 offered improvements to touchscreen operation and multimedia capabilities, including through the Nokia N8. These devices demonstrated continuing technical development, but incremental improvements did not fully resolve the broader problem of delivering a modern, consistent software experience.
Nokia’s Ovi initiative faced related challenges. The company had introduced the brand in 2007 to organise internet services around its phones, and the Ovi Store followed in 2009 as an application distribution platform. Maps, music, content and synchronisation were important elements of the strategy. The difficulty was turning these separate offerings into a coherent customer experience that could compete with platforms whose application distribution and software interfaces were rapidly becoming central attractions.
A company can introduce a store without immediately creating a thriving application ecosystem. Developers must find its tools practical, customers must find its applications useful, and the commercial opportunity must justify the effort required to support the platform. When development is more complicated or the audience appears less commercially promising, software producers may prioritise competing systems. Nokia had the advantage of a substantial installed customer base, but the value of that audience was weakened by software fragmentation and uncertainty about the platform’s direction.
Another major initiative emerged from Nokia’s work on Linux-based operating systems. In February 2010, Nokia and Intel announced MeeGo, a new open-source software platform combining Nokia’s Maemo project with Intel’s Moblin development. MeeGo was intended to support a range of computing devices and provide a more modern foundation for future products. Its development also involved efforts to improve application creation and portability, including through the Qt software framework.
MeeGo offered an opportunity to move beyond some of Symbian’s historical limitations. However, it introduced another complex programme into an organisation already trying to improve its existing smartphones, manage numerous devices and expand its online services. Nokia now had to sustain current sales while developing a credible successor platform that was not yet ready to replace the established business at scale. The longer this transition continued, the more difficult it became to present a clear and convincing software strategy to customers and developers.
This was a problem of timing as much as technological direction. Apple and Android manufacturers were improving products, expanding application catalogues and attracting developers while Nokia worked on several potential solutions. Every delay in establishing a consistent platform gave competing ecosystems more opportunities to grow. The market did not suspend its development while Nokia reorganised its software ambitions.
Technical fragmentation was only one part of the explanation. Nokia had developed strong managerial and engineering processes around producing complex physical devices in large numbers. Delivering successive handset models required disciplined manufacturing, component procurement, reliability testing and coordination with mobile operators. Those capabilities remained valuable, but rapidly evolving software required an organisational environment in which problems could be identified early, priorities adjusted and development decisions coordinated across teams.
Research into Nokia’s smartphone failure suggests that these organisational processes were not functioning effectively enough. Timo Vuori and Quy Huy examined how fear and communication problems influenced decision-making inside the company. Their work, discussed in INSEAD’s analysis of how Nokia contributed to its own decline, identifies a pattern in which senior managers experienced pressure from competitors while middle managers feared the consequences of delivering unwelcome information.
Under those conditions, communication could become distorted. Managers concerned about reporting delays or technical difficulties might present development progress more favourably than circumstances justified. Senior executives could then make strategic commitments based on expectations that development teams were unlikely to meet. The resulting gap between promised outcomes and actual capabilities made it harder to coordinate projects and respond realistically to competitors.
These findings should not be interpreted as proof that every Nokia executive deliberately concealed information or that organisational fear alone destroyed the company. The research draws substantially on retrospective accounts of a complicated period, and Nokia’s failure also reflected external competition, technical constraints and changing customer expectations. Its importance lies in showing how internal behaviour can compound technological problems. Even capable engineers and substantial research budgets are insufficient when the organisation struggles to communicate problems accurately and act on them collectively.
The interaction between Nokia’s software challenges and its organisational structure created a particularly difficult cycle. Fragmented development made schedules and compatibility harder to manage, while pressure to deliver competitive products encouraged optimistic commitments. Delayed or imperfect products then weakened customer confidence and increased management pressure. Nokia’s multiple software initiatives were intended to break this cycle, but coordinating them became another demanding task.
Nokia was therefore attempting a difficult transition while continuing to operate an enormous global handset business. Its existing products still served millions of customers, and abandoning them prematurely would threaten current revenue. Yet investing heavily in the established platform could also divert resources from its successor. Every possible decision carried significant commercial risks.
By 2010, Nokia still possessed enormous engineering resources, a recognised brand and substantial market presence. It had also demonstrated that it understood many elements of the smartphone challenge. What remained unresolved was whether the company could convert its different initiatives into one competitive platform quickly enough. That uncertainty became central to the next leadership transition.
The Burning Platform, Windows Phone, and the Microsoft Sale
Olli-Pekka Kallasvuo became Nokia’s chief executive in 2006, shortly before Apple introduced the iPhone. His leadership period encompassed the company’s efforts to develop Symbian, launch Ovi and pursue a successor operating system. By 2010, however, Nokia faced increasing pressure from competitors whose software ecosystems were expanding rapidly. The company remained a major handset manufacturer, but its ability to determine the future direction of the smartphone market had weakened.
In September 2010, Stephen Elop succeeded Kallasvuo as Nokia’s chief executive. Elop had previously worked at Microsoft, making him an unusual choice for a company historically associated with Finnish management and engineering culture. He arrived with a mandate to improve Nokia’s competitive position and confront the growing uncertainty surrounding its smartphone strategy. His leadership would lead to one of the most consequential platform decisions in the company’s history.
In February 2011, Elop circulated an internal message that became famous as the burning platform memo. The document described a man standing on an oil platform surrounded by flames, forced to choose between remaining in danger and jumping into uncertain waters. Elop used the metaphor to communicate the urgency of Nokia’s position. He argued that the company faced serious competitive threats and needed changes extending beyond improvements to existing products.
The memo subsequently became public, creating an unusually visible account of Nokia’s internal difficulties. Its language was striking because it came from the chief executive of a company that still sold an enormous number of mobile phones. Rather than merely promising a new product, Elop acknowledged substantial problems in the company’s existing strategy and execution. The message also raised questions about the future of Symbian before Nokia had established a successful replacement.
That same month, Nokia and Microsoft announced a broad strategic partnership. Windows Phone would become Nokia’s principal smartphone operating system, replacing Symbian in that role. Nokia would contribute its handset engineering, design, distribution and mobile expertise, while Microsoft would supply the software platform and associated services. The companies intended to create a competitive third ecosystem alongside those led by Apple and Google.
The partnership had a strategic rationale. Nokia could concentrate more attention on handset development and integration while relying on Microsoft to provide the software foundation. Microsoft’s resources and established software capabilities offered the prospect of building an alternative platform with sufficient scale to attract customers and developers. Windows Phone also offered a way to distinguish Nokia’s products from the increasingly crowded market of Android manufacturers.
Choosing Android would have involved different risks. The operating system already had substantial momentum, but several manufacturers were competing through it, creating intense pressure around handset design, pricing and differentiation. Nokia would have needed to establish a compelling reason for customers to purchase its Android products instead of alternatives from companies such as Samsung or HTC. Joining the Android ecosystem might have reduced some software-development burdens, but it would not automatically have restored Nokia’s commercial leadership.
Continuing with MeeGo also presented uncertainty. Nokia had invested in the platform, and it offered the prospect of greater independence over software development. However, building a modern operating system and attracting developers demanded considerable time, coordination and resources. Nokia needed a competitive response while its existing smartphone business was already under pressure. The eventual Windows Phone decision reflected management’s assessment of these competing risks, not the absence of other conceivable strategies.
Nevertheless, the Microsoft partnership introduced a particularly dangerous transition period. Symbian phones remained commercially important, but customers and developers now knew that Nokia intended to move its future smartphone business towards Windows Phone. Buyers considering an expensive Symbian handset had reasons to question how much future support and application development it would receive. Developers faced similar uncertainty about which platform deserved their investment.
This transition problem is sometimes described through the Osborne effect, in which announcing a replacement can undermine demand for an existing product before its successor is ready. Nokia’s situation was more complicated than that simple mechanism, because Symbian already faced substantial competitive pressure. The February 2011 announcements may have increased uncertainty surrounding the platform, but they did not create its technical difficulties or the broader movement towards competing ecosystems. The timing of Nokia’s strategy added another burden to an already challenging recovery.
The first Nokia Lumia smartphones reached customers later in 2011. Their industrial design and the distinctive Windows Phone interface offered a visibly different experience from older Symbian devices. Nokia continued developing the Lumia range and attempted to establish a position through design, photography, navigation and integration with Microsoft’s services. Yet an attractive handset could not immediately overcome the application and ecosystem disadvantages faced by Windows Phone.
Developers had limited resources and commercial incentives. Many already prioritised iOS and Android because those platforms offered large, growing audiences. Supporting Windows Phone required additional work whose expected returns could be uncertain. Consumers, meanwhile, could encounter missing applications or differences in functionality that made the platform less attractive despite Nokia’s hardware quality.
Further complications arose as Microsoft developed the operating system. The transition from Windows Phone 7 to Windows Phone 8 introduced new technical capabilities but also created compatibility limitations for earlier devices. Customers and developers had to navigate another platform transition while Nokia was attempting to build confidence in its new strategy. Lumia sales grew from a relatively small base, but their expansion was insufficient to compensate quickly for the contraction of Nokia’s established smartphone business.
Nokia’s financial position consequently came under increasing pressure. The company had to support product development, marketing and restructuring while fighting competitors whose ecosystems were already established. Its traditional manufacturing and distribution strengths still mattered, but they could not independently generate the developer participation and software momentum necessary to transform Windows Phone into a leading platform.
In September 2013, Nokia announced an agreement to sell substantially all of its Devices & Services business to Microsoft. The announced transaction was valued at approximately €5.44 billion, including arrangements relating to Nokia’s patent portfolio. After regulatory and other completion processes, Nokia finalised the sale on April 25, 2014.
The transaction marked the end of Nokia Corporation’s ownership of the handset business that had made its name globally famous. Microsoft acquired the principal devices operation, while Nokia retained its telecommunications infrastructure business, important intellectual-property assets and other activities. The company was not being liquidated, and its patents were not simply transferred wholesale as part of an unrestricted sale.
The distinction matters when interpreting Nokia’s failure. The original Finnish company survived, but the smartphone strategy through which it had hoped to preserve handset leadership had not succeeded. The Windows Phone decision deserves scrutiny because of its risks, execution and timing, yet it followed several years of technical and organisational difficulties. Treating the 2011 partnership as the single cause of Nokia’s collapse obscures the problems that made such a drastic decision attractive to management in the first place.
When Nokia’s Collapse Reached Salo
Nokia’s decline was not experienced only through falling market share, financial losses or strategic announcements. In Finland, the company’s handset operations supported manufacturing jobs, specialist engineering work and economic activity in communities closely associated with its growth. Salo, a town in southwestern Finland, was one of the places where the consequences became particularly visible. Nokia’s international success had created local employment and skills that were difficult to replace when production contracted.
A contemporary account helps illustrate the human dimension. In April 2012, Associated Press reporting on Salo’s uncertain economic future described the circumstances of former Nokia technician Tomi Marjuaho. He had taken a severance package in 2010 after leaving the company but continued struggling to find suitable employment and replace the income his household had depended upon. The payment provided temporary financial support, but it did not solve the longer-term problem of finding another regular wage.
Marjuaho’s experience occurred before Nokia announced its next major round of restructuring. It illustrates a distinction that employment statistics alone cannot capture: a worker’s departure from a company and the restoration of financial security are separate events. Manufacturing employment can provide stable incomes, specialised professional identities and connections to a local economy. When those positions disappear, workers may find that their experience does not translate immediately into comparable opportunities nearby.
In June 2012, Nokia announced plans to reduce its global workforce by as many as 10,000 positions by the end of 2013 as part of a broader restructuring programme. The proposals included closing its handset manufacturing facility in Salo while retaining research and development activities there. The distinction between production and development reflected Nokia’s changing operational priorities, but it did not preserve the factory employment associated with assembling devices. Manufacturing operations in Salo ended in 2012, bringing an important chapter of Finnish handset production to a close.
The effects were not identical for every employee. Some workers had different skills, severance arrangements or employment opportunities, while others faced prolonged uncertainty. The broader economic consequences also extended beyond Nokia’s direct workforce to suppliers, service businesses and households connected to local spending. These outcomes should not be reduced to a single former employee’s experience, but individual accounts provide context that aggregate restructuring figures cannot.
Salo demonstrates why Nokia’s smartphone failure mattered beyond the technology industry. The company’s earlier success had connected local communities to an enormous global market, making their prosperity partly dependent on decisions and competitive developments occurring far beyond Finland. When Nokia lost its position, the costs were distributed across people who had played no direct role in choosing Symbian, MeeGo or Windows Phone. The corporate transformation that followed would preserve Nokia as a business, but it could not automatically restore the manufacturing economy built around its old handset operations.
How Nokia Reinvented Itself After Mobile Phones
The sale of Nokia’s handset business was a dramatic break with its recent past, but it did not leave the company without substantial operations. Nokia had continued developing and supplying telecommunications networks throughout its years of handset dominance. Its customers included mobile operators and other organisations purchasing the equipment necessary to transmit calls, data and internet traffic. Unlike consumer handsets, these systems were largely invisible to the people using them, even though they formed essential parts of modern communications infrastructure.
Nokia’s network business had its own history of consolidation. In 2007, Nokia and Siemens established Nokia Siemens Networks, combining important telecommunications equipment operations. Nokia subsequently acquired Siemens’ stake in 2013, gaining full control of the venture. As the consumer handset business moved towards Microsoft, this infrastructure operation became the foundation for the corporation’s next phase.
The network market differed significantly from consumer mobile phones. Equipment manufacturers competed for major contracts with telecommunications operators, whose purchasing decisions involved coverage, capacity, reliability, operating costs and long-term support. Building networks required expertise in radio technology, software, standards and the integration of complex systems. Nokia already possessed many of these capabilities, giving it a substantial operating business that could continue independently of its former handset division.
Nokia strengthened this position through a major acquisition. In April 2015, it announced an agreement to acquire Alcatel-Lucent in an all-stock transaction valued at approximately €15.6 billion. The companies began combined operations in January 2016, creating a broader telecommunications infrastructure supplier with expertise spanning mobile and fixed networks, internet routing and optical communications.
The acquisition also brought Bell Labs into Nokia’s organisation. The research institution had an extensive history of contributions to telecommunications and computing, giving Nokia access to important scientific and engineering capabilities. More broadly, Alcatel-Lucent helped expand the company’s range of technologies beyond mobile radio systems. Nokia could now address a wider set of infrastructure requirements associated with the networks connecting households, businesses, data centres and telecommunications operators.
This transformation was not simply an attempt to abandon a failed business and pursue something unfamiliar. Network infrastructure had been part of Nokia’s operations for decades, and earlier corporate decisions had helped establish its position in that market. The handset sale allowed the company to concentrate more heavily on an activity in which it already possessed relevant expertise. Its history of diversification and restructuring had once again created the possibility of a different corporate future.
Meanwhile, the familiar Nokia name continued appearing on mobile phones, although the ownership arrangements were substantially different. In 2016, the Finnish company HMD Global announced arrangements to bring Nokia-branded mobile devices to market. HMD was an independent business operating under licensing agreements, not a restoration of Nokia Corporation’s former handset division. The distinction was important because consumers could encounter a Nokia-branded phone without purchasing a device manufactured and marketed by the original corporation.
In 2017, HMD introduced devices including the Android-based Nokia 6 and a redesigned version of the Nokia 3310. The Nokia 6 represented the brand’s participation in the modern Android smartphone market, while the revived 3310 drew on memories of Nokia’s earlier handset success. Both demonstrated the continuing commercial recognition attached to the Nokia name. However, a licensing arrangement is not the same as rebuilding the industrial, organisational and commercial structure that once made Nokia the world’s largest handset manufacturer.
Nokia Corporation’s main strategic direction remained focused on telecommunications technology. Its operations supported mobile networks, fixed communications infrastructure, routing, optical transmission and related services. The arrival of 5G increased the complexity of network systems and created demand for equipment capable of supporting more data-intensive applications. At the same time, competition from other major telecommunications equipment suppliers required continuing investment in research, software and engineering.
The company’s infrastructure strategy evolved as network technologies and customer requirements changed. In February 2025, Nokia completed its acquisition of Infinera, expanding its position in optical networking. Optical communications had become especially important as data centres, cloud services and increasingly demanding computing workloads required greater network capacity. The acquisition strengthened Nokia’s participation in technologies connecting large concentrations of computing equipment as well as conventional telecommunications networks.
By October 2026, Nokia’s reporting reflected a corporation organised around Network Infrastructure and Mobile Infrastructure rather than consumer handset manufacturing. According to its third-quarter 2026 interim report, the company generated approximately €5.154 billion in quarterly net sales. That revenue came from a fundamentally different business from the one that had previously made Nokia phones everyday consumer products.
The transformation did not remove the ordinary challenges of industrial competition. Telecommunications infrastructure requires substantial research investment, and customer purchasing decisions can be affected by network spending cycles, technology transitions, regulation and geopolitical developments. Nokia must continue competing with established suppliers and emerging alternatives while developing products that meet increasingly complex technical requirements. Its survival does not mean that future success is guaranteed.
Nevertheless, Nokia’s continued operations change the meaning of its familiar rise-and-fall story. The company lost control of the consumer product category through which most people knew it, but retained and expanded capabilities in another part of the communications industry. Its brand remained recognisable through licensing, while its principal commercial identity shifted towards the infrastructure that allows communications services to function.
This outcome also reveals the limits of treating companies as though they were synonymous with their most successful products. Nokia had been a paper manufacturer before it became associated with rubber products, and an industrial conglomerate before it became a mobile-phone leader. Its infrastructure business existed alongside its handset empire and eventually became the foundation for corporate survival. The company was not rescued by nostalgia for its old phones; it continued through assets, expertise and markets that consumers had rarely associated with its name.
Nokia’s history is ultimately a story of changing competitive advantages. Manufacturing excellence, distribution, reliability and usable hardware enabled the company to dominate conventional mobile telephony. Those strengths became insufficient when operating systems, applications and developer ecosystems acquired greater importance. Nokia attempted to respond, but technical fragmentation, organisational weaknesses, execution difficulties and the risks of its platform transition prevented it from sustaining handset leadership.
The consequences were substantial. Nokia lost its defining consumer business, Microsoft acquired the handset operations, and communities such as Salo experienced the disruption of jobs and industrial activity connected to the company’s earlier success. Yet Nokia Corporation continued developing technologies essential to modern communications, extending its infrastructure business through acquisitions and research.
The company that began beside a Finnish river in 1865 is no longer the mobile-phone manufacturer that dominated the early 2000s. Its history demonstrates both how an established leader can lose a market when the basis of competition changes and how a corporation can survive by concentrating on different capabilities. Nokia did not win the smartphone war, but its story did not end with the phones it lost.
Last Updated on October 29, 2026 by Aseem Gupta