Reading Time: 23 Minutes
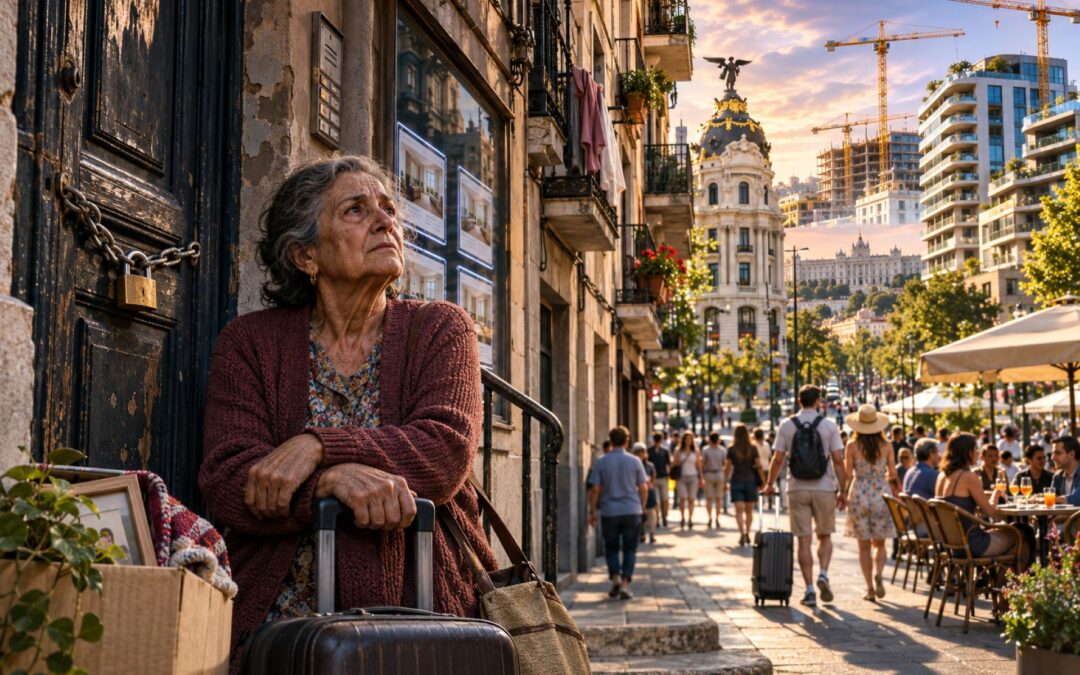
On 23 September 2026, a crowd gathered outside an apartment building in Madrid’s Retiro district. Inside was María del Carmen Abascal, known to her neighbours as Maricarmen, an 87-year-old woman whose family had rented the same home since 1956. She had grown old there, but the building’s ownership had changed, the legal protection surrounding her tenancy had unravelled, and she was about to lose the place she knew as home.
Maricarmen left the building in a wheelchair and was transferred to a stretcher. Within days, her eviction had helped draw thousands of people onto Madrid’s streets and into a protest camp in Puerta del Sol. She died in hospital on 7 October, before she could move back into the apartment under a last-minute agreement.
The crisis quickly became national politics. Emergency housing measures failed in parliament, Prime Minister Pedro Sánchez called an early election, and Spain’s apparently impressive economic record became the subject of a much angrier question: if the country was doing so well, why were so many people finding ordinary life increasingly difficult to afford?
Spain was growing faster than several of Europe’s largest economies, adding jobs and attracting investment. Yet a severe shortage of homes, expensive rents and limited progress in purchasing power were making that success feel remarkably distant from everyday life. The contradiction did not begin with Maricarmen, and it could not be explained by one unpopular landlord, one government or one economic statistic.
The Eviction That Turned a Housing Crisis into a Political Crisis
Maricarmen was 17 when she moved into the sixth-floor apartment on Calle del Alcalde Sainz de Baranda in 1956. Her father had signed the original lease, and the family lived under an older rental arrangement whose relatively low rent became an important source of stability. After her father’s death, the tenancy passed to her mother; after her mother’s death, it passed to Maricarmen. By the time the dispute reached its final stage, she was paying roughly €500 a month in rent and associated charges for a home of around 90 square metres.
The apartment was purchased in 2018 by Urbagestión Desarrollo e Inversión, a property company. For a while, Maricarmen continued paying as before. Then, in 2020, the company told her to leave, arguing that the successive transfers of the old tenancy had reached their legal limit. What followed was not simply a landlord demanding a higher price and a court automatically agreeing. It was a complicated dispute about whether her right to remain under the inherited contract had expired.
A court of first instance initially sided with Maricarmen. The company appealed, and in June 2022 the provincial court ruled against her, interpreting the tenancy succession rules differently. Spain’s Supreme Court later declined to hear her appeal, leaving that decision standing. The owner subsequently offered a different rental arrangement at a price far beyond what she had been paying; contemporary reporting described an offer of about €1,600 a month against a pension of roughly €1,400. For Maricarmen, the legal distinction did not make the practical problem any less frightening: she risked losing the apartment in which she had spent almost her entire life.
There were four attempts to evict her. The first, in autumn 2025, was suspended after neighbours and tenant activists mobilised. Two more attempts in June 2026 were also postponed amid public pressure. By the fourth attempt, scheduled for 23 September, Maricarmen’s health had deteriorated. Supporters spent the night outside the building, hoping their presence would prevent her removal. Police eventually carried out the eviction, and she was taken to Madrid’s Gregorio Marañón hospital.
The chronology matters because the case was neither a sudden eviction from nowhere nor a simple story of tenants refusing to pay. Maricarmen had continued paying her rent while the legal dispute unfolded. Residents saw a person whose stability depended on a decades-old contract confronting a modern property market in which the same apartment could command a vastly higher price. Her supporters regarded the outcome as an indictment of a system that could be legally defensible while feeling socially intolerable.
The consequences extended far beyond the building. On 26 September, tens of thousands marched through Madrid, and some protesters pitched tents in Puerta del Sol. The camp grew, with the tenant movement pressing for protections against eviction and rental insecurity. Sánchez’s government hurriedly assembled two emergency housing decrees, but the opposition People’s Party, Vox and the Catalan party Junts voted against them on 1 October. On 5 October, Sánchez announced an early general election for 29 November, turning the dispute into a central issue of the campaign.
Meanwhile, there had been a breakthrough in Maricarmen’s individual case. On 28 September, the property company, her lawyer, tenant representatives and Madrid’s city authorities reached an agreement for her to return under an eight-year lease at a rent close to the old one. The company signed the contract and handed over the keys on 2 October. Maricarmen was due to sign and return herself, but she died on 7 October, one day before that planned signing. The return she and her supporters had fought for never happened.
The tenant movement’s subsequent demonstrations and November general strike reflected a wider anxiety: millions of people were watching property values and rents rise faster than their ability to secure a home.
Europe’s Economic Success Story Has an Affordability Problem
The striking feature of Spain’s situation is that its economic performance was not imaginary. While Germany struggled with industrial weakness and other major European economies grew slowly, Spain experienced a stronger recovery, expanding employment and activity across services, tourism and other sectors. Its economy had become one of the euro area’s relative success stories, which gave Sánchez a substantial record to defend.
The European Commission’s May 2026 forecast recorded growth of 2.8% in 2025 and projected a further 2.4% in 2026. It expected unemployment to fall below 10%, although that was a forecast rather than a completed annual result. The same assessment pointed to resilient domestic demand, investment and a growing workforce supported by migration. For a country that had endured extraordinarily high unemployment after the financial crisis, those improvements were significant.
The trouble begins when national growth figures are treated as a summary of everyone’s circumstances. Gross domestic product measures the value of goods and services produced. It does not tell us how the proceeds are shared, what an average worker earns after inflation, or how much money remains when rent and essential bills have been paid. A country can generate more economic activity while a renter in Madrid finds the next lease less affordable than the last.
GDP per capita brings the population into the calculation by dividing total output by the number of residents. It is more informative than aggregate GDP when comparing average economic performance, but it remains an average, not the income of a typical household. It also does not subtract the cost of securing a home in a particular city or distinguish a person with a paid-off property from someone searching for their first apartment.
The comparison becomes even more complicated when wages, taxes and property are considered. Someone who already owns an apartment may see their household wealth rise alongside property prices, while a young person with a similar salary experiences the same increase as an ever more distant obstacle to ownership. A business can expand its turnover by hiring more workers, and the government can collect additional taxes, without the typical employee feeling proportionately richer.
Sánchez’s claims about purchasing power therefore need to be judged against the exact indicators and time periods being compared. Spain can outperform France or Germany in one measure without outperforming them in every measure that affects living standards. There are also real benefits in lower unemployment and more stable jobs that should not be dismissed simply because rent remains expensive.
The proper question is not whether Spain has grown. It is whether that growth has translated into sufficiently broad and durable gains in household welfare. Housing is where the gap between the national success story and individual experience has become hardest to ignore.
Why Tourism and Holiday Rentals Became the Enemy
Barcelona offers an unusually vivid expression of the frustration. In the summer of 2024, demonstrators protesting overtourism confronted visitors and, in some incidents, sprayed them with water pistols. The slogan urging tourists to go home appeared on walls and banners. What outsiders saw as hostility toward holidaymakers was also a complaint about the transformation of neighbourhoods into places increasingly organised around short stays rather than permanent residents.
Tourism matters enormously to Spain’s economy. Hotels, restaurants, airlines, shops, transport services and cultural attractions employ substantial numbers of people and bring spending into cities and coastal regions. According to the national statistics institute, Spain welcomed a record 96.8 million international tourists in 2025, almost twice its resident population. That counts visits, not distinct people or simultaneous arrivals.
Holiday rentals sit at the centre of the political argument. In highly visited neighbourhoods, a flat marketed by the night can be financially more attractive than one rented to a family by the year. When enough owners make that calculation, the stock of homes available to local residents can shrink. Noise, turnover, rising commercial rents and the disappearance of ordinary neighbourhood services can intensify the feeling that residents have been displaced without ever leaving the city.
Barcelona has therefore committed to ending roughly 10,000 tourist-apartment licences by 2028. National authorities have also acted against tens of thousands of allegedly illegal short-term rental listings, including properties advertised through Airbnb. For tenants competing for scarce housing, these measures have an obvious appeal: a flat used for holidays might become a home again.
Yet the numbers cannot simply be added as though every tourist listing were an immediately available long-term rental. Some properties are second homes or seasonal accommodation; others are in locations with little year-round demand, while some listings may duplicate properties or never have complied with residential-use rules. An estimate of hundreds of thousands of tourist flats nationally is informative about the market’s size, but it is not a reliable count of homes that can be recovered overnight.
There is a deeper geographical problem as well. Housing demand is intense around Madrid, Barcelona and employment centres, not evenly spread across the country’s beaches, mountains and smaller towns. Converting a holiday apartment in one municipality does not necessarily help a worker who must live near a hospital, university or office elsewhere. And even a substantial transfer from tourism into residential use would be a one-time increase in supply, while new households continue to form year after year.
None of this makes tourism restrictions pointless. Where short-term rentals are displacing permanent housing, enforcing licensing rules and limiting conversions can protect neighbourhoods. But the policy also imposes costs on owners and the tourism economy, and its effect depends on local conditions. If an expanding city cannot add enough homes, a ban on holiday lets can relieve one source of pressure without removing the underlying scarcity.
The anger directed at tourists is thus a symptom of a larger collision between Spain’s economic model and its housing capacity. Tourism helps the economy grow; successful tourist destinations attract workers and investment; yet the resulting demand for urban space can price some of those workers out. Treating visitors as the sole cause obscures the difficult question of why so little suitable housing has been made available alongside that success.
Rent Controls, Tenant Protections, and Their Unintended Effects
Faced with fast-rising rents, governments can intervene more quickly in contracts than in construction. A regulation limiting what a landlord may charge can take effect long before a new apartment block receives permission to be built. For a household worried about the next rent increase or losing its home, that difference in timing is not an abstraction. It is one reason tenant protections have such strong political appeal.
Spain’s 2023 Housing Law created a framework for rent regulation in designated stressed residential markets. The precise rules depend on the area, the type of landlord, the dwelling and the contract, but the intention was to curb escalating rental charges and protect households exposed to severe market pressure. Barcelona became an important test case, alongside other parts of Catalonia. The government also sought to strengthen protections for vulnerable tenants facing eviction when no adequate alternative accommodation was available.
Rent regulation produces several effects at once, and separating them matters. A tenant who can renew a lease under a limit may gain stability and avoid a sudden jump in housing costs. A newcomer looking for an apartment may face a different problem: insufficient vacancies, fierce competition or eligibility requirements that make finding a property difficult. These outcomes can coexist, so the experiences of an established renter and someone entering the market need not be contradictory.
Landlords may respond by accepting lower rental growth, postponing maintenance, selling the property, or seeking contracts that fall outside particular restrictions. Some may switch to temporary or seasonal arrangements, especially when these offer greater flexibility or revenue. But such responses are not inevitable, and a fall in advertised listings is not automatically evidence that the total number of occupied rental homes has collapsed. Listing platforms show what is being offered at a given moment; registered contracts and housing-stock data answer different questions.
Barcelona’s evidence is revealing precisely because it complicates the slogans. The city’s housing observatory reported that average rents on new contracts fell from about €1,193 per month in the first quarter of 2024 to €1,161 in the final quarter of 2025. Its monitoring of the regulated rental market also recorded 1,374 additional active rental contracts since the controls began. Seasonal contracts declined in the period covered. These figures undermine the claim that Barcelona’s entire rental stock fell by 69%, though they cannot establish every cost of regulation.
There are reasons to treat the findings carefully. Average rent on newly signed contracts can change because the mix of homes rented has changed, and a comparison with what rents might have been without regulation depends on assumptions. A policy can protect a group of renters while still discouraging certain investments or making market access harder for others. Conversely, evidence from one earlier Catalan rent-control experiment cannot automatically settle the effects of a later rule with different coverage and enforcement.
Maricarmen’s case pushed the debate beyond rents to the question of eviction itself. The two emergency measures submitted to the full parliament on 1 October 2026 were defeated when the PP, Vox and Junts opposed them. Their objections differed in emphasis, but opponents raised concerns about legal certainty, property rights and the possibility that additional obligations would discourage owners from supplying rental housing. Tenant organisations argued that withholding protection from vulnerable residents was unacceptable while the shortage remained unresolved.
The story did not end with that vote. Following the 11 November general strike and major housing demonstrations, Spain’s interim parliamentary body considered revised measures on 12 November. One decree passed by 35 votes to 34, extending certain protections against eviction of vulnerable tenants through 2030 where alternative housing could not be provided. It also included restrictions on some speculative transactions, a levy on tourist rentals, limits on certain rent increases and housing-finance incentives. A second decree, which proposed stronger automatic lease renewals and compensation to tenants when landlords ended contracts, failed by 34 votes to 35. The narrow parliamentary outcome left the surviving rules vulnerable to reversal after the election.
The lesson is not that tenants should simply be exposed to market forces, nor that price regulation can produce homes that do not exist. Eviction protection addresses an immediate human risk; rental caps attempt to moderate the price of existing accommodation. Both can be valuable, particularly for vulnerable households. Neither replaces the need to increase the supply of suitable housing, and neither can be evaluated honestly without considering who receives the protection, who struggles to enter the market and how landlords respond over time.
How Spain Went from Building Too Much to Building Too Little
Spain’s contemporary shortage is particularly striking because the country once built homes at an extraordinary rate. During the early and mid-2000s, cranes became a defining feature of the landscape. New estates spread around cities and along the coast, land prices climbed, and construction employed large numbers of people. The boom was so intense that comparisons were made between Spanish homebuilding and the combined output of several much larger European countries.
One important cause was the change in financing conditions after Spain joined the euro. Lower borrowing costs and easier access to credit helped fuel purchases, development and speculation. Banks and especially the regional savings-bank sector financed projects whose viability often depended on continually rising prices. Developers bought land, households borrowed heavily, and rising property values made the entire system appear safer than it was. Building was no longer only a response to the need for shelter; it had also become a vehicle for credit-fuelled wealth creation.
When the global financial crisis struck in 2008, Spain’s property bubble burst. Projects stalled, developers failed, troubled loans weakened the banking system, and construction jobs vanished. Unemployment eventually reached roughly one-quarter of the workforce during the subsequent crisis. Workers left the industry, firms disappeared and the ability to expand construction rapidly was damaged. The impact was not limited to a temporary fall in housebuilding: a generation of households and policymakers learned to associate excessive development with financial catastrophe.
There was a reasonable lesson to learn from that experience. Building too many homes in the wrong places with fragile financing can wreck households, financial institutions and public finances. But avoiding another speculative bubble is different from ensuring that cities can provide enough homes as their populations and economies change. Spain has struggled to make that distinction in practice, even as demand has returned strongly to the metropolitan areas and tourist regions where people most want to live.
The scale of the mismatch is visible in official data. The OECD’s assessment of Spain’s housing constraints reported approximately 345,000 construction permits between 2022 and 2024, compared with 604,000 net new households. Drawing on Bank of Spain estimates, it described a housing shortage of around 600,000 units for 2022–2025. These are not interchangeable measures: permits are approvals rather than completed homes, household formation is demand, and the shortage estimate depends on the period and assumptions used.
Housing cannot be supplied instantly because a map contains empty land. Land must be designated for development, infrastructure planned, legal requirements satisfied, financing arranged and construction undertaken. In Spain, major powers over urban planning sit with autonomous communities and local authorities, while the central government has a more limited direct role. That division is not inherently wrong—local governments understand local needs—but poorly coordinated responsibilities can make development slow and unpredictable.
Planning procedures also have legitimate functions. They help protect environmental resources, historic neighbourhoods, public services and residents affected by major projects. The problem arises when obtaining buildable land, navigating objections and securing permissions become so uncertain that viable homes are never completed. The OECD noted that permitting itself could take up to two years in some circumstances; the entire land-development process can be longer. Broad claims that every Spanish project requires 15 years, however, should not be mistaken for a verified national average.
Nor are permits the only obstacle. Builders need qualified workers, materials, finance and confidence that completed homes can be sold or rented at prices covering their costs. The collapse after 2008 diminished the industry’s workforce, and rebuilding its capacity requires training and stable demand. Municipalities need transport links, schools, water systems and other infrastructure to accommodate growth. Developers may also find luxury housing more profitable than affordable rental accommodation unless incentives and financing conditions are changed.
Spain has an unusually thin stock of social rental housing by international standards. The OECD put it at only about 3% of the housing stock. That leaves many households dependent on private landlords in the same expensive market, rather than offering a sizeable alternative for people who cannot afford market rates. Expanding public and affordable housing is consequently part of the supply challenge, not a separate issue that can be resolved through rent caps alone.
When demand rises where building is difficult, the economics of housing scarcity can push up the value of existing properties without providing anyone with an additional home. Spain experienced the destructive consequences of building too recklessly, then entered an era in which building enough became exceptionally difficult. Escaping that history requires both financial prudence and a credible capacity to produce housing where it is needed.
Immigration, Population Growth, and the Productivity Paradox
If housing construction was so constrained, how did Spain manage to grow rapidly? Part of the answer is that economic output can increase even when the productivity of the average worker changes relatively little. More people can enter employment, more hours can be worked and more services can be delivered. Spain has experienced a major expansion of its workforce, and immigration has been central to that transformation.
For much of its modern history, Spain was a country from which people emigrated in search of work. In recent decades it has become an important destination for newcomers from Latin America, elsewhere in Europe, North Africa and beyond. Foreign-born residents now account for a substantial share of the population, and their importance has become particularly apparent as Spain’s native-born population ages. The change has reshaped the labour market, the customer base of businesses and the demands placed on local services.
An analysis by Funcas estimated that the incorporation of foreign labour accounted for about 47% of Spain’s accumulated GDP growth since 2022. The study also noted that foreign workers allowed sectors facing labour shortages to expand and helped some Spanish-born workers move into better-paid occupations. That is a more informative explanation than the suggestion that the economy simply added people and counted the proceeds as an economic miracle.
There is still an important distinction between growth through additional labour and growth through greater productivity. If a restaurant expands from ten workers to fifteen and serves more customers, total output can increase without each worker producing more per hour. If better equipment, organisation or training allows those ten workers to provide more value, output per worker rises. Both types of growth matter, but sustained improvement in productivity is especially important for higher wages and living standards.
It would nevertheless be wrong to say that adding workers cannot increase GDP per person. Immigrants can fill roles that otherwise remain vacant, complement existing workers, start businesses, pay taxes and raise total production by more than their addition to population. BBVA Research found that immigration contributed to Spain’s GDP-per-capita gains, estimating roughly one-quarter of the increase since 2022 after accounting for productivity differences. The exact share depends on the assumptions, but the direction matters: immigration has not merely inflated the national total while leaving per-person output untouched.
The workforce expansion also intersects with a demographic problem. Spain, like many European countries, has large generations approaching retirement and comparatively low fertility. Its pay-as-you-go pension system depends heavily on contributions from people currently working to support today’s beneficiaries. Additional working-age migrants can strengthen the contribution base and moderate the fiscal burden of ageing, although they too will grow older and eventually qualify for benefits. Immigration buys economic and demographic room; it does not abolish the mathematics of retirement.
This explains the government’s interest in regularising the position of migrants already living and working in Spain. Proposals involving hundreds of thousands of people have attracted intense political attention. But announcing a process, approving applications and granting legal status are not identical events, and the numbers should not be presented as though every contemplated application had already been processed. Legal employment can improve protections for workers while bringing more activity into the formal tax and social-security system.
The housing consequence is real as well. New residents need homes, whether they work in hospitals, agriculture, building sites, delivery services or technology companies. When the population grows quickly in cities where housing supply is sluggish, demand increases and competition for available accommodation intensifies. This pressure should be understood alongside smaller household sizes, internal migration, tourism, investor demand and inadequate construction. Blaming immigrants alone would confuse the immediate addition to demand with the policy failures that prevent supply from responding.
Indeed, migrants can be part of the solution if they work in construction and related trades. Restricting immigration in the name of affordability could therefore reduce some housing demand while also limiting the workforce needed to build more homes, staff businesses and finance pensions. The relevant policy question is not whether Spain should choose economic growth or affordable housing. It is whether population, employment, infrastructure and residential development can expand in a coordinated way.
Why Economic Growth Has Not Translated into Broad Prosperity
Even when GDP per person rises, the typical household may not feel the improvement. One reason is distribution: new income can flow disproportionately to particular companies, workers, property owners or regions. Another is timing. People experience the price of rent, groceries and transport every month, while changes in average productivity or national wealth may take years to affect their own pay.
Spain’s wage record illustrates the tension. The OECD reported in its 2026 assessment of Spanish employment that real wages had risen by around 2% over the previous year but remained about 2% below their level in the first quarter of 2021. This was despite substantial minimum-wage increases that helped protect some low-paid employees. The finding does not mean no workers received meaningful raises, or that Spain’s labour market had made no progress. It shows how inflation can erase much of the apparent benefit of nominal salary increases.
Housing makes those pressures uneven. A retired couple who own their home outright and receive a stable pension face a different budget from a young professional paying market rent in Barcelona. A homeowner with a long-standing mortgage may enjoy relatively predictable housing costs while neighbouring renters confront new lease prices. The same rise in property values can make one family feel wealthier and another feel locked out of an essential part of adult life.
For younger Spaniards, the consequences extend beyond the monthly budget. When rent consumes too much of a starting salary, leaving the family home becomes harder, saving a deposit takes longer and starting a household can be postponed. The transcript cites the striking claim that only around one in seven under-30s lives independently. Precise estimates depend on the year and definition of emancipation, but Spain’s unusually late departure from parental homes is a persistent social and economic concern. It affects personal autonomy, family formation and the ability to move to cities offering better work.
Companies can report strong earnings during the same period. Businesses with growing demand, market power or better technology may raise profits even when their customers feel financially squeezed. Spanish banks, including Santander and BBVA, have enjoyed periods of strong profitability, helped by interest margins and other activities. But profits at six large banks cannot establish that every business is thriving, or that gains come directly from migrants being paid less. The transcript’s specific claims about profits retained per worker require comparable accounting definitions before they can support such a conclusion.
The government also benefits from economic growth. More jobs, spending and profits normally mean a broader tax base, and inflation can increase receipts even when tax rates remain unchanged. A particularly revealing example is fiscal drag: when tax thresholds and allowances are not adjusted for rising prices, nominal salary increases can result in a higher effective income-tax burden without an equivalent improvement in purchasing power.
Spain’s government estimated about €2.3 billion in additional 2025 personal-income-tax revenue from not adjusting tax thresholds for inflation. That does not mean each worker was pushed into a wholly new tax bracket; progressive taxes apply different rates to slices of income, and the effect also involves allowances and deductions. It does mean that an inflation-matching pay rise can leave a household paying more tax in real terms than it would have under an indexed system.
Tax receipts finance pensions, healthcare, education and other public services, so they cannot simply be treated as wealth taken from workers without purpose. The distributional debate is about whether additional revenue is justified, who bears the burden and whether public spending visibly improves everyday life. The same applies to corporate profits: investment and healthy firms create jobs, but the fact that firms are doing well does not by itself answer whether the gains reach employees and customers.
The distinction is ultimately between producing more wealth and making that wealth usable. A person cannot pay rent with the national GDP growth rate. When salaries improve slowly and housing costs absorb a growing share of income, even real economic progress can coexist with widespread dissatisfaction.
Can Spain’s Political Parties Fix the Housing Crisis?
The housing emergency has forced Spain’s parties to propose answers to an uncomfortable combination of problems. Tenants want security and rents they can afford. Prospective buyers want enough homes to make ownership realistic. Existing homeowners often rely on property values to preserve their savings, while landlords want predictable rules and returns. Businesses need workers who can live near their jobs, and the government must support pensions and public services as the population ages.
Sánchez’s Socialist-led government has emphasised tenant protection, rent regulation and measures against speculation. Those policies address immediate insecurities that markets alone may not resolve quickly. Its critics argue that intervention can deter landlords, increase regulatory uncertainty and leave the central supply problem largely untouched. But the central government cannot simply decree thousands of completed apartments into existence. Regional and municipal planning rules, infrastructure and implementation determine how much actually gets built.
There is also political fragmentation. Junts, whose support has mattered to the parliamentary balance, opposed the October emergency decrees. The government’s revised proposals then received sharply different treatment on 12 November, with one surviving and another defeated. Those divisions reveal the difficulty of reconciling eviction protection, stronger lease rights and owners’ objections. The next government could also reverse the surviving measures.
Alberto Núñez Feijóo and the conservative People’s Party offer a more construction-focused pitch. Feijóo has promised a million new homes over a four-year term, changes to land rules and faster building permissions. One proposal would treat an application as approved if a town hall failed to respond within 90 days, subject to the requirement that construction comply with the applicable plan. His proposed faster building approvals are intended to address the delays that make residential development so uncertain.
Faster approvals could increase construction, but delivering a million homes would require more than changing a deadline. Developers need finance and builders, municipalities need infrastructure, and permissions must survive legal and environmental scrutiny. Feijóo has also proposed tax benefits for renters and landlords and incentives to help young people buy homes. Without sufficient additional supply, purchase subsidies and easier credit risk pushing up prices by strengthening demand.
The PP faces another test of credibility. Its politicians control important regional and municipal administrations, including Madrid, where the party has exercised substantial influence for decades. Planning reform therefore depends partly on whether PP-led local authorities are willing to enable the density and development their national leaders advocate. Restrictions sometimes reflect legitimate infrastructure and neighbourhood concerns, but they can also protect the scarcity that keeps existing property valuable. The same contradiction can affect politicians of the left who champion affordability while resisting development close to their own constituents.
Vox introduces a different tension through its hardline immigration agenda, including proposals framed around deportation or remigration of certain groups of foreign residents. Some voters view these measures as a way to reduce pressure on housing and public services. Yet curbing the workforce raises questions about how sectors facing labour shortages would operate and how contributions would support an ageing society. Forecasts suggesting that Spain might need extraordinary numbers of migrants over coming decades should be understood as scenarios based on demographic and pension assumptions, not literal, unavoidable recruitment quotas.
Vox also advocates extensive tax reductions, which supporters argue could leave households and businesses with more money. Such proposals must be weighed against their fiscal costs and the need to fund pensions, healthcare, infrastructure and housing programmes. The experience of the United Kingdom’s short-lived 2022 tax-cutting programme under Liz Truss illustrates why the credibility of financing matters, but it is not proof that all Spanish tax cuts would have the same effects. The design, timing and fiscal conditions are crucial.
The coming election may change which policies are pursued, but it cannot remove the underlying trade-offs. Rent control is easier to announce than new supply is to deliver. Construction reform is easier to promise than to implement across different levels of government. Restricting immigration may appeal to voters facing rising housing costs, but it can also undermine the labour supply and public revenues on which the economy depends. Blaming one group cannot resolve the problem.
Spain is not alone in this predicament. Canada’s experience with population growth outpacing housing supply shows how an affluent country can report economic success while renters and prospective homeowners experience declining affordability. Both cases reveal why a housing shortage becomes especially painful when policymakers treat rising property prices as a sign of prosperity for existing owners and an affordability problem for everyone else.
A country cannot guarantee both cheap housing and permanently rapid appreciation of the same homes. Rising prices can reward people who already own property, but the prospective buyer pays for those gains. Lower prices or slower appreciation may help the next generation while unsettling households that have come to treat property as their principal investment. That is a genuine political conflict, not something a slogan about the free market or tenant rights can make disappear.
Spain’s economic growth deserves recognition. More jobs, productive businesses and the contribution of immigrants are real achievements, and the housing crisis does not erase them. But a stronger economy has to do more than produce an impressive national total. It has to make room for people to live near opportunity, earn a sustainable income, build a household and grow old without fearing that prosperity has made their own home unaffordable.
Maricarmen’s story gave that contradiction a face. The policies adopted after her death may protect some tenants, and future reforms may increase the number of homes, but neither result can be assumed in advance. What Spain needs is not a choice between growth and security; it is a housing system capable of supporting both. Until that happens, the country’s economic miracle will remain real in the statistics and painfully incomplete in the lives of many of the people those statistics describe.