
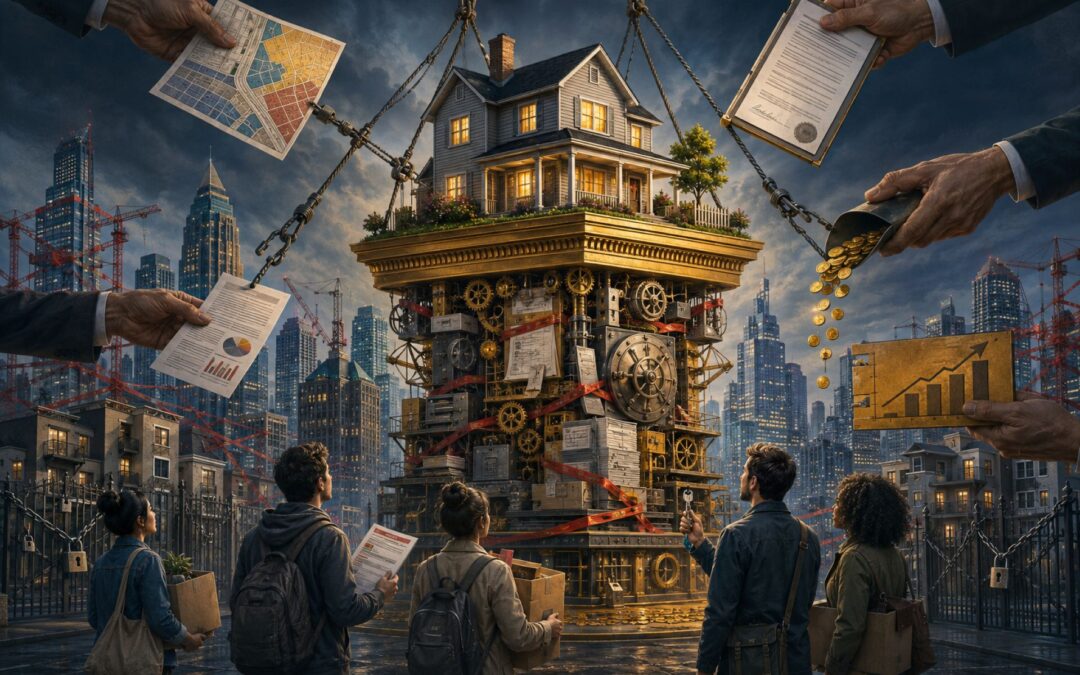
Housing is supposed to be one of life’s basic necessities, yet in some of the world’s wealthiest cities, earning a good salary is no longer enough to buy a home. Vancouver, Toronto, San Francisco, Sydney, Melbourne, London, and Lisbon have all struggled with housing costs that leave ordinary workers competing for homes increasingly disconnected from local incomes.
The obvious explanation is that demand has grown faster than supply. But that raises a more difficult question: why do prosperous cities, with functioning governments and decades of experience, repeatedly fail to build enough housing where people want to live?
Part of the answer is that housing serves two purposes that increasingly conflict. For someone trying to find a place to live, affordable housing means paying less. For someone whose home is their largest financial asset, rising property values represent wealth, retirement security, and an inheritance for their children. Governments promise the first group affordability while reassuring the second that their investments remain secure.
This contradiction influences everything from zoning regulations and property taxes to mortgage subsidies and bank rescues. The housing crisis is not simply the result of greedy developers, wealthy foreigners, or insufficient construction. It is the product of interconnected incentives that often reward expensive housing even as governments claim to oppose it.
The Homeownership Promise That Turned Shelter Into Wealth
The idea that homeownership should create wealth was not originally a sinister economic experiment. It developed partly from a reasonable belief that owning a home could provide families with stability, encourage long-term saving, and give ordinary households an opportunity to accumulate assets.
After World War II, governments deliberately expanded access to homeownership. In the United States, the 1944 GI Bill included mortgage benefits that helped eligible returning veterans purchase homes. The Department of Veterans Affairs’ history of its home-loan programme describes how government loan guarantees became an important part of American housing finance. Canada developed its own mortgage-support institutions, including the Canada Mortgage and Housing Corporation (CMHC), to encourage residential construction and access to credit.
These programmes helped many households build wealth and establish financial security. Buying a home could also encourage saving because mortgage payments gradually converted income into home equity. Unlike rent, part of each principal repayment increased the owner’s stake in an asset.
However, there is an important distinction between a home providing value and its market price continuously increasing.
A factory can become more valuable by producing additional goods, improving efficiency, or earning greater profits. A house provides useful shelter and housing services, and a rented property can generate income, but an unchanged house does not automatically provide more accommodation merely because its resale price increases. Much of its appreciation may instead come from the land underneath it.
Urban land becomes valuable because people want access to what surrounds it: employment, transport, schools, parks, hospitals, businesses, and other residents. When a government builds a railway station or a neighbourhood becomes a thriving employment centre, nearby property owners can receive substantial gains even without improving their buildings.
Scarcity magnifies those gains. If thousands of people want to live near a growing business district but planning rules prevent additional homes from being built, competition for the existing properties can raise land prices dramatically.
That appreciation can make homeowners considerably wealthier. It also creates a powerful incentive to preserve the conditions responsible for the appreciation.
A home gradually becomes more than shelter. It becomes a retirement fund, a source of collateral, a family inheritance, and an investment that owners expect to outperform inflation. Governments reinforce these expectations through mortgage support, preferential taxation, and policies intended to sustain homeownership.
The difficulty appears when a society begins treating substantial housing appreciation as a normal financial expectation. If property values are expected to rise significantly faster than wages, future buyers must devote increasingly large amounts of income to purchasing the same homes.
Existing owners may welcome the appreciation because it increases their wealth. Prospective buyers experience precisely the same development as a loss of affordability. This conflict becomes especially significant when homeowners represent an influential voting constituency and much of the banking system is exposed to residential property.
A policy that makes housing genuinely more affordable can therefore threaten the financial expectations of the people who already own it.
Zoning, Local Vetoes, and the Economics of Scarcity
Housing follows the basic economic relationship between supply and demand. When demand for a desirable location increases faster than the number of available homes, prices tend to rise. Construction can ease that pressure, but only if builders are allowed to provide enough homes in the places people actually want to live.
Many expensive cities prevent precisely that response.
Zoning determines how land may be used, including what types of buildings are permitted, how tall they can be, and how many homes a parcel can contain. These rules serve legitimate purposes. They can separate residential neighbourhoods from dangerous industrial activity, coordinate infrastructure, and protect environmental or historic resources.
However, zoning can also preserve scarcity by restricting large areas of valuable urban land to detached houses or other low-density uses.
A neighbourhood might be close to major employers, public transportation, and excellent schools, yet allow only one home on a large plot. Demand for that location can increase for decades without a corresponding increase in housing capacity. The neighbourhood becomes progressively more expensive, while additional development is pushed toward its outskirts.
The resulting shortage is partly artificial. The land is not necessarily incapable of accommodating more people; the rules prohibit it from doing so.
This is why urban planners frequently discuss missing-middle housing. Between detached houses and high-rise apartment towers are duplexes, triplexes, townhouses, courtyard apartments, rowhouses, and smaller apartment buildings. These forms can accommodate more households without requiring every residential street to become a collection of skyscrapers.
They can also support walkable neighbourhoods, local shops, and public transportation. When cities restrict these options, families may have to choose between expensive detached houses, small high-rise apartments, or longer commutes from distant suburbs.
Zoning restrictions have sometimes served explicitly exclusionary purposes. San Francisco’s early residential zoning helped protect wealthy neighbourhoods and reinforced racial and economic segregation. Rules presented as neutral controls over building types could also limit access to particular communities.
The consequences can persist long after the original justifications become unacceptable. Once a neighbourhood consists primarily of expensive detached houses, existing owners have strong financial incentives to resist changes that might alter its character or increase the housing supply.
This resistance is commonly called NIMBYism, meaning Not In My Backyard. Residents oppose developments near their homes, often citing traffic, parking, sunlight, neighbourhood character, infrastructure capacity, or environmental damage.
Some objections are legitimate. A city should consider whether new construction has adequate water, transport, schools, and other services. Historic preservation and environmental protection can also provide genuine public benefits.
The political problem emerges when almost every proposed development encounters objections, delays, or additional restrictions. Existing residents can attend planning meetings, organise campaigns, and pressure local representatives. The people who would benefit from new homes may not yet live in the neighbourhood, leaving them with little representation in decisions about their future housing.
Environmental review can become part of this conflict. California’s Environmental Quality Act, or CEQA, was designed to ensure that public decisions consider environmental consequences. Critics argue that its procedures can also be used to delay infill housing, even when denser development could reduce outward sprawl and car-dependent commuting.
Vancouver illustrates another trade-off. Its protected public views, often called view cones, limit certain building heights to preserve views of the surrounding mountains. These views contribute to the city’s identity and public spaces, but height restrictions can also reduce development capacity on valuable sites.
Importantly, the rules have not remained unchanged. Vancouver modified its view protections in 2024 and approved further adjustments in December 2025, including changes intended to accommodate additional housing in the Downtown Eastside. The city’s official public-view policies show how planners have attempted to balance skyline preservation with housing capacity.
San Francisco has also moved away from parts of its historically restrictive framework. Its Family Zoning Plan, adopted in December 2025, permits additional housing types and density in selected well-resourced areas, particularly near major transport routes and commercial streets.
These changes demonstrate that restrictive zoning is not permanent. Nevertheless, permission to construct more housing does not automatically produce completed homes. Builders still need finance, viable land prices, infrastructure, permits, and enough expected demand to justify construction.
Zoning reform is therefore necessary in many constrained cities, but it works best alongside financial and administrative reforms that make the newly permitted housing feasible.
The deeper political issue remains that scarcity creates concentrated benefits for existing property owners while distributing its costs among renters, prospective buyers, employers, and future residents. Those bearing the costs are often less organised than those defending the restrictions.
Property Taxes, Land Value, and the Incentive Not to Move
Property taxation presents one of the more counterintuitive explanations for expensive housing. Low property taxes sound like a way to make homeownership affordable, but they can also increase the amount buyers are willing to pay for a property.
Consider two otherwise identical houses. If one carries a substantially lower annual property-tax bill, a purchaser can afford to devote more money to its mortgage. When many buyers make similar calculations, part of the tax saving becomes incorporated into the house’s purchase price.
Economists call this tax capitalisation. The Federal Reserve Bank of Minneapolis explains how higher property taxes can lower upfront home prices, potentially benefiting younger or financially constrained buyers who struggle to assemble large down payments.
This does not mean raising property taxes automatically makes owning a home cheaper overall. Buyers must still pay the recurring tax, and existing owners can face genuine financial pressure. The distribution of costs changes: less of the total housing expense may be paid upfront to the seller, while more is paid over time through taxation.
California’s Proposition 13 is a prominent example of how property-tax rules influence the housing market.
Approved in 1978, Proposition 13 generally limits the basic property-tax rate to 1% of assessed value, apart from specified additional charges, and limits annual increases in a property’s assessed base value to 2% in most circumstances. Properties are generally reassessed when ownership changes or qualifying new construction occurs. The California State Board of Equalization explains the assessment framework, including how assessed values can differ from market prices.
As property values rise, longtime homeowners can end up paying taxes on assessments far below what their homes would command if sold today. A recent buyer of a comparable property may face a much higher assessed value simply because the purchase occurred later.
Warren Buffett highlighted this disparity during Arnold Schwarzenegger’s 2003 California gubernatorial campaign. Buffett described a home in Omaha valued at approximately $500,000 with an annual property-tax bill of $14,401, while his much more valuable Laguna Beach property reportedly carried a bill of only $2,264.
The comparison illustrated how acquisition-based assessments could produce enormous differences between properties with different ownership histories. The politics were equally revealing: proposals perceived as threatening Proposition 13 were extraordinarily controversial, even when their distributional effects seemed difficult to defend.
The arrangement also creates a potential lock-in effect. Homeowners who have benefited from years of favourable assessments may have less incentive to move because purchasing another property could reset their taxable value. An older couple might remain in a large house after their children leave, while a younger family searches for a suitable home nearby.
Property-tax rules are not the only reason people stay in their homes, and California has provisions that allow some owners to transfer assessments under specified conditions. Nevertheless, tax treatment can influence mobility and the allocation of existing housing.
There is also a distinction between taxing land and taxing the buildings constructed on it.
Economists and thinkers including Adam Smith, David Ricardo, John Stuart Mill, Henry George, and Milton Friedman recognised arguments for taxing land values. Land is fixed in location and supply, and much of its value comes from surrounding economic activity and public investment rather than the owner’s individual efforts.
A land-value tax focuses on the underlying site instead of the structures built upon it. Unlike a conventional tax that also increases when an owner makes improvements, a properly designed land-value tax does not directly penalise constructing additional apartments or renovating a building.
This can encourage more productive use of valuable sites. An owner holding an underdeveloped plot near a railway station would still owe tax on its land value, whether the site accommodated one house, several apartments, or remained largely unused.
Land taxation is not a complete affordability solution, and reforms require careful assessment, transition rules, and protection for vulnerable owners with valuable property but limited cash income. Its significance is that it offers a way to capture some of the value created collectively by urban growth without discouraging construction as directly as taxes on improvements can.
Why Home Sale Profits Receive Special Treatment
Recurring property taxes are only one part of the financial advantage associated with owner-occupied housing. Many countries also provide preferential tax treatment when homeowners sell their principal residences.
Canada offers a particularly important example.
Under Canada’s principal-residence exemption, eligible capital gains from the sale of a qualifying principal residence may be exempt from taxation. The rules depend on factors such as designation, ownership, use, reporting, and the period during which the property qualifies. Anti-flipping provisions and other restrictions also apply.
For a homeowner who purchased a property decades earlier, the exemption can protect a substantial increase in wealth from capital-gains taxation.
Compare that with someone earning a salary or operating a profitable business. Their income is generally subject to taxation as it is earned. Depending on the country’s tax rules, gains from financial investments, business assets, or additional properties may also face taxes that do not apply in the same way to qualifying gains on a family home.
There are defensible reasons for treating a principal residence differently. Homeowners need somewhere to live after selling, and taxing the entire gain could make relocating or replacing a home more difficult. Inflation also complicates the distinction between nominal appreciation and genuine increases in purchasing power.
Nevertheless, favourable treatment changes incentives. When an asset can appreciate substantially and qualifying gains receive preferential taxation, households have another reason to concentrate wealth in owner-occupied property.
That matters because housing already combines shelter, savings, collateral, and investment in one asset. Tax advantages can strengthen its attraction relative to other uses of capital, although the scale of any resulting displacement of productive business investment cannot simply be assumed.
The political consequences are significant too. Once households build financial plans around favourable treatment of housing wealth, reform becomes difficult. Governments must weigh the potential benefits of more neutral taxation against legitimate concerns about retirement savings, mobility, and fairness to people who purchased under the existing rules.
Preferential treatment of home-sale profits is therefore not the sole cause of unaffordability. It is another part of a system that can make property ownership financially attractive while leaving new entrants to pay increasingly high prices.
Why Cities Load the Cost of Growth onto New Homes
Cities need money to support growth. More residents require roads, water connections, sewers, public transportation, schools, parks, emergency services, and other infrastructure. Providing those services is expensive, and the costs cannot simply be ignored.
One way to finance them is through recurring taxes on the existing property base. Another is to charge developers when new housing is constructed.
Many municipalities rely on development charges, impact fees, infrastructure levies, and related contributions. These can be justified by the principle that growth should help pay for the infrastructure it requires. Existing residents reasonably object to bearing every cost associated with additional development.
However, fees on new housing can become problematic when they are large, unpredictable, or poorly aligned with the actual costs of servicing development.
Imagine a builder considering a small apartment project. The developer must pay for land, construction, financing, professional services, approvals, and infrastructure contributions. If the expected selling price cannot cover those costs and provide an adequate return for the risk, the project may never proceed.
Increasing development charges can change that calculation. Some projects become less profitable, some are delayed, and others may be abandoned. Smaller infill developments can be particularly vulnerable when fixed approval and infrastructure costs are spread across relatively few homes.
But who ultimately pays the fees is more complicated than simply saying developers pass every additional dollar to buyers.
In competitive land markets, developers may respond to higher charges by offering less for development sites. This shifts part of the burden onto landowners. In other circumstances, fees may contribute to higher sale prices, reduce the amount of housing built, or change which projects are economically attractive.
An empirical study of impact fees in Miami-Dade County by Keith Ihlanfeldt and Timothy Shaughnessy found that higher fees were associated with higher prices for new and existing houses and lower values for undeveloped residential land.
Other evidence challenges the idea that higher charges necessarily translate into higher prices. Cameron Murray’s research on developer charges in Queensland used natural experimental conditions and found no identifiable house-price increase attributable to the charges in the setting studied.
These findings are not interchangeable, but they illustrate an essential distinction: the legal responsibility for paying a fee is not necessarily the same as its eventual economic burden.
Market demand, available land, alternative development opportunities, financing conditions, and expectations about future taxes all influence the outcome.
The infrastructure benefits also matter. A fee that finances an essential sewer expansion or a new transport connection can make additional housing possible. The relevant question is whether the charging system funds necessary services efficiently or creates avoidable barriers to construction.
Problems become especially serious when cities protect existing homeowners from recurring tax increases while relying heavily on new development to fund municipal needs. The political burden then falls disproportionately on people who have not yet purchased homes or moved into the area.
Builders may respond by prioritising projects with stronger margins, including more expensive units, while cheaper or less conventional housing becomes difficult to justify. Complex approval requirements add uncertainty, requiring investors to account for the possibility of delays or rejection.
It is tempting to explain expensive new housing entirely through developer greed. Developers certainly seek profits, but their incentives operate within rules established by governments. When land is scarce, approvals are uncertain, and construction carries high financing and regulatory costs, blaming builders alone obscures how those conditions shape prices.
A better system would transparently finance genuine infrastructure needs while avoiding unnecessary penalties on the additional housing that growing cities require.
How Global Wealth Enters Local Housing Markets
Housing is purchased in local markets, but the money used to buy it can come from anywhere in the world.
That distinction matters in desirable cities with limited housing supply. Local residents generally depend on wages earned in the local economy, while international buyers may draw on accumulated wealth, businesses, or asset sales in other countries.
When wealthy purchasers compete for a fixed number of homes, property prices can become increasingly disconnected from what local salaries can support.
Portugal provides a useful example of how governments can actively encourage these capital flows.
Following the eurozone debt crisis, Portugal introduced its residence-by-investment programme, commonly called the golden visa, in 2012. Eligible foreign investors could obtain residence rights through qualifying investments, including real estate purchases under the rules that existed at the time.
Portugal also introduced a non-habitual resident tax regime intended to attract certain professionals, retirees, and internationally mobile residents through favourable tax arrangements. The two programmes had different eligibility requirements, but both formed part of efforts to attract foreign wealth and economic activity.
The benefits were understandable. Portugal wanted investment, employment, and economic recovery. Property purchases could support construction, renovation, financial services, legal work, and local spending.
However, attracting wealthy purchasers into housing markets with limited supply also created distributional problems. Sellers and property-related businesses could benefit from stronger demand, while residents dependent on Portuguese wages faced more intense competition.
Research by the International Tax Observatory on Portugal’s golden-visa programme found evidence of a premium around the €500,000 investment threshold. Its analysis identified transaction prices exceeding fiscal values by an average of approximately €38,000 at that threshold, suggesting a substantial effect in the relevant high-end market segment.
That is meaningful evidence of a policy-related price distortion. It is not proof that international investors were responsible for all Portuguese housing inflation.
Portugal’s problems also reflect restrictions on construction, insufficient housing supply in high-demand locations, difficulties moving between homes, and other regulatory and tax factors. The OECD’s 2026 housing assessment of Portugal examines these structural constraints alongside international demand.
Portugal removed real estate purchases as a qualifying golden-visa investment route in October 2023. The original non-habitual resident regime was also closed to most new entrants and replaced by a narrower incentive framework. These changes are important because the earlier arrangements should not be described as though they remain available unchanged.
Vancouver offers another example of controversy surrounding foreign wealth and residential property. International investment became an important political issue in its housing market, particularly in expensive neighbourhoods. Canada’s Quebec Immigrant Investor Program has also attracted scrutiny because participants’ eventual settlement locations may differ from the province through which they apply.
The current Quebec programme, however, has specific investment, contribution, and residence requirements. It is not accurately described as an unrestricted exchange of a payment for immediate permanent residency.
Cities including London, Sydney, Melbourne, and Auckland have faced related debates about international buyers, investment property, and housing affordability. Yet the circumstances differ, and foreign capital cannot be assumed to have the same effect everywhere.
Nor should wealthy immigrants or foreign purchasers become convenient scapegoats for failures of domestic housing policy. People who relocate may work, start businesses, pay taxes, and contribute to their communities. Foreign investment can support productive economic activity, not merely property speculation.
The central issue is how capital enters a housing market and whether additional supply can respond. When a government encourages property investment while restricting construction, extra purchasing power can intensify competition for existing homes. When the market can add housing more readily, the same increase in demand may produce a larger construction response and less sustained pressure on prices.
Foreign capital can therefore amplify a housing shortage, but it does not eliminate the responsibility of domestic governments to address the conditions that make housing scarce.
Government Mortgage Guarantees and Buyer Subsidies
When homes become unaffordable, governments often respond by helping households obtain mortgages or accumulate larger down payments. These programmes can provide immediate relief, but they may also increase purchasing power without increasing the number of available homes.
Canada illustrates both the benefits and the difficulties of this approach.
Its housing-finance system involves extensive public support through CMHC, which provides mortgage insurance and supports securitisation programmes. Mortgage insurance protects eligible lenders against qualifying borrower defaults, while government-backed mortgage securities allow investors to receive payments supported by specified guarantee arrangements.
These mechanisms can help lenders obtain funding, support mortgage-market liquidity, and make housing finance more accessible. They also create public financial exposure, which CMHC has discussed in its explanation of mortgage risk-sharing.
The distinction between the different guarantees matters. Mortgage default insurance protects against specified credit losses, while guarantees associated with mortgage-backed securities address payments to investors under the programme’s rules. Neither means that the government guarantees an individual home’s resale value or promises to prevent house prices from falling.
Nevertheless, public support can influence how cheaply and readily mortgage credit is supplied. When borrowing becomes easier, households may qualify for larger loans and compete more aggressively for property.
Canada also offers savings arrangements such as the First Home Savings Account and the Home Buyers’ Plan, which provide qualifying households with tax-advantaged ways to accumulate or access funds for home purchases.
These programmes can genuinely help individual buyers. A household that struggles to save a down payment may benefit substantially from the available tax advantages or withdrawal rules.
But individual assistance and market-wide affordability are not the same thing.
Suppose a neighbourhood has 100 homes available and 200 households competing to purchase them. If the government increases the purchasing power of those households without changing the supply of homes, sellers may be able to charge more. Some assisted buyers gain access to the market, while unsuccessful households face higher prices.
The size of this effect depends on how assistance is designed, who receives it, and whether builders can respond by constructing more housing.
CMHC examined precisely this problem in its April 2026 analysis of demand-side housing interventions and supply. Its modelling found that broader assistance can worsen affordability over time when housing construction does not sufficiently expand, while targeted programmes and matching supply increases can reduce adverse effects.
This explains why policies that help people borrow or save more money cannot independently solve a structural shortage.
Governments may also adjust mortgage qualification rules, amortisation periods, and other lending conditions to reduce immediate financial pressure. Such changes can be valuable for particular borrowers, but easier credit can also support higher purchase prices when housing supply remains constrained.
The problem extends beyond housing itself. Property costs interact with wages, household debt, taxes, infrastructure, and broader economic performance. Canada’s housing difficulties are therefore closely connected to the wider pressures explored in Why Canada is So Expensive to Live In.
The strongest housing assistance policies recognise the difference between helping vulnerable households and expanding the market’s productive capacity. Assistance may be justified for reasons of fairness or financial stability, but it should not become a substitute for allowing enough homes to be built.
Otherwise, governments risk helping some households purchase expensive homes while leaving the underlying market just as unaffordable.
The Cost of Letting the Housing System Fail
Once housing becomes central to household wealth and financial stability, governments face another problem: a significant decline in property prices can have consequences far beyond the real estate market.
Households use property as a major store of savings. Banks accept homes as collateral for mortgages. Developers borrow against the expected value of future projects. Construction supports employment and purchasing throughout the economy, while local governments receive revenue associated with property ownership and development.
A sharp housing downturn can affect all these relationships simultaneously.
When property prices decline, recent buyers may owe more than their homes are worth. Households can reduce spending as their perceived wealth falls. Developers may cancel projects, construction workers may lose employment, and banks can experience rising defaults and weaker collateral values.
These effects are especially dangerous when lending standards are weak, borrowers carry substantial debt, and financial institutions depend heavily on real estate.
Japan’s economic crisis offers a historical example.
During the late 1980s, Japan experienced an enormous property and stock-market bubble. Rising land values supported lending and encouraged further speculation. Financial institutions increasingly relied on inflated asset valuations, while borrowers and investors operated under expectations that had become difficult to sustain.
When the bubble burst in the early 1990s, land and share prices fell sharply. Banks were left with large volumes of troubled loans, businesses faced financial distress, and the economy entered a prolonged period of weak growth.
Japan’s authorities eventually committed substantial public resources to stabilising the banking system. In October 1998, the government expanded the authorised financial-sector support package to ¥60 trillion.
The International Monetary Fund’s account of Japan’s banking crisis explains that the package included ¥25 trillion for recapitalising weak but solvent banks, ¥18 trillion for resolving insolvent institutions through mechanisms including nationalisation, and ¥17 trillion for protecting depositors.
These amounts represented authorised support for several financial-stability functions, not a single ¥60 trillion purchase of bad real estate loans.
Japan’s experience illustrates the dangers of allowing speculative asset values and financial institutions to become deeply intertwined. However, its prolonged stagnation cannot be attributed solely to bank rescues. Delayed recognition of bad loans, weak corporate balance sheets, demographic and structural changes, and broader policy decisions also shaped the aftermath.
The United States faced a different housing-related financial crisis in 2008. Risky mortgage lending, securitisation practices, excessive leverage, and falling home prices contributed to widespread financial distress. Government intervention was intended to prevent a deeper collapse of institutions and credit markets.
These crises explain why authorities sometimes intervene even when private investors have made serious mistakes. Allowing major banks to fail disorderly can harm depositors, businesses, workers, and households that never participated in property speculation.
But rescue expectations can create moral hazard. If investors believe financial institutions will always receive public support when housing-related risks become systemic, they may have weaker incentives to avoid excessive exposure.
Not every government intervention is a bailout, however.
Canada’s purchases of Canada Mortgage Bonds demonstrate the importance of distinguishing different policies. Its 2024–2025 Debt Management Report records approximately CAD $28.75 billion in additional purchases during that fiscal year. The government described the measure in terms of debt management, funding savings, and support for housing-related priorities.
Such purchases can influence financial-market conditions, but they are not equivalent to nationalising a failed bank or guaranteeing that homeowners will never suffer capital losses.
The political difficulty is broader than any individual intervention.
If prices decline sharply, governments face pressure from homeowners, banks, developers, and other groups exposed to real estate. If prices keep rising faster than incomes, renters and future buyers become increasingly excluded.
Politicians therefore have incentives to pursue policies that appear to improve affordability without openly reducing existing property wealth. They may subsidise buyers, support mortgage credit, or promise additional construction while reassuring homeowners that their investments will remain protected.
This tension cuts across political parties. Housing ownership is widespread, and people who depend on their homes for financial security do not necessarily vote according to conventional ideological divisions.
The danger is that protecting the housing system from every possible decline can reinforce expectations of continuous appreciation. Over time, those expectations may encourage borrowing, speculation, and resistance to reforms that would otherwise moderate prices.
A stable financial system is important. But financial stability should not be confused with a permanent government obligation to preserve ever-rising property values.
What Affordable Housing Would Actually Require
There is no single policy capable of resolving an expensive housing market. Affordability depends on construction capacity, population and household growth, income, credit conditions, taxation, infrastructure, and the availability of homes in desirable locations.
The most important starting point in supply-constrained cities is to make it easier to construct additional housing where demand already exists.
That means allowing more apartments, townhouses, duplexes, and other missing-middle homes in established neighbourhoods, particularly near jobs, transport, and public services. It also means reducing unnecessary approval delays, providing predictable building rules, and coordinating new construction with the infrastructure required to support it.
More construction does not guarantee an immediate decline in every property price. Housing is expensive and slow to produce, and desirable locations retain value. However, allowing supply to respond to demand can reduce the pressure that would otherwise accumulate on existing homes.
The scale of the challenge is substantial. CMHC’s 2025 housing-supply gaps assessment examines the additional construction needed to improve Canadian affordability by 2035. Its estimates highlight that financial assistance alone cannot replace the physical production of housing on the required scale.
Tax reform is another important component.
Governments can examine whether recurring land and property taxes are designed in ways that encourage efficient land use, discourage unnecessary speculation, and distribute the benefits of public infrastructure more fairly. A greater focus on land value can potentially reduce the incentives to hold valuable urban sites without developing them.
Reforms must nevertheless account for homeowners with limited incomes, particularly older residents who could face significant tax bills without corresponding cash flow. Deferrals, phased transitions, targeted relief, and other protections can help address these concerns without permanently exempting valuable land from appropriate taxation.
Municipal finance also needs attention. Cities require sustainable sources of revenue to fund infrastructure, but financing methods should not make otherwise viable housing projects impossible. Development charges should be transparent, proportionate, and evaluated against their effects on construction, land prices, and long-term public costs.
Foreign-investment programmes deserve similar scrutiny. Governments should distinguish investment that creates productive activity and additional housing from incentives that primarily increase competition for an existing stock of scarce properties. Restrictions on speculative activity may be appropriate in certain markets, but blaming foreign purchasers cannot substitute for addressing domestic supply barriers.
Housing assistance should be carefully targeted and coordinated with construction. Support for low-income households, first-time buyers, and people facing immediate housing insecurity can have substantial social value. Yet broad subsidies that mainly increase borrowing capacity may achieve little if sellers capture much of the benefit through higher prices.
There is also an essential role for rental housing and tenant protection.
Not everyone wants to purchase a home, and ownership should not be the only route to housing security. A functioning market needs a range of options, including private rentals, non-profit housing, social housing, and homes suited to different household sizes and incomes.
Tenant protections can help prevent displacement and instability, while affordable and social housing can serve people whose needs the private market does not adequately meet. These measures require careful design alongside supply expansion so that immediate protections do not unintentionally worsen longer-term shortages.
Finally, policymakers need to distinguish improved affordability from a destructive housing crash.
Housing can become more affordable when construction expands, rents grow more slowly, and household incomes rise faster than property prices over a sustained period. In some overheated markets, nominal price declines may also be part of an adjustment. None of these outcomes necessarily requires a banking collapse or widespread foreclosure.
An orderly adjustment is preferable to a sudden financial crisis, especially for heavily indebted households. The objective should be a housing system in which people can afford suitable accommodation without depending on unsustainable increases in debt or property values.
The greatest obstacle is political rather than technical. Reforms can reduce expected windfalls for some landowners, alter neighbourhoods, change tax obligations, and disappoint investors who assumed prices would keep rising rapidly. The costs of the existing system, meanwhile, are spread across renters, young households, longer commuters, and people who have postponed forming families or moving for work.
These groups do not have equal political power, even when their combined economic losses are substantial.
Governments therefore face a genuine choice about which outcomes their policies should favour. They can continue protecting the financial expectations created by decades of rising property values, or they can gradually redesign the system to provide more abundant and affordable housing.
Housing became expensive through a combination of economic demand, restricted supply, financial incentives, and political choices. Those forces differ across countries, but they often reinforce one another in the same direction.
Existing homeowners generally did not design the system. Many bought homes to provide security for their families, responded rationally to available incentives, and came to rely on property wealth for their future. Recognising their legitimate interests does not require treating every increase in housing prices as a public good.
Solving the crisis does not mean making homeownership worthless or deliberately destroying household wealth. It means allowing housing to become more affordable without demanding that existing assets appreciate faster than the incomes of the people who need somewhere to live.
A society can support homeownership, encourage savings, and protect financial stability while permitting more construction and better-designed taxation. What it cannot sustainably promise is that homes will become increasingly accessible to new buyers while simultaneously delivering exceptional, uninterrupted appreciation to every existing owner.
Housing affordability ultimately depends on resolving that contradiction. Until governments are willing to prioritise the availability of shelter when it conflicts with the expectation of continuously rising property wealth, their promises to make housing affordable will remain difficult to fulfil.
Last Updated on October 18, 2026 by Aseem Gupta