Reading Time: 11 Minutes
Imagine applying for a $300,000 mortgage. The bank reviews your income, checks your credit history, considers the property and approves the loan. You might picture it finding $300,000 in savings deposited by other customers and transferring that money to you. That seems like the natural way a bank would lend: collect money from people who have it, then pass it to people who need it.
But modern commercial banking works differently. When a bank makes a loan, it can create a new deposit at the same time. Money that did not previously exist as a bank-account balance becomes available for someone to spend. If that sounds like a remarkably powerful privilege, it is. The puzzle is why banks still struggle, fail and occasionally need rescuing when they can create money in the first place.
The answer lies in the difference between creating a spendable deposit and creating wealth. To see it clearly, follow one mortgage from the moment it is approved to the moment it is repaid.
What Is Money, and How Is a Bank Deposit Different From Cash?
Money is whatever people can readily use to make payments, although different forms of money work in different ways. Notes and coins are the most visible form, but much of the money households and businesses use consists of balances recorded in commercial-bank accounts. When you pay a bill electronically, your bank usually does not dispatch a bundle of notes to the recipient. It adjusts account records and, when necessary, settles with another bank.
That means the $5,000 displayed in your current account is not ordinarily a marked pile of cash sitting untouched in a vault. It is the bank’s obligation to pay you or transfer value on your instructions. From your perspective the deposit is an asset: you can use it to buy groceries, pay rent or settle a bill. From the bank’s perspective the same $5,000 is a liability, because the bank owes it to you.
Commercial-bank deposits should also be distinguished from central-bank reserves. Reserves are balances eligible banks hold at a central bank and use, among other things, to settle payments between institutions. Households cannot normally pay their electricity bills by transferring central-bank reserves. Cash, commercial-bank deposits and reserves are connected parts of the monetary system, but they are not interchangeable entries on the same balance sheet.
This distinction matters because a commercial bank can create a new deposit when it extends credit. It cannot, merely by recording a mortgage, conjure up the central-bank reserves it may need when that deposit moves to another institution. The ability to make a loan therefore begins one financial process rather than removing every obligation that follows.
How a $300,000 Mortgage Creates New Money
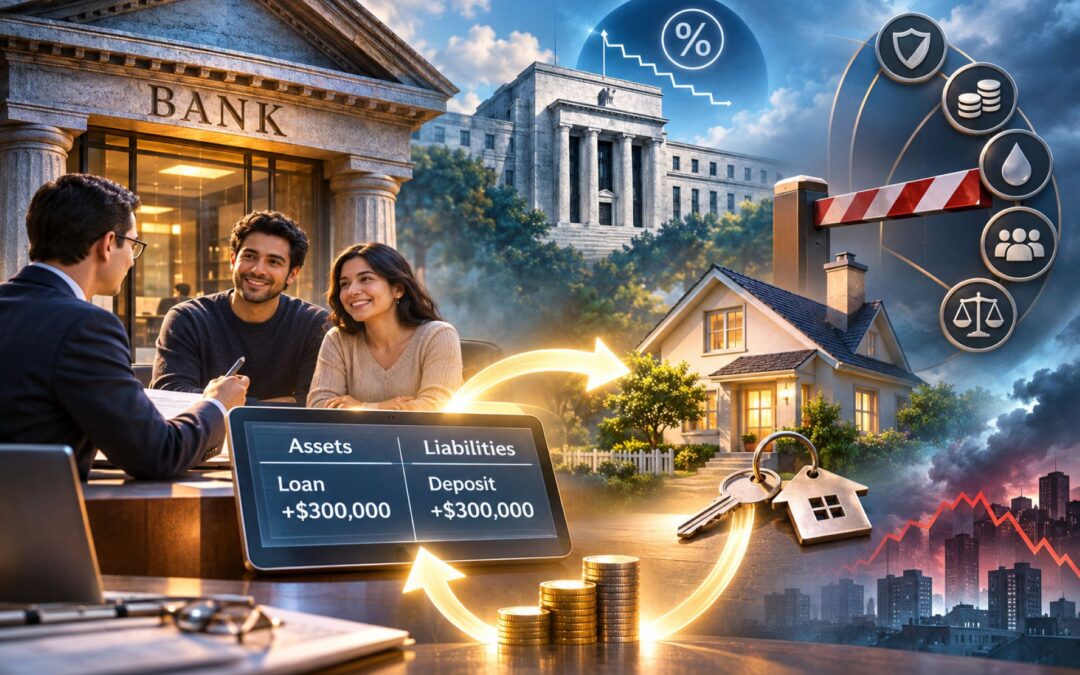
Suppose you qualify for a $300,000 mortgage and the bank approves it. At the moment the loan is made, the bank records two matching entries. It adds a $300,000 loan to its assets, representing your contractual obligation to repay the principal with interest. It also credits your account with a $300,000 deposit, representing the bank’s obligation to honour your payments and withdrawals.
The entries balance: the bank acquires a $300,000 asset and takes on a $300,000 liability. You acquire $300,000 of spendable deposit money, but also a $300,000 debt. Nothing in those entries requires another saver to see their account reduced by $300,000. This is the central point of the Bank of England’s explanation of money creation in the modern economy: banks do not simply lend out a predetermined stock of customer deposits.
The new deposit counts as money because it can be used to purchase goods and services. Yet the bank has not made an effortless $300,000 profit. Its asset is a promise of future repayments, not a suitcase of guaranteed cash, and its new liability can be called upon immediately when you spend. If you never repay, the apparently valuable loan can turn into a loss while the bank still has obligations to depositors and other creditors.
There are real economic consequences to this accounting. A mortgage can enable a transaction that otherwise could not take place. A business loan can finance equipment, inventory or expansion before the business earns the revenue to pay for it. Lending brings purchasing power into the present against expected future income, which is why credit can support productive activity and also why excessive borrowing creates danger.
What Happens When the Borrower Spends That Money?
The $300,000 becomes useful when you pay the seller of the house. If the seller keeps an account at your bank, the payment is comparatively straightforward: your deposit balance falls by $300,000 and the seller’s rises by $300,000. The bank now owes the seller rather than you. Your mortgage debt remains, but there has not been a second creation of $300,000 merely because the payment changed hands.
Now suppose the seller uses another bank. Your bank must arrange for the seller’s bank to receive payment, typically through the banking system’s settlement arrangements. The seller’s bank credits the seller’s deposit account, while the banks transfer settlement funds between themselves. As the Swiss National Bank explains in its account of money creation, lending, deposit creation and the transfer of funds between banks must be understood together.
This reveals a practical constraint that the initial loan entry does not show. Your bank may have created a deposit without first finding a particular saver to fund the mortgage, but when your payment leaves the bank it needs the liquid resources to settle that transfer. It might use reserves it already holds, attract deposits, borrow from other institutions, sell liquid assets or obtain eligible central-bank funding under applicable conditions. Each route has a cost or limitation.
The seller still has the $300,000 deposit at the end of the transaction, while you still owe $300,000 on the mortgage. What has disappeared is your original deposit balance after you paid the seller; it has not remained in your account alongside the seller’s receipt. At the level of the banking system, the new purchasing power can continue circulating, even as the lender must manage its own funding and settlement position.
This difference between a single bank and the entire banking system explains much of banking’s apparent paradox. The system can expand deposit money through credit, but individual institutions can lose deposits and reserves to competitors whenever customers make payments. They cannot treat a newly created balance as a free supply of settlement cash.
Why Can’t Banks Create Unlimited Money?
The first limitation is capital. Bank capital is the owners’ residual stake in the institution, providing a buffer against losses. A mortgage may be recorded as a $300,000 asset when issued, but its value depends on the borrower’s ability to repay and the bank’s prospects of recovering money if the borrower defaults. If enough loans deteriorate, losses erode the bank’s capital and can ultimately leave it insolvent.
Regulators therefore require banks to maintain capital in relation to their exposures, alongside other safeguards. Lending expands a bank’s assets and risks, but does not automatically provide an equivalent increase in the shareholders’ capital that must support them. A bank that wants to grow its loan book may need to retain earnings, raise new capital or reduce other risks. The exact requirements depend on the jurisdiction and institution, but the underlying constraint cannot be abolished by typing a larger number into a customer’s account.
Liquidity is a different problem. A bank can own assets that are valuable over many years and still be unable to meet payments due this afternoon. Mortgages are typically repaid gradually; withdrawals, account transfers and other funding obligations may arrive immediately. The Federal Reserve’s discussion of the difference between bank liquidity and capital helps clarify why a bank needs both the ability to absorb losses and access to funds when obligations come due.
A solvent bank may face a liquidity crisis if too many depositors withdraw funds at once or if other lenders refuse to renew short-term funding. A bank with abundant liquidity, meanwhile, can still fail if its borrowers suffer losses so severe that its assets no longer cover what it owes. Financial stability requires attention to both risks; neither an impressive deposit balance nor access to emergency liquidity is a substitute for sound lending.
Funding also has a price. A bank may need to pay interest to attract deposits or borrow from wholesale markets, while its mortgage income arrives over time. It must cover operating costs, expected credit losses, regulatory requirements and the risk that market interest rates will change. Creating a loan is not the same as earning a return from it: if the borrower pays too little relative to these costs, or never pays at all, the bank can lose money.
Then there is the borrower. Banks need applicants who actually want credit and can plausibly repay it. A household with insufficient income cannot safely support any mortgage simply because the bank has the technical ability to create the corresponding deposit. Businesses may postpone investment when sales are weak, and borrowers may reject loans when interest rates are too high. Banks can advertise credit, but they cannot manufacture an unlimited supply of worthwhile lending opportunities.
These interacting limits explain why the familiar story of a rigid money multiplier is incomplete. It is misleading to imagine banks first collecting a fixed quantity of reserves and then mechanically lending a predetermined multiple of that amount. In practice, banks evaluate profitable lending opportunities while managing capital, liquidity, funding and monetary-policy conditions. The Deutsche Bundesbank’s explanation of money creation emphasises that creating book money does not release banks from the economic and regulatory constraints of banking.
These limitations become especially visible when confidence breaks down. If customers fear that a bank cannot honour withdrawals, they may rush to move their deposits elsewhere. Because long-term loans cannot always be converted into cash quickly without losses, heavy withdrawals can turn anxiety into a bank run. Deposit insurance, supervision and central-bank liquidity facilities can reduce the danger, but none makes careless lending harmless.
How Central Banks Influence Lending and Property Prices
Commercial banks make individual lending decisions, but central banks strongly influence the financial conditions under which those decisions are made. Institutions such as the Federal Reserve, the Bank of England and the Reserve Bank of India use monetary-policy tools to affect short-term interest rates and wider borrowing costs. They also support payment-system functioning and, within their mandates, financial stability.
When policy rates rise, banks often face higher funding costs and borrowers encounter more expensive credit. A household that could comfortably meet the monthly payments on a particular mortgage at one interest rate may qualify for a smaller loan at a higher rate. Businesses may postpone investments whose expected returns no longer justify the financing cost. Lending can weaken even though banks retain the accounting ability to create deposits.
Lower rates can work in the opposite direction, supporting borrowing and spending, but the relationship is not automatic. Banks may remain cautious when unemployment is rising, consumers may avoid new debt and businesses may see little reason to expand. Central banks influence incentives and financial conditions; they do not directly decide the fate of every mortgage or command commercial banks to lend without regard to risk.
Housing illustrates why this matters. When more households can borrow larger sums, they can bid more for the same limited stock of homes. If construction cannot respond quickly, some of the easier credit may show up as higher prices rather than additional housing. Conversely, rising mortgage rates can weaken demand, although land availability, household incomes, construction, demographics and local regulations also influence prices. The wider interaction between property valuation, mortgage leverage and investment risk is explored in The Economics of Real Estate.
Banks therefore have influence over property markets without controlling them. Lending determines part of the purchasing power buyers bring to the market, while the supply of homes and the expectations of sellers and investors determine how that purchasing power translates into prices. Easy credit can finance genuine homeownership and building; when paired with unrealistic expectations, it can also inflate the value of existing assets.
What Happens to Money When a Loan Is Repaid?
Return to the mortgage. Suppose that after making regular payments you repay $10,000 of its principal. The bank reduces your outstanding loan balance by $10,000. When that payment is made from a bank deposit, the corresponding deposit liability also falls by $10,000 across the banking system, allowing for any interbank settlement involved. The repayment reverses part of the original loan creation.
This is why economists say repayment of bank-loan principal destroys deposit money. Nothing physical has to be shredded. The loan asset and the deposit liability are both reduced, removing purchasing power that lending had previously introduced. Nor does repayment require you to hand back the identical electronic dollars first credited to your account; deposits circulate and the money used to repay a loan may have come from wages, a sale or another payment.
Interest follows a different path. If part of your monthly payment covers interest, that portion is revenue to the lender rather than a reduction in the amount originally borrowed. The bank can use its income to pay employees, rent, technology providers, deposit interest, taxes and other expenses, or eventually distribute profits. Those payments send purchasing power back into the economy. Interest is therefore not simply erased in the same way that repayment of principal extinguishes the loan balance.
For the individual borrower, however, the practical burden is real: monthly payments include both principal and interest, and a longer or more expensive loan may require substantially more cash over its life than the amount borrowed. That does not mean the financial system must create a separate permanent stock of money equal to all future interest at the outset. The same deposits can change hands repeatedly as people earn income, spend, repay debts and receive payments from banks and other businesses.
Credit creation and principal repayment are thus two sides of an ongoing process. When new lending exceeds repayments and other changes, the stock of bank deposits can expand; when repayment and contraction dominate, deposit money can shrink. The path of money in the economy depends on much more than the amount approved in any single mortgage application.
When Bank Lending Fuels a Financial Crisis
The ability to create deposits makes credit expansion powerful, but it does not guarantee that the activities being financed will generate enough income to support the resulting debts. During an economic boom, borrowers may feel secure, banks may compete to issue loans and rising property values may make collateral appear safer. Each new round of lending can support more spending and, in some markets, higher asset prices.
This can become self-reinforcing. As houses appreciate, homeowners feel wealthier, lenders perceive more collateral value and investors grow confident that another buyer will pay a higher price later. Yet a rise in collateral prices does not necessarily improve a borrower’s income or capacity to service a mortgage. If lending standards deteriorate, the financial system becomes increasingly dependent on prices continuing to rise.
The United States experienced an extreme version of these risks before the global financial crisis. Many mortgages were extended to borrowers with weak credit profiles or under terms that became difficult to meet when rates reset or housing prices stopped climbing. Loans were packaged into mortgage-backed securities and other products held across the financial system, spreading exposure well beyond the original lenders. The Federal Reserve’s history of the subprime mortgage crisis describes how the housing downturn contributed to broader financial instability.
When house prices declined and borrowers defaulted, institutions faced falling asset values and mounting losses. Confidence in the securities and in the firms holding them weakened. Some banks and financial companies relied on funding that could disappear quickly, so doubts about their assets became liquidity problems as well as solvency problems. The collapse of Lehman Brothers in September 2008 helped turn an already serious crisis into a worldwide financial shock.
Money creation alone did not cause that disaster. Poor underwriting, leverage, securitisation incentives, opaque financial exposures, dependence on unstable funding and failures of oversight all mattered. A fuller account appears in The 2008 Financial Crisis Explained. The lesson for the mechanics of banking is that creating more deposits cannot make a bad loan good, eliminate losses or ensure that borrowers and institutions can meet their obligations.
Banks create money by accepting financial risks and commitments that extend into the future. When those commitments are managed responsibly, credit can help families buy homes and businesses invest before their income arrives. When obligations grow faster than borrowers’ capacity to repay, the same system can magnify a boom and deepen its collapse.
A bank approving a $300,000 mortgage is not handing over an untouched pile of another customer’s savings, nor is it granting itself $300,000 of free wealth. It is creating a deposit and a corresponding debt, then taking responsibility for the funding, settlement and risk that follow. Understanding both sides of that transaction explains why banks can create money—and why they cannot lend without limits.
Last Updated on November 10, 2026 by Aseem Gupta